










Mold-Tek Packaging's Pharma, Food volumes lift Q2 growth
Key highlights
- Mold-Tek Packaging’s Q2 FY2027 sales volume increased 10.08% year on year to 11,028.46 metric tonnes.
- Pharma packaging volume grew 26.30% and Food & FMCG packaging volume rose 23.70% in Q2 FY2027, offsetting a 12.32% decline in lubricants packaging.
- Q2 FY2027 revenue increased 30.73% to Rs 274.2253 crore, while EBITDA rose 29.80% to Rs 51.27 crore.
- H1 FY2027 profit increased 23.18% to Rs 46.64 crore, while sales volume grew 8.04% to 23,116.98 metric tonnes.
powered by IRIS
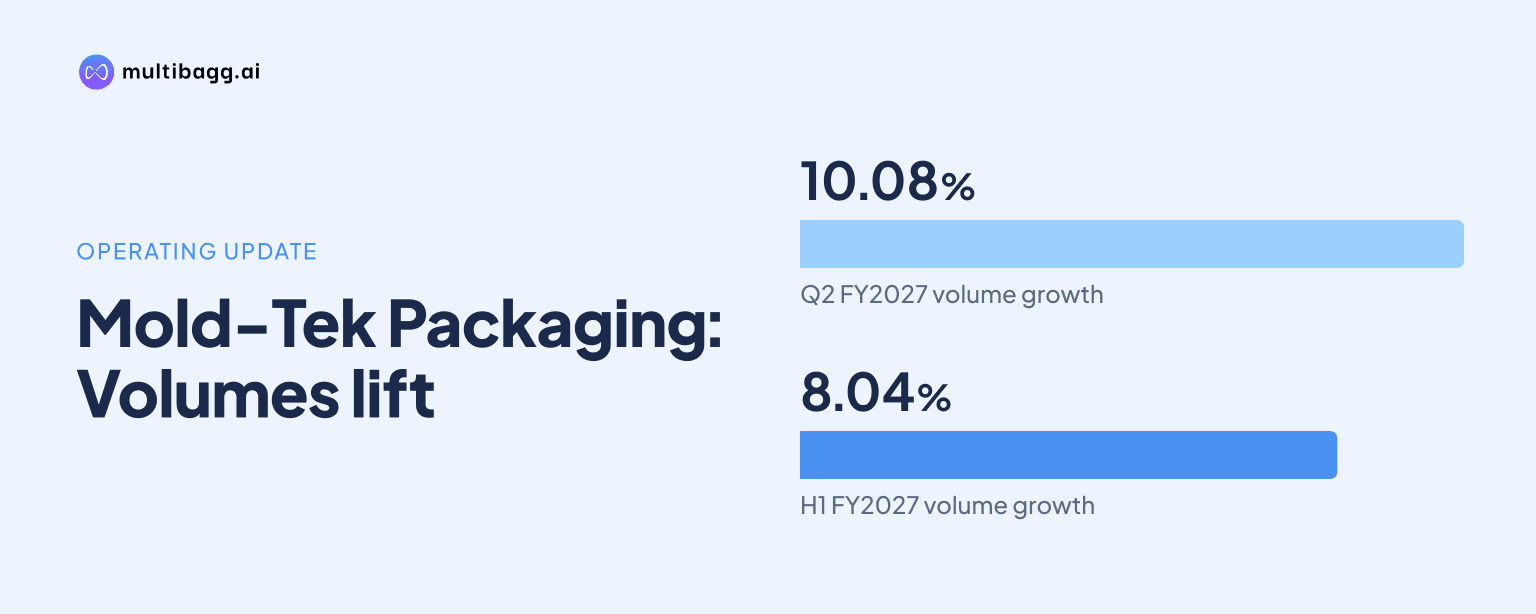
Mold-Tek Packaging Limited recorded 10.08% year-on-year sales-volume growth to 11,028.46 metric tonnes in Q2 FY2027, despite a 12.32% decline in lubricants packaging. Pharma packaging grew 26.30% and Food & FMCG packaging, including Q-Pack, rose 23.70%, offsetting the lubricants decline and accompanying revenue growth of 30.73% to Rs 274.2253 crore.
Know Mold-Tek Packaging inside out
Results, valuation, peers and who's buying, in one view.
Which segments drove Mold-Tek Packaging's Q2 volume growth?
Pharma packaging and Food & FMCG packaging drove Mold-Tek Packaging's Q2 FY2027 volume growth, rather than lubricants. Pharma packaging expanded 26.30% year on year, while Food & FMCG packaging, including Q-Pack, increased 23.70%. Paints packaging grew 8.61%, and these three categories more than offset the 12.32% decline in lubricants packaging.
Mold-Tek Packaging's total Q2 FY2027 sales volume rose to 11,028.46 metric tonnes from 10,018 metric tonnes in Q2 FY2026. The filing does not disclose tonnage or revenue by individual segment, but it says growth in pharma, Food & FMCG and paints collectively exceeded the decline in lubricants and produced the 10.08% overall increase.
Mold-Tek Packaging attributed the pharma increase to customer acceptance, a larger presence in pharmaceutical packaging, and demand from existing and new customers. For Food & FMCG, it cited demand for innovative and premium in-mould-labeling, or IML, packaging solutions. The company said Panipat Unit-14 contributed sales in North India and management expects Food & FMCG growth to sustain or improve in coming quarters.
How did Mold-Tek Packaging's Q2 financial performance compare?
Mold-Tek Packaging reported Q2 FY2027 revenue from operations of Rs 274.2253 crore, up 30.73% from Rs 209.7587 crore in Q2 FY2026. Revenue growth exceeded the 10.08% rise in sales volume, while the company reported an improved product mix and earnings before interest, tax, depreciation and amortisation, or EBITDA, per kg of Rs 46.49.
EBITDA increased 29.80% to Rs 51.27 crore from Rs 39.50 crore, according to the results presentation. Net profit increased 36.06% to Rs 21.09 crore in that presentation. The statutory quarterly results reported profit for the period of Rs 21.0689 crore, compared with Rs 15.4809 crore a year earlier.
Mold-Tek Packaging said Q2 FY2027 EBITDA per kg of Rs 46.49 was 30% above Q2 FY2026. Chairman and Managing Director J. Lakshmana Rao said raw-material prices had increased sharply and material availability was constrained by geopolitical disruptions, but pre-agreed customer pricing arrangements allowed the company to pass through higher input costs and protect operating margins.
Got a follow-up? Ask IRIS
What does Mold-Tek Packaging's first-half performance show?
Mold-Tek Packaging recorded lower volume growth in H1 FY2027 than in Q2 alone, while revenue and profit still increased faster than tonnage. H1 sales volume rose 8.04% to 23,116.98 metric tonnes from 21,395 metric tonnes in H1 FY2026, and revenue from operations increased 27.62% to Rs 574.6773 crore from Rs 450.3171 crore.
For the six months ended 30 September 2026, EBITDA grew 23.97% to Rs 107.70 crore from Rs 86.81 crore. Profit for the period rose 23.18% to Rs 46.64 crore in the statutory results from Rs 37.8816 crore in H1 FY2026, while the presentation reported net profit of Rs 46.67 crore.
The Q2 volume increase of 10.08% was above the 8.04% H1 growth rate, indicating that the second-quarter tonnage growth was faster than the first-half average. Mold-Tek Packaging linked the difference between H1 volume growth and profit growth to operational efficiencies and higher-margin segment contributions, but did not provide segment-level H1 volume data.
What plans could support Mold-Tek Packaging's packaging growth?
Mold-Tek Packaging is expanding pharma packaging through investment in advanced manufacturing capabilities, specialised packaging solutions and capacity enhancement. The company said its recently undertaken pharma-infrastructure investments are expected to support growth and increase the segment's contribution to revenue and profitability, although it did not disclose investment value or incremental capacity.
For Food & FMCG, Mold-Tek Packaging cited market opportunities, manufacturing capabilities and its customer base, including North India sales from Panipat Unit-14. It is also integrating printing facilities under one roof at Sultanpur, Telangana, an initiative management expects to streamline workflows, reduce operating costs, improve turnaround times and improve resource utilisation.
Mold-Tek Packaging said commercial production of IODEX containers is planned to start in Q3 FY2027, with revenue expected from Q4 FY2027. Other new packs for three multinational companies are under development and are also expected to add revenue from Q4 FY2027, while eye-dropper pack moulds are expected by Q4 FY2027 and commercial production is planned for Q1 FY2028.
Conclusion
Mold-Tek Packaging's Q2 FY2027 result shows that pharma and Food & FMCG were the main volume engines. Their respective 26.30% and 23.70% growth rates, alongside 8.61% growth in paints, outweighed the 12.32% lubricants decline and supported a 10.08% overall volume increase, 30.73% revenue growth and 29.80% EBITDA growth.
The next disclosed milestones are the planned Q3 FY2027 start of IODEX-container production, expected Q4 FY2027 revenue from new packs, and the projected Q1 FY2028 commercial start for eye-dropper packs. Investors and readers can also watch whether Panipat Unit-14 sustains Food & FMCG growth and whether the Sultanpur printing integration delivers the efficiencies management expects.