










Mufti working-capital days reach 217 as H1 operating cash falls
Key highlights
- Mufti’s working-capital cycle rose to 217 days in H1 FY27 from 196 days in FY26.
- Net cash from operating activities fell to Rs 4.2 crore in H1 FY27 from Rs 32.4 crore in H1 FY26.
- Trade receivables increased to Rs 285.2 crore at September 2026 from Rs 236.3 crore at March 2026.
- H1 FY27 profit after tax increased 18% year-on-year to Rs 29.6 crore.
powered by IRIS
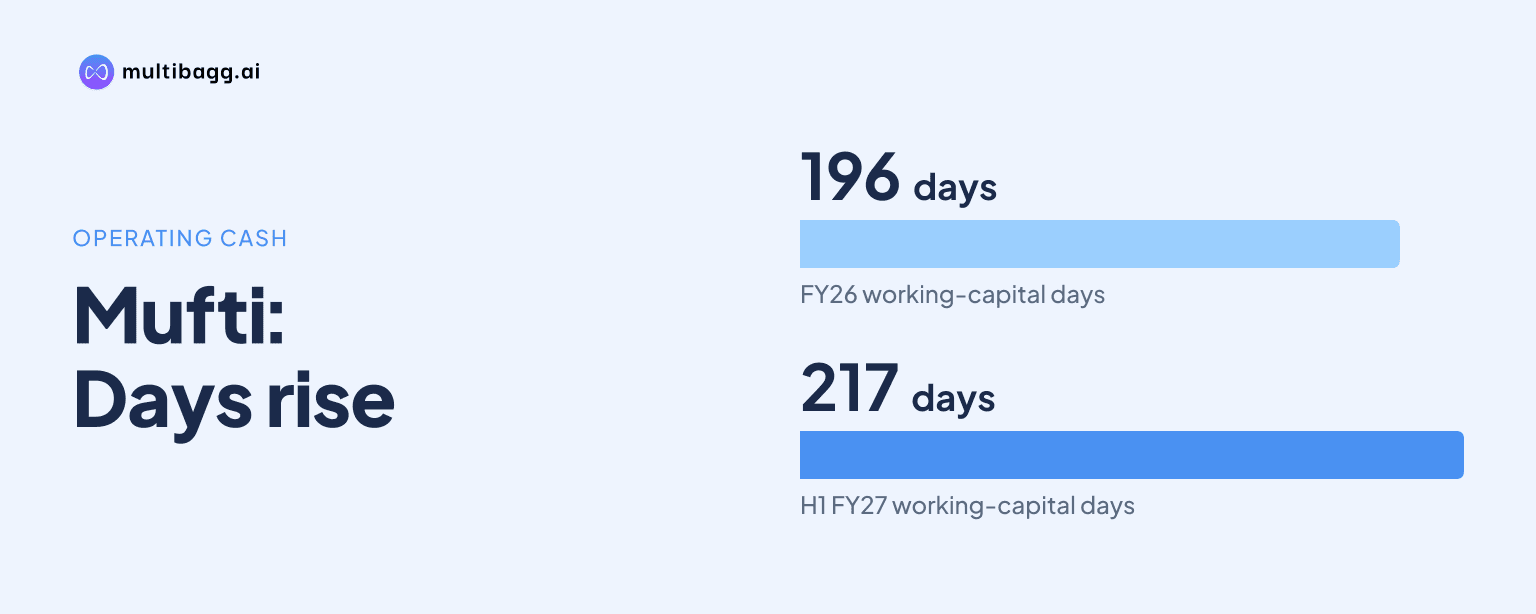
Credo Brands Marketing Limited reported for Mufti a 217-day working-capital cycle in H1 FY27 and Rs 4.2 crore in net cash from operating activities, down from Rs 32.4 crore a year earlier, even as profit after tax rose 18% to Rs 29.6 crore.
Know Credo Brands Marketing inside out
Results, valuation, peers and who's buying, in one view.
Why did Mufti’s working-capital days rise to 217?
Mufti’s working-capital days rose to 217 in H1 FY27 because debtor days increased to 162, inventory days reached 69 and creditor days declined to 14. Total working-capital days were 196 in FY26 and 184 in FY25, so the H1 FY27 measure was 21 days above FY26 and 33 days above FY25.
Debtor days were the largest element of the cycle at 162 in H1 FY27, compared with 147 in FY26 and 133 in FY25. Inventory days increased from 65 in FY26 to 69, while creditor days, which reduce the net funding requirement, fell from 16 in both FY25 and FY26 to 14. The reported movements show that receivables accounted for most of the change from FY26.
How did Mufti’s H1 FY27 operating cash flow compare with last year?
Mufti generated Rs 4.2 crore of net cash from operating activities in H1 FY27, compared with Rs 32.4 crore in H1 FY26, as working-capital changes absorbed Rs 71.9 crore. That outflow was more than double the Rs 33.7 crore working-capital absorption reported in the comparable prior-year half.
Operating profit before working-capital changes rose to Rs 87.7 crore in H1 FY27 from Rs 79.2 crore in H1 FY26, while cash generated from operations before direct taxes fell to Rs 15.8 crore from Rs 45.5 crore. Direct taxes paid were Rs 11.6 crore, below Rs 13.1 crore a year earlier, but the lower tax payment did not offset the larger cash use in working capital.
The company’s post-Indian Accounting Standard 116 cash-flow summary reports Rs 4 crore of cash flow from operations for H1 FY27, alongside Rs 132 crore for FY26 and Rs 159 crore for FY25. The H1 FY27 cash-flow statement provides the more detailed Rs 4.2 crore figure after direct taxes, while the annual figures are presented for full financial years and are not directly comparable with a six-month period.
What changed in Mufti’s balance sheet by September 2026?
Mufti’s inventory and trade receivables both increased between March 2026 and September 2026, consistent with the H1 FY27 working-capital outflow. Inventories rose by Rs 20.3 crore to Rs 130.7 crore, while trade receivables increased by Rs 48.9 crore to Rs 285.2 crore.
Together, inventories and trade receivables rose by Rs 69.2 crore in the six months to September 2026, from Rs 346.7 crore to Rs 415.9 crore. Current assets increased to Rs 466 crore from Rs 446 crore, but cash and cash equivalents on the balance sheet declined to Rs 12.8 crore from Rs 52.4 crore over the same period.
Mufti reported nil borrowings at both September 2026 and March 2026. Lease liabilities were Rs 172.7 crore under non-current liabilities and Rs 45.3 crore under current liabilities at September 2026, while total equity increased to Rs 455.4 crore from Rs 438.6 crore.
Got a follow-up? Ask IRIS
How did Mufti’s earnings grow while operating cash declined?
Mufti’s reported H1 FY27 earnings increased before the working-capital cash movement, with revenue from operations rising 11% year-on-year to Rs 314.6 crore and profit after tax increasing 18% to Rs 29.6 crore. Gross profit increased 12% to Rs 188.2 crore, and gross margin expanded by 80 basis points to 59.8%.
Earnings before interest, tax, depreciation and amortisation, or EBITDA, rose 9% to Rs 86.1 crore, but EBITDA margin decreased by 50 basis points to 27.4% from 27.9% in H1 FY26. Operating profit before working-capital changes nevertheless increased by Rs 8.5 crore year-on-year, whereas the working-capital cash outflow increased by Rs 38.2 crore.
Mufti’s H1 FY27 sales mix was led by exclusive brand outlets, or EBOs, at 52.7%, followed by multi-brand outlets, or MBOs, at 28.7%. Online contributed 11.8%, large-format stores accounted for 4.0%, and other channels made up 2.8%; in Q2 FY27, EBOs represented 47.1% while MBOs represented 36.0%, showing a different quarterly channel mix.
What return measures did Mufti report at September 2026?
Mufti reported trailing-12-month return on capital employed, or RoCE, of 14.6% and return on equity, or RoE, of 11.9% as of September 30, 2026. These measures were presented alongside a balance sheet with nil borrowings and total equity of Rs 455.4 crore at September 2026.
Mufti defines RoCE as earnings before interest and tax divided by average capital employed, where capital employed comprises total equity, long-term debt and short-term debt. It defines RoE as profit after tax divided by average equity; H1 FY27 profit after tax was Rs 29.6 crore, compared with Rs 25.1 crore in H1 FY26.
Conclusion
Mufti’s H1 FY27 results show higher reported earnings alongside a marked reduction in operating cash conversion. Revenue reached Rs 314.6 crore and profit after tax rose to Rs 29.6 crore, but the increase in trade receivables and inventories contributed to a Rs 71.9 crore working-capital outflow, taking the cycle to 217 days and net operating cash to Rs 4.2 crore.
The next disclosures will show whether the working-capital cycle changes as Mufti executes its store-network plan. Management said it had 57 stores under the New Mufti 2.0 identity after opening or renovating 14 during the quarter, and said it would prioritise store productivity over pure store count; subsequent results can indicate whether receivable and inventory growth moderates alongside that plan.