










Muthoot Microfin MSEL book reaches Rs 4,161.9 crore in five quarters
Key highlights
- MML’s MSEL portfolio reached Rs 4,161.9 crore in Q2 FY’27, compared with Rs 250.4 crore in Q2 FY’26.
- MSEL disbursements were Rs 1,297.6 crore in Q2 FY’27, compared with Rs 1,051.0 crore in Q1 FY’27.
- MSEL reported 99.7% collection efficiency and 0.02% delinquency at 90-plus days in Q2 FY’27.
- MML’s non-JLG AUM share rose to 31% in Q2 FY’27 from 2% in Q2 FY’26.
powered by IRIS
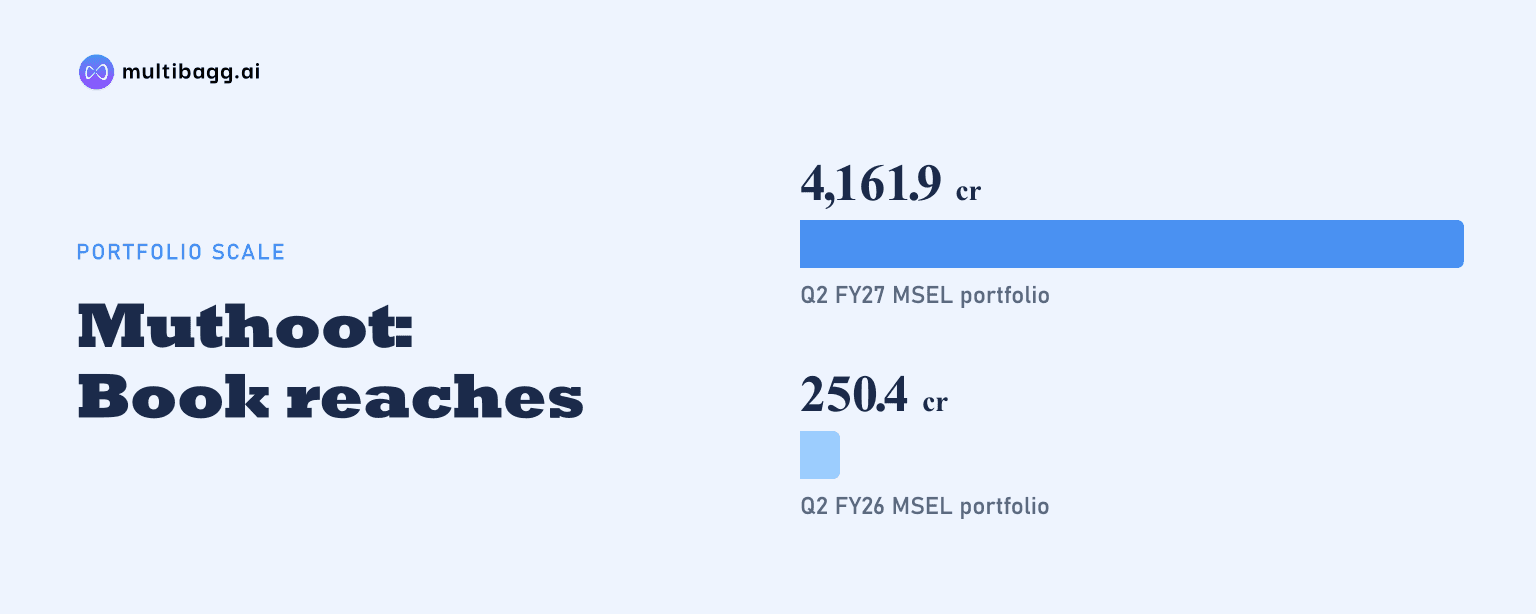
Muthoot Microfin’s Muthoot Small Enterprise Loan portfolio reached Rs 4,161.9 crore in Q2 FY’27, up from Rs 250.4 crore in Q2 FY’26 across five reported quarters. The portfolio, referred to as MSEL, recorded Rs 1,297.6 crore of Q2 FY’27 disbursements, 99.7% collection efficiency and 0.02% delinquency at 90-plus days overdue.
Know Muthoot Microfin inside out
Results, valuation, peers and who's buying, in one view.
How fast has MML’s MSEL portfolio grown?
MML’s MSEL portfolio rose by Rs 3,911.5 crore between Q2 FY’26 and Q2 FY’27, reaching Rs 4,161.9 crore from Rs 250.4 crore. The presentation says the series considers the MSEL new-book portfolio from July 2025, making it a measure of the product’s early build-out rather than a mature portfolio.
MSEL disbursements reached their highest reported level of Rs 1,409.7 crore in Q4 FY’26, declined to Rs 1,051.0 crore in Q1 FY’27, and recovered to Rs 1,297.6 crore in Q2 FY’27. Even with that movement in disbursements, the outstanding portfolio increased by Rs 950.9 crore quarter on quarter in Q2 FY’27.
The average ticket size, or ATS, was Rs 18.6 lakh in Q2 FY’27, compared with Rs 17.5 lakh in Q1 FY’27 and Rs 18.1 lakh in Q2 FY’26. The rise in Q2 FY’27 disbursement from the preceding quarter therefore coincided with a higher reported average ticket size.
How does MSEL change MML’s portfolio mix?
MSEL is included in MML’s non-JLG portfolio, whose share of assets under management, or AUM, rose to 31% in Q2 FY’27 from 2% in Q2 FY’26. Over the same period, the JLG share fell to 69% from 98%, which the presentation identifies as part of MML’s diversification strategy.
MML’s total AUM was Rs 15,322.8 crore in Q2 FY’27, up 22.0% year on year and 6.0% quarter on quarter. MSEL’s Rs 4,161.9 crore portfolio was part of the non-JLG category, which also includes MSME LAP loans and gold loans.
MML’s secured AUM increased to Rs 652.6 crore in Q2 FY’27 from Rs 6.9 crore in Q2 FY’26, while unsecured AUM rose to Rs 14,670.2 crore from Rs 12,551.9 crore. MSEL is shown separately from the secured and unsecured AUM chart, so the presentation does not provide a direct reconciliation between the MSEL balance and the secured-AUM classification.
MML clients’ industry exposure to microfinance loans declined to 36.3% in September 2026 from 54.2% in March 2024. Over that period, unsecured business-loan exposure increased to 38.3% from 28.0%, while gold-loan exposure rose to 17.5% from 11.4%.
What do MSEL collection and delinquency figures show?
MSEL reported collection efficiency, or CE, of 99.7% in Q2 FY’27, with delinquency of 0.15% at 0-plus days overdue and 0.02% at 90-plus days overdue. These figures relate to a portfolio that had reached Rs 4,161.9 crore by the end of the quarter.
MSEL delinquency declined across the reported ageing buckets, from 0.10% at 30-plus days to 0.05% at 60-plus days and 0.02% at 90-plus days. MML also reported 100% e-NACH and Unified Payments Interface, or UPI, mandate enrolment for MSEL in Q2 FY’27.
MSEL’s 99.7% CE was above MML’s overall CE of 98.11% in Q2 FY’27. MML’s overall CE was 97.97% in Q1 FY’27 and 93.34% in Q2 FY’26, while its reported October 2026 overall CE was 98.18%; these are company-wide comparators rather than MSEL delinquency measures.
MML reported a 24.5% effective yield and 8.1% product return on assets, or ROA, for MSEL in Q2 FY’27. The presentation says product ROA uses actual revenue, direct variable costs including credit cost, and generic operating expenses apportioned using relevant cost drivers.
Got a follow-up? Ask IRIS
Where is MML’s MSEL portfolio concentrated?
Tamil Nadu held the largest MSEL portfolio at Rs 1,466.1 crore, or 35% of the Q2 FY’27 total, followed by North at Rs 848.0 crore, or 20%. Kerala accounted for Rs 605.8 crore, or 15%, meaning Tamil Nadu and Kerala together represented half of MSEL.
Rest of South, comprising Karnataka, Telangana and Andhra Pradesh, represented Rs 335.9 crore and 8% of MSEL, with Karnataka accounting for 7.6% of the portfolio. Tamil Nadu, Kerala and Rest of South together made up 58% of MSEL, compared with 42% across North, East and West.
MML reported that South represented 48% of overall AUM in Q2 FY’27 and 58% of its individual-loan portfolio. The matching 58% share for MSEL across the three southern categories shows the product’s regional weight, although the presentation does not state that MSEL and individual loans are identical categories.
What operating context supports MML’s diversification?
MML operated 1,675 branches across 394 districts in Q2 FY’27, compared with 1,718 branches in Q2 FY’26. As total AUM rose to Rs 15,322.8 crore from Rs 12,558.8 crore, AUM per branch increased to Rs 9.15 crore from Rs 7.31 crore.
The relationship-officer count declined to 8,492 in Q2 FY’27 from 9,501 in Q2 FY’26, while AUM per relationship officer increased to Rs 1.80 crore from Rs 1.32 crore. MML notes that Q2 FY’27 productivity ratios include 87 contractual staff on payroll.
Rural AUM penetration was 96.6% in Q2 FY’27. MML also reported that its top 10 districts accounted for 19% of gross loan portfolio, while 336 districts, or 85.3% of total districts, were in the other-district exposure grouping.
Conclusion
MML’s diversification is visible in both the scale of MSEL and the broader AUM mix. MSEL reached Rs 4,161.9 crore within five reported quarters while non-JLG’s AUM share rose from 2% to 31%; the product’s reported Q2 FY’27 CE was 99.7%, and its 90-plus delinquency was 0.02%.
The next reported quarters will show whether MML’s diversification strategy further changes the 69% JLG and 31% non-JLG AUM mix. Key disclosed measures to track are MSEL disbursement relative to the Rs 1,409.7 crore peak in Q4 FY’26, as well as the product’s CE, delinquency and 58% southern portfolio concentration.