










NCC Limited Q2 revenue rises 32% to ₹6,042 crore YoY
Key highlights
- NCC reported Q2 FY27 consolidated revenue of ₹6,042 crore, up 32% from ₹4,585 crore a year earlier.
- H1 FY27 consolidated revenue rose 21% to ₹11,884 crore from ₹9,793 crore.
- Q2 FY27 consolidated EBITDA was reported at ₹528 crore with an 8.79% margin.
- NCC retained FY27 revenue-growth guidance of 8% to 10% and reported an order book of ₹80,167 crore.
powered by IRIS
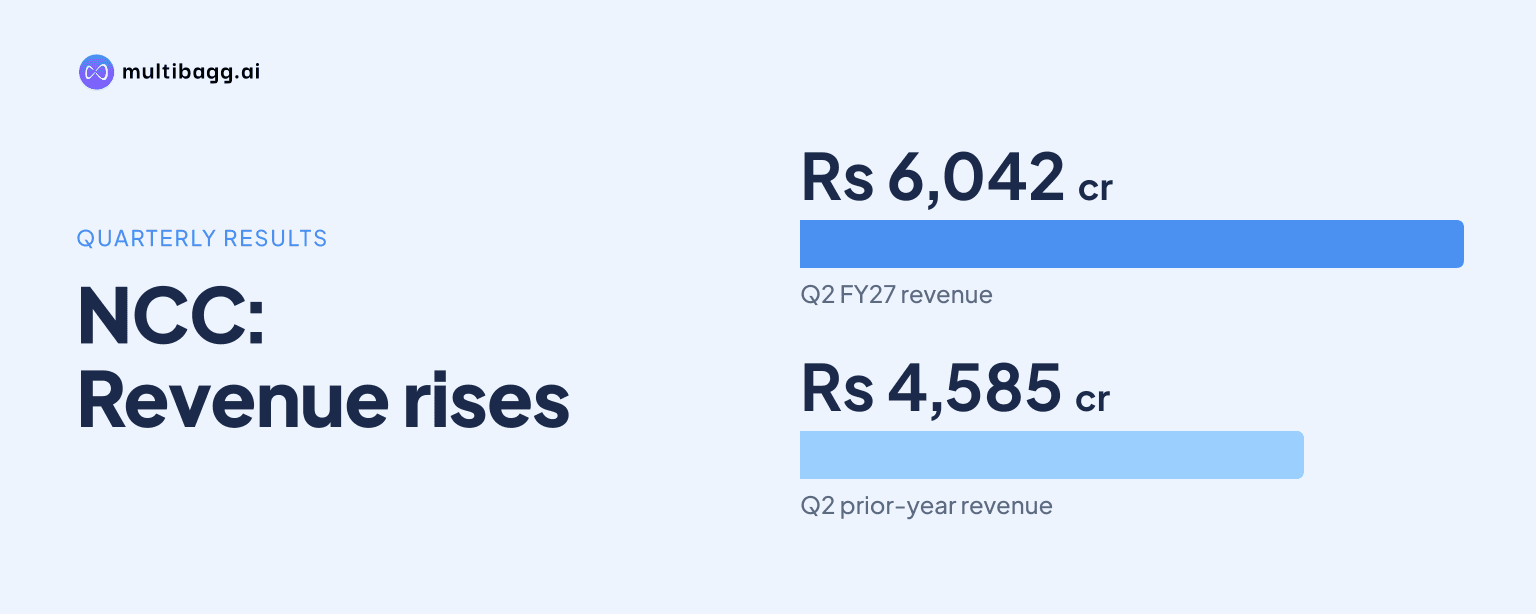
NCC Limited reported its highest-ever second-quarter consolidated revenue of ₹6,042 crore in Q2 FY27, up 32% year on year from ₹4,585 crore. The construction company also reported 21% consolidated revenue growth in the first half, while retaining its full-year revenue growth guidance of 8% to 10%.
Know NCC inside out
Results, valuation, peers and who's buying, in one view.
What did NCC report for Q2 FY27?
NCC Limited reported consolidated turnover of ₹6,042 crore for the quarter ended September 30, 2026, compared with ₹4,585 crore in the corresponding quarter of FY26. The 32% year-on-year increase made this the company’s highest Q2 consolidated revenue disclosed in the source material.
On a standalone basis, NCC reported Q2 turnover of ₹4,957 crore, up 31% from ₹3,775 crore a year earlier. The distinction between standalone and consolidated reporting is important because the company’s consolidated figures include the performance of its subsidiaries, while the standalone numbers cover the parent entity.
How did NCC's profitability and first-half revenue perform?
NCC reported ₹11,884 crore in consolidated turnover for H1 FY27, an increase of 21% from ₹9,793 crore in H1 FY26. Management attributed the half-year performance to mining projects and improved site conditions, according to the earnings-call material.
The investor-presentation highlights in the supplied material reported quarterly EBITDA of ₹528 crore, with an 8.79% margin, compared with ₹393 crore and an 8.66% margin in the prior-year quarter. Separately, the chief financial officer said standalone EBITDA was ₹417.05 crore at an 8.48% margin, versus ₹277.45 crore and 7.45% a year earlier. These are different reporting bases and should not be directly compared without that context.
Got a follow-up? Ask IRIS
What is NCC's FY27 revenue outlook?
NCC retained its FY27 revenue growth guidance of 8% to 10%, despite reporting 21% consolidated growth in the first half. The guidance indicates that the company expects a slower pace of revenue growth in the second half relative to its H1 performance, although management did not quantify the expected H2 trend in the material provided.
The company also maintained a disciplined capital-expenditure outlook of ₹500 crore for FY27. Its order book stood at ₹80,167 crore, giving NCC a substantial stated project pipeline. Order-book data shows work awarded but does not, by itself, determine the timing of execution, revenue recognition or profitability.
How do the results affect investors and construction operations?
The Q2 revenue growth reflects stronger execution across NCC’s operations, including mining projects, along with improved site conditions cited by management. For investors, the reported improvement in EBITDA margin to 8.79% at the consolidated level provides a measure of operating performance alongside the 32% increase in revenue.
The supplied material also cited consolidated profit after tax of ₹184 crore, up 19% year on year. Another result summary included in the source reported net profit of ₹198.8 crore and revenue from operations of ₹6,015 crore. As these figures differ from the consolidated earnings-call and presentation data, readers should use the company’s filed financial results to confirm the applicable reporting basis and final figures.
NCC said it expects substantial completion of major Jalji Unmishan backlogs by March 2027. The stated timetable provides context for project execution, but the company did not provide a detailed financial contribution or margin outlook for those projects in the supplied transcript excerpts.
Conclusion
NCC’s Q2 FY27 results show a 32% rise in consolidated revenue to ₹6,042 crore and 21% growth in H1 revenue to ₹11,884 crore. The reported EBITDA margin improvement and ₹80,167 crore order book support the company’s disclosed execution momentum, while standalone and consolidated measures should be assessed separately.
The main point to watch is how NCC reconciles its 8% to 10% FY27 revenue-growth guidance with the faster growth reported in the first half. Investors can also track progress on the ₹500 crore capital-expenditure plan and the company’s stated target to substantially complete major Jalji Unmishan backlogs by March 2027.