










Protean says RFP spend held Q2 margin below its 18% run rate
Key highlights
- Protean reported Q2FY27 revenue of Rs 271 crore, up 8% year on year and sequentially.
- Protean reported Q2FY27 EBITDA of Rs 43 crore and a 15% margin, including Rs 10 crore of upfront RFP spending.
- Excluding RFP spending, Protean said Q2FY27 EBITDA was Rs 53 crore and EBITDA margin was 18%.
- Protean had about Rs 750 crore of cash and marketable securities and zero debt on 30 September 2026.
powered by IRIS
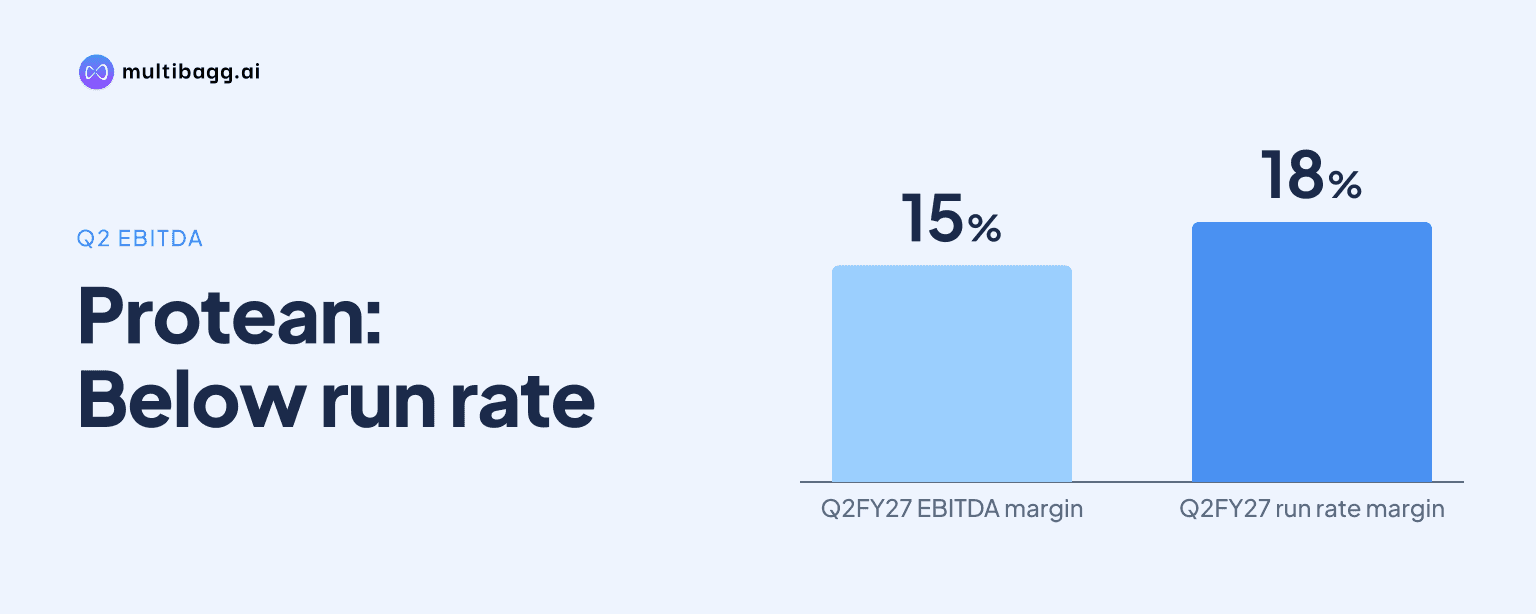
In Q2FY27, Protean reported a 15% EBITDA margin, while management said Rs 10 crore of upfront request-for-proposal, or RFP, project spending reduced the reported figure below its 18% underlying run rate; it said most projects are going live and major investment is largely behind it.
Know Protean eGov Technologies inside out
Results, valuation, peers and who's buying, in one view.
Why did Protean's reported margin decline in Q2FY27?
Protean's reported margin declined because it incurred employee and other costs for RFP projects before the related full-year revenue accrued. Consolidated earnings before interest, tax, depreciation and amortisation, or EBITDA, were Rs 43 crore in Q2FY27, compared with Rs 44 crore in Q2FY26, while EBITDA margin was 15%. Revenue from operations nevertheless rose 8% year on year and sequentially to Rs 271 crore.
The effect was more visible in the first half. H1FY27 EBITDA was Rs 71 crore, versus Rs 89 crore in H1FY26, and margin was 12.8%. Management attributed Rs 28 crore of H1FY27 costs to upfront RFP spending and cost inflation, recorded mainly in employee costs and other expenses before revenue recognition from the projects.
How much did RFP spending affect Protean's underlying profitability?
Protean said that, excluding Rs 10 crore of Q2FY27 upfront RFP investment, EBITDA would have been Rs 53 crore and EBITDA margin would have been 18%. Management said this adjusted EBITDA was 22% higher year on year and the adjusted margin was 187 basis points above the comparable prior-year level.
Profit after tax, or PAT, was Rs 16 crore in Q2FY27, down from Rs 24 crore a year earlier, with a reported PAT margin of 6%. Protean presented normalized PAT, excluding the upfront RFP investment, at Rs 24 crore for Q2FY27 and Rs 44 crore for H1FY27, with an 8% margin in both periods. These normalized figures are management's adjustments rather than reported earnings.
When does Protean expect reported margins to recover?
Protean expects reported margins to move closer to its stated 18% underlying run rate in coming quarters because most RFP projects are going live and the major investment is largely behind it. Management said expenditure preceded full-year revenue accrual from the projects, creating the timing difference that affected Q2FY27 and H1FY27 reported margins.
The company gave neither a full-year margin target nor a specific quarter when reported margin may reach 18%. It said it entered H2FY27 with better revenue and margin visibility, while cautioning that project-led revenue can land in a single quarter. New initiatives contributed Rs 42 crore, or about 16%, of Q2FY27 revenue, and their H1FY27 revenue grew 56% year on year.
Got a follow-up? Ask IRIS
Which businesses could improve Protean's future revenue mix?
Protean is pursuing bundled enterprise solutions and international digital public infrastructure offerings to change its revenue mix, while retaining its core public-infrastructure activities. Management said its enterprise proposition combines identity, verification, consent, data analytics, credit analysis, documentation and compliance in a single customer journey, enabling pricing per journey or outcome rather than only per application programming interface, or API, call.
The early commercial indicators were more than 20 signed mandates and more than 30 mandates in the immediate pipeline for adjacent banking, financial services and insurance, or BFSI, offerings. Management identified eSignPro digital documentation, stamping and signing, plus CKYC-led onboarding journeys, as the two principal areas. It did not disclose contract values, customer names, revenue timing or margins for these mandates.
Identity Services was Protean's fastest-growing reported segment in Q2FY27, with revenue up 24% year on year and volume up 26% across four digital-identity vectors. Tax Services contributed Rs 121 crore, growing 13% year on year and 22% sequentially, while CRA Services contributed Rs 80 crore, up 2% year on year. Management said CRA revenue includes charges linked to assets under management, or AUM, alongside subscriber-based revenue.
What balance-sheet and execution factors should investors track?
Protean had zero debt and about Rs 750 crore of cash and marketable securities as of 30 September 2026. Property, plant and equipment rose to Rs 150 crore in September 2026 from Rs 63 crore in March 2026, reflecting investment in the ASK project, according to management.
Working-capital execution also remains relevant because days sales outstanding, or DSO, increased to 93 days in September 2026 from 64 days in March 2026, primarily due to project receivables. The transcript does not give a receivables-collection timetable. Management also said it had deployed automation and advanced validation tools in core operations to reduce dependence on external partners and redeploy resources to new projects.
Conclusion
Protean's Q2FY27 result indicates that reported profitability was lower than management's adjusted operating measure because Rs 10 crore of RFP costs were recognised before associated project revenue accrued. Revenue increased 8% year on year to Rs 271 crore, while management's 18% adjusted EBITDA margin is its stated reference point for a recovery in reported margin as projects go live.
The next points to watch are the pace of full-year revenue accrual from RFP projects, conversion of more than 30 enterprise mandates in the immediate pipeline, and H2FY27 tax volumes. Management said FY28 tax-revenue visibility should improve after PAN 2.0 is implemented sometime next year, and it expects to share tangible international-business progress in coming quarters.