










Qualiance H1 Revenue Falls 19.5% Amid US Tariff Uncertainty
Key highlights
- Qualiance’s H1FY27 revenue from operations fell 19.5% year on year to Rs 30.97 crore from Rs 38 crore.
- H1FY27 EBITDA declined 29.9% to Rs 5.26 crore, while the EBITDA margin narrowed to 17.0% from 19.5%.
- Cash and bank balances rose to Rs 37.9 crore in September 2026 from Rs 0.8 crore in March 2026, while short-term borrowings fell to Rs 12.8 crore from Rs 23.6 crore.
- Qualiance generated 98.82% of its revenue from exports and is building a new facility planned at approximately 3.4 times its existing manufacturing capacity.
powered by IRIS
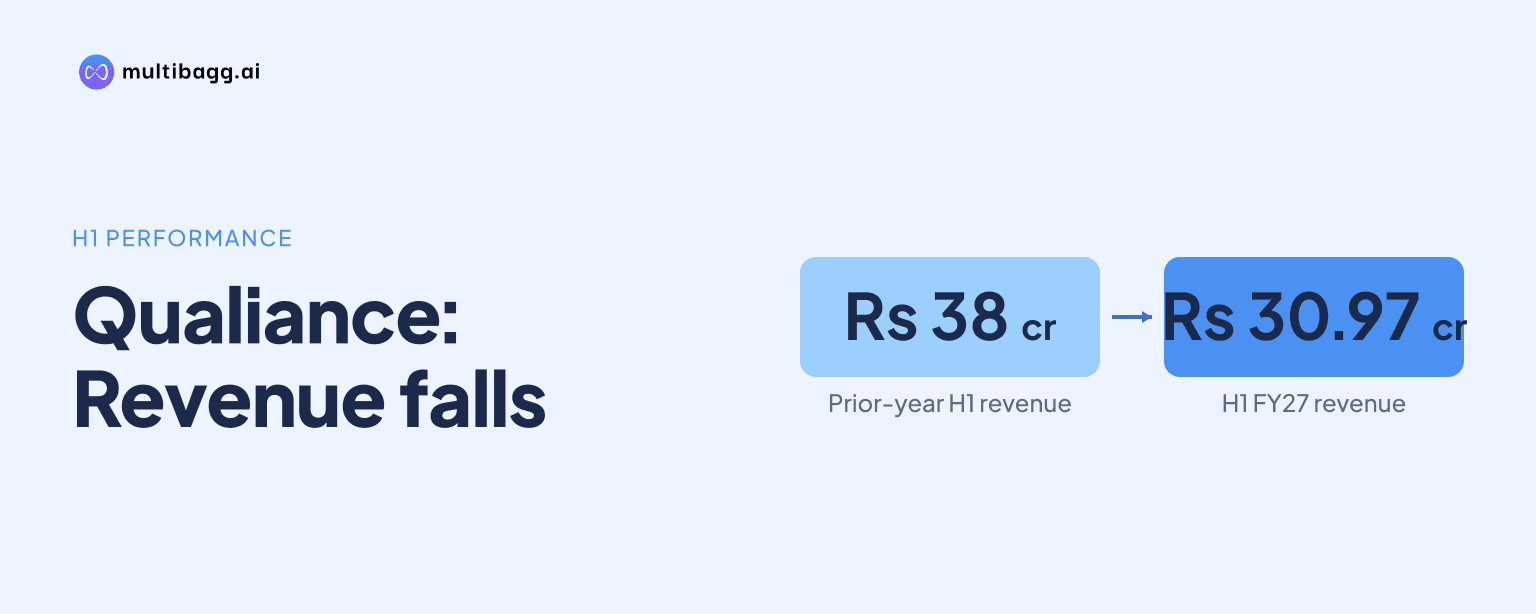
Qualiance International Limited reported revenue from operations of Rs 30.97 crore in the first half of financial year 2027 (H1FY27), down 19.5% from Rs 38 crore in H1FY26, after United States tariff-policy uncertainty affected customer ordering and inspection delayed dispatches. Qualiance expects pending orders to be executed in H2FY27 and management retained its FY27 revenue outlook in line with the preceding financial year.
Know Qualiance International inside out
Results, valuation, peers and who's buying, in one view.
Why did Qualiance’s H1FY27 revenue decline?
Qualiance’s H1FY27 revenue declined because softer United States demand amid tariff-related uncertainty affected customer ordering, while dispatches of some orders awaited inspection. Revenue from operations was Rs 30.97 crore in H1FY27, compared with Rs 38 crore in H1FY26, resulting in the reported 19.5% year-on-year decline.
Chairman and Managing Director Vipul Badani identified United States tariff-policy uncertainty and delays in dispatches of orders awaiting inspection as the primary near-term challenges during the first half. Management said the orders awaiting inspection are expected to be executed in H2FY27, although the presentation does not disclose their value or an inspection timetable.
Qualiance operates a technical-apparel manufacturing facility in Tiruppur, Tamil Nadu, with installed capacity of 4.5 lakh garments a year. The company manufactures military, tactical, protective workwear and activewear, using seam sealing, bonding, ultrasonic welding and lamination, and reported an export share of 98.82%.
How did Qualiance’s H1FY27 profitability change?
Qualiance’s profitability declined faster than revenue in H1FY27 because lower capacity utilisation reduced earnings and margins. Earnings before interest, tax, depreciation and amortisation (EBITDA) fell 29.9% to Rs 5.26 crore from Rs 7.51 crore, while the EBITDA margin declined to 17.0% from 19.5%.
Gross profit was Rs 16 crore in H1FY27, compared with Rs 21 crore in H1FY26, and gross margin decreased to 51.0% from 54.9%. Cost of goods sold increased to Rs 13 crore from Rs 12 crore, while the change in inventories was Rs 2 crore, compared with Rs 6 crore a year earlier.
Employee benefits expense fell to Rs 6 crore from Rs 9 crore, while other expenses declined to Rs 4 crore from Rs 5 crore. Those reductions did not offset the Rs 5 crore fall in gross profit, leaving EBITDA at Rs 5 crore in the rounded profit-and-loss statement and Rs 5.26 crore in the accompanying commentary.
Profit after tax (PAT) was Rs 3.74 crore in H1FY27, compared with Rs 5.25 crore in H1FY26, and the PAT margin narrowed to 12.1% from 13.6%. Qualiance said the prior-year PAT included a one-time, non-cash deferred-tax credit of Rs 1.52 crore and described PAT as broadly stable year on year after excluding that item.
Got a follow-up? Ask IRIS
What do Qualiance’s balance sheet and cash figures show?
Qualiance’s cash and bank balances increased to Rs 37.9 crore in September 2026 from Rs 0.8 crore in March 2026, while total assets rose to Rs 99.5 crore from Rs 69 crore. Shareholders’ funds were Rs 77.3 crore in September 2026, compared with Rs 34.7 crore six months earlier.
The presentation reported net cash flow from operating activities of Rs 8.9 crore in the September 2026 column, compared with Rs 8.2 crore in the March 2026 column. Net cash flow from financial activities was Rs 26.5 crore, versus an outflow of Rs 4.9 crore, contributing to a reported Rs 37.1 crore increase in cash and cash equivalents.
Working-capital balances were lower in September 2026 than in March 2026: inventories declined to Rs 21.1 crore from Rs 24.1 crore and trade receivables decreased to Rs 12.5 crore from Rs 16 crore. Short-term borrowings fell to Rs 12.8 crore from Rs 23.6 crore, while long-term borrowings declined to Rs 4 crore from Rs 4.9 crore.
The H1FY27 snapshot reported return on equity (ROE) of 16%, return on capital employed (ROCE) of 13%, and debt-to-equity of 0.25 times. It reported net worth of Rs 68 crore and specified that these calculations excluded revaluation reserves of Rs 9.59 crore.
What is Qualiance expecting in H2FY27?
Qualiance expects stronger H2FY27 performance because orders awaiting inspection are expected to be executed and domestic customers are expected to contribute more. This is management’s expectation rather than a reported second-half result, following H1FY27 revenue of Rs 30.97 crore.
Management said it remains committed to FY27 revenue in line with the previous financial year despite the 19.5% H1FY27 revenue decline. The presentation gives no numerical FY27 revenue target, no value for the pending orders and no schedule for completing their inspection or dispatch.
Qualiance is pursuing a broader customer base through deeper domestic relationships and expansion in Europe. Its customer base includes Swiss Government departments and international institutional and brand clients across Europe and North America, supported by the existing 4.5 lakh-garment annual capacity in Tiruppur.
Construction has commenced on a new manufacturing facility as part of the company’s initial public offering objectives, according to the chairman. Management said the facility is intended to provide approximately 3.4 times existing manufacturing capacity, allowing Qualiance to address larger requirements, engage new customers and pursue opportunities across markets.
Conclusion
Qualiance’s H1FY27 result reflects the effect of delayed United States-linked ordering and inspection-related dispatch delays on sales and profitability. Revenue declined 19.5% to Rs 30.97 crore, EBITDA fell to Rs 5.26 crore and PAT was Rs 3.74 crore, while inventories, receivables and borrowings were lower in September 2026 than in March 2026.
The next result will show whether pending orders are executed in H2FY27 as management expects and whether domestic customers provide the anticipated additional contribution. Progress on the new facility, planned at approximately 3.4 times current capacity, and delivery of FY27 revenue in line with the preceding financial year are the disclosed matters to watch next.