










Radico Khaitan’s premium mix lifts FY2026 case realisation
Key highlights
- Radico Khaitan’s total realisation rose to Rs 1,181 per case in FY2026 from Rs 864 in FY2021.
- Prestige & Above volume reached 16.7 million cases in FY2026, or 45.6% of reported volume.
- Q2 FY2027 EBITDA increased 51.0% year on year to Rs 356.5 crore, with margin at 20.4%.
- Q2 FY2027 net debt was Rs 175.4 crore, down Rs 68.7 crore from March 2026.
powered by IRIS
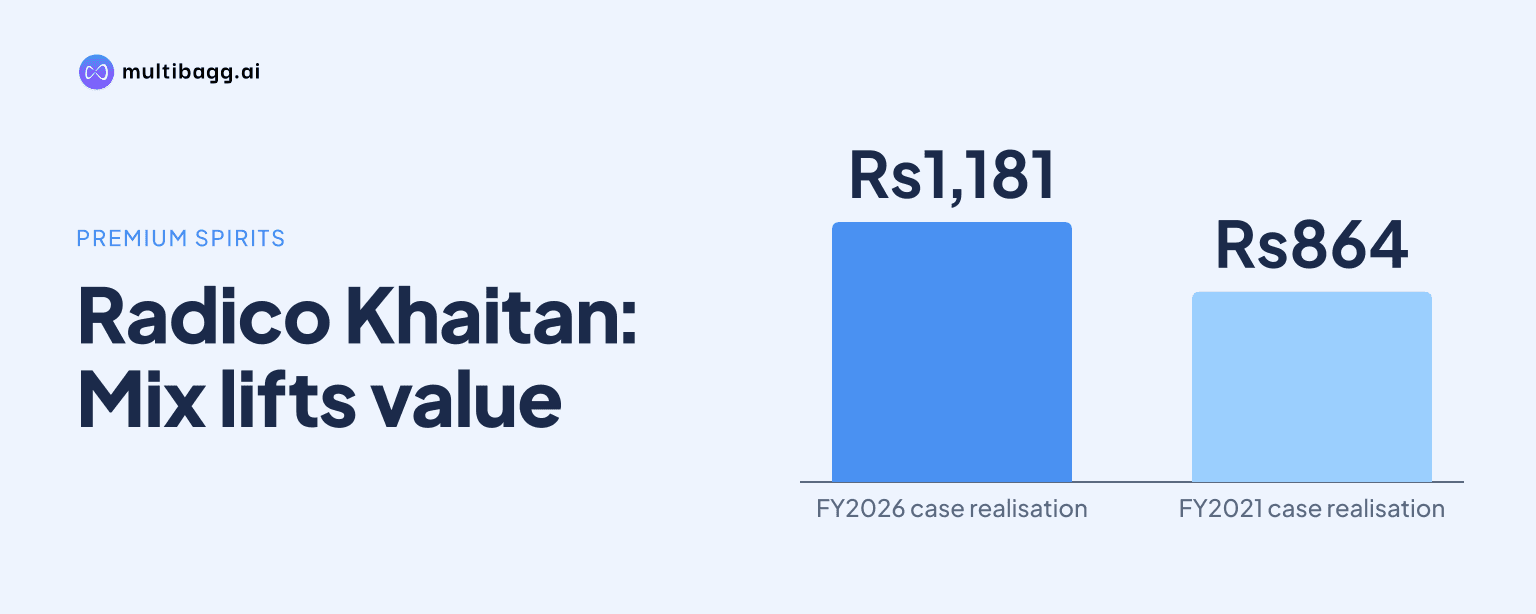
Radico Khaitan Limited (Radico Khaitan) lifted total realisation to Rs 1,181 per case in FY2026 from Rs 864 in FY2021, while Prestige & Above volume reached 16.7 million cases and accounted for 45.6% of reported volume. Prestige & Above realisation was Rs 1,834 per case, versus Rs 634 for Regular & Others.
Know Radico Khaitan inside out
Results, valuation, peers and who's buying, in one view.
How has Radico Khaitan’s premium mix changed?
Radico Khaitan’s Prestige & Above volume rose to 16.7 million cases in FY2026 from 7.1 million cases in FY2020, lifting the segment’s share of reported volume to 45.6% from 29.0%. The presentation says Prestige & Above brands have grown at a 13% compound annual growth rate since FY2019.
The volume shift was faster in Prestige & Above than in Regular & Others. Prestige & Above added 9.6 million cases between FY2020 and FY2026, while Regular & Others added 2.7 million cases, reaching 19.9 million cases from 17.2 million cases. Total volume increased by 14.0 million cases to 38.3 million cases over the same period.
The FY2026 mix was marginally below FY2025, when Prestige & Above represented 46.1% of total volume, but remained well above the 29.0% recorded in FY2020. For FY2023 to FY2026, Radico Khaitan excludes royalty brands from the Prestige & Above and Regular & Others measures while including royalty brands in total volume, meaning the segment volumes do not necessarily sum to the total.
The latest quarterly data show a further shift in own-volume mix. In Q2 FY2027, or the second quarter of financial year 2027, Prestige & Above volume grew 35.8% year on year to 5.28 million cases, while Regular & Others volume declined 9.7% to 4.55 million cases. Prestige & Above therefore represented 53.7% of total own volume, compared with 43.6% in Q2 FY2026.
What happened to Radico Khaitan’s realisation per case?
Radico Khaitan’s total realisation increased by Rs 317 per case, to Rs 1,181 in FY2026 from Rs 864 in FY2021. The gain coincided with both a larger Prestige & Above volume base and higher realisation within that segment.
Prestige & Above realisation rose by Rs 324 per case over the five-year comparison, from Rs 1,510 in FY2021 to Rs 1,834 in FY2026. Regular & Others realisation increased by Rs 31 to Rs 634 per case from Rs 603, leaving a Rs 1,200 per-case difference between the two segments in FY2026.
The annual path differed by segment. Prestige & Above realisation increased every year shown, from Rs 1,510 in FY2021 to Rs 1,801 in FY2025 and Rs 1,834 in FY2026. Regular & Others realisation reached Rs 649 in FY2025 before declining to Rs 634 in FY2026, while total realisation still edged up from Rs 1,180 to Rs 1,181.
The Q2 FY2027 revenue mix is consistent with the difference in annual segment realisation. Prestige & Above generated Rs 996.0 crore, or 77.1%, of Indian-made foreign liquor (IMFL) revenue of Rs 1,292.2 crore, although it made up 53.7% of own volume. Regular & Others generated Rs 292.7 crore, or 22.7% of IMFL revenue.
Got a follow-up? Ask IRIS
How did the premium mix coincide with profitability growth?
Radico Khaitan reported Q2 FY2027 gross profit of Rs 838.4 crore, up 28.6% year on year, against a 16.8% increase in net revenue from operations to Rs 1,745.1 crore. Gross margin consequently rose to 48.0% from 43.6%, an increase of 4.4 percentage points.
Earnings before interest, tax, depreciation and amortisation (EBITDA) rose 51.0% to Rs 356.5 crore in Q2 FY2027 from Rs 236.1 crore in Q2 FY2026. EBITDA margin rose to 20.4% from 15.8%, a 4.6-percentage-point movement. The presentation attributes higher profitability and return ratios to premiumisation coupled with raw-material tailwinds.
The half-year comparison showed a similar pattern. EBITDA for Half Year FY2027 was Rs 704.6 crore, up 50.9% from Rs 466.8 crore in Half Year FY2026, while EBITDA margin was 20.5% compared with 15.6%. Net revenue from operations increased 14.3% to Rs 3,429.8 crore over that period.
Quarterly profit measures also grew faster than net revenue. Q2 FY2027 profit before tax increased 65.1% to Rs 307.7 crore, while total comprehensive income increased 67.1% to Rs 230.3 crore. Total comprehensive income margin rose to 13.2% from 9.2%, and basic earnings per share increased to Rs 17.23 from Rs 10.38.
What do Radico Khaitan’s latest mix and debt figures show?
Radico Khaitan’s Q2 FY2027 IMFL revenue grew 23.4% year on year to Rs 1,292.2 crore, faster than the 1.4% increase in non-IMFL revenue to Rs 452.9 crore. IMFL consequently represented 74.0% of net revenue from operations, compared with 70.1% a year earlier.
Within IMFL, Prestige & Above revenue increased 38.6% to Rs 996.0 crore in Q2 FY2027, while Regular & Others revenue declined 9.3% to Rs 292.7 crore. Prestige & Above’s share of IMFL revenue rose to 77.1% from 68.6% in Q2 FY2026, exceeding its 53.7% share of own volume.
Radico Khaitan reported net debt of Rs 175.4 crore at Q2 FY2027, a reduction of Rs 68.7 crore compared with March 2026. The company also reported Q2 FY2027 total comprehensive income of Rs 230.3 crore and EBITDA of Rs 356.5 crore; the financial figures in the presentation are on a standalone basis.
The presentation does not provide a quantified bridge separating the effects of premiumisation and raw-material conditions on the Rs 120.4 crore year-on-year increase in Q2 FY2027 EBITDA. It identifies both mechanisms, while the reported data separately show a 35.8% rise in Prestige & Above volume and a 4.6-percentage-point increase in EBITDA margin.
Conclusion
Radico Khaitan’s multi-year figures show a portfolio with a larger share of Prestige & Above cases and higher total realisation. From FY2021 to FY2026, total realisation rose by Rs 317 per case, while the premium segment’s FY2026 realisation was Rs 1,200 per case above Regular & Others. Q2 FY2027 paired that mix shift with 20.4% EBITDA margin and Rs 175.4 crore of net debt.
The next results will show whether Prestige & Above can sustain the Q2 FY2027 level of 53.7% of own volume and 35.8% year-on-year volume growth while Regular & Others volume declined 9.7%. Radico Khaitan identifies raw-material tailwinds as part of the recent profitability outcome, but discloses no numerical target for future realisation, margins or return ratios.