










Rashi Peripherals Limited Q2 FY27 Profit Rises 121% on Revenue Growth
Key highlights
- Rashi Peripherals reported Q2 FY27 consolidated revenue of ₹6,185.11 crore, up 48.84% year-on-year.
- Q2 FY27 consolidated PAT rose 120.77% year-on-year to ₹130.74 crore.
- Consolidated EBITDA increased 112.37% to ₹220.12 crore in Q2 FY27.
- Working-capital days improved to 55 days from 61 days.
powered by IRIS
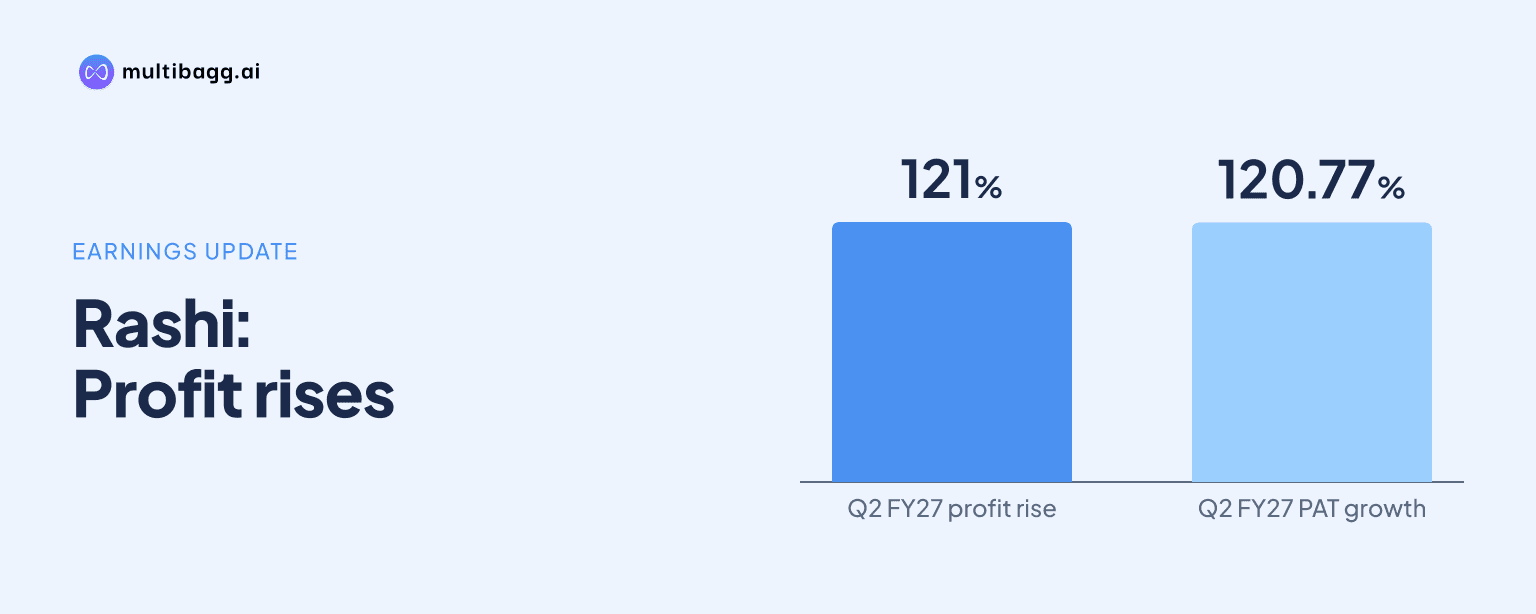
Rashi Peripherals Limited reported its highest-ever Q2 profit in FY27, with consolidated profit after tax rising 121% year-on-year to ₹130.74 crore as consolidated revenue increased 48.84% to ₹6,185.11 crore. The company also reported improved margins and working-capital efficiency, while management flagged softer consumer demand and a potential ₹900 crore qualified institutional placement.
Know Rashi Peripherals inside out
Results, valuation, peers and who's buying, in one view.
What did Rashi Peripherals report for Q2 FY27?
Rashi Peripherals reported strong growth across its standalone and consolidated operations for the quarter ended September 30, 2026. Consolidated revenue from operations rose 49% year-on-year to ₹6,185 crore, while EBITDA increased 112% to ₹220 crore. Consolidated PAT rose 121% to ₹131 crore, marking the company’s highest quarterly profit on a consolidated basis.
The filed quarterly figures place consolidated revenue at ₹6,185.11 crore, compared with ₹4,155.41 crore in Q2 FY26. Operating profit increased to ₹220.12 crore from ₹103.65 crore, while net profit rose to ₹130.74 crore from ₹59.22 crore. The earnings call was held on November 6, 2026, after the company declared its quarterly results on November 5.
On a standalone basis, revenue from operations grew 42% year-on-year to ₹5,708 crore. Standalone EBITDA rose 96% to ₹196 crore and standalone PAT increased 172% to ₹153 crore. Management said the performance reflected growth across its businesses and progress in building a broader technology solutions platform.
How did margins and working capital change during the quarter?
Rashi Peripherals expanded profitability margins in Q2 FY27 alongside revenue growth. Consolidated EBITDA margin increased by 106 basis points year-on-year to 3.56%, while consolidated PAT margin improved by 69 basis points to 2.11%.
Standalone EBITDA margin increased by 95 basis points to 3.44%. Standalone PAT margin improved by 128 basis points to 2.68%, compared with the prior-year quarter. The improvement in operating and net margins helped profit grow faster than revenue on both reported bases.
Working-capital days declined to 55 days from 61 days. For a technology distribution business, where inventory and receivables require regular funding, this reduction indicates better efficiency in the capital tied up in day-to-day operations. The company did not provide further break-up of inventory, receivable or payable movements in the supplied call extract.
What was Rashi Peripherals' first-half FY27 performance?
Rashi Peripherals reported continued growth in the first half ended September 30, 2026. Consolidated revenue from operations increased 55% year-on-year to ₹11,287 crore, while EBITDA rose 81% to ₹375 crore. Consolidated PAT increased 95% to ₹235 crore.
Consolidated EBITDA margin for H1 FY27 improved by 49 basis points to 3.33%. Consolidated PAT margin expanded by 43 basis points to 2.08%. These figures show that the margin improvement reported in the second quarter was also visible across the first six months of the financial year.
Standalone H1 revenue rose 49% year-on-year to ₹10,540 crore. Standalone EBITDA grew 71% to ₹345 crore and PAT rose 117% to ₹250 crore. The company described both its quarterly and half-yearly standalone and consolidated profit levels as record highs.
Got a follow-up? Ask IRIS
Why did management give a cautious outlook for the second half?
Rashi Peripherals flagged softer consumer demand as a factor relevant to the second-half FY27 outlook. The supplied earnings-call summary does not quantify the expected demand effect or provide a formal revenue or earnings forecast, but the comment introduces caution after a period of rapid first-half growth.
The company also referred to a potential ₹900 crore qualified institutional placement, or QIP. A QIP can raise capital from eligible institutional buyers, but new share issuance can dilute existing shareholders. The supplied material identifies the possible amount and dilution concern but does not disclose pricing, timing, use of proceeds, or final approval status.
For investors, the second-half discussion therefore involves two separate considerations. One is whether demand conditions affect the pace of sales growth. The other is whether, and on what terms, the company proceeds with the proposed equity fundraising. Neither matter changes the reported Q2 FY27 financial results.
How do the results affect investors and the technology distribution sector?
Rashi Peripherals' results show that its operating profit and net profit grew more quickly than revenue in Q2 FY27. Consolidated revenue rose 48.84%, while operating profit rose 112.37% and net profit increased 120.77%. The concurrent improvement in margins and reduction in working-capital days are key financial indicators for shareholders assessing the quality of reported growth.
The results also underline the importance of execution in India's technology hardware distribution market. Revenue growth alone may not translate into stronger returns if margins remain narrow or if more cash is locked in operations. In this quarter, Rashi Peripherals reported both higher revenue and better profitability metrics, though management's comments on consumer demand indicate that market conditions remain relevant for future business activity.
Any QIP, if completed, would add a capital-allocation dimension to the investment case. Investors would need to assess the final issue terms, the number of shares issued and the stated deployment of funds against the company's operating needs and balance-sheet priorities. Those details were not available in the supplied earnings-call material.
Conclusion
Rashi Peripherals delivered record Q2 and H1 FY27 profits, supported by strong revenue growth, expanded EBITDA and PAT margins, and a six-day improvement in working-capital days. Consolidated Q2 revenue reached ₹6,185.11 crore and consolidated PAT reached ₹130.74 crore, representing year-on-year growth of 48.84% and 120.77%, respectively.
The next points to watch are management's assessment of consumer demand during the second half of FY27 and any formal update on the potential ₹900 crore QIP. The company has not disclosed the proposed fundraising timeline, pricing or intended use of proceeds in the supplied material.