










Regency Fincorp Caps Digital Lending at 30%, JetFund at Rs 50 crore
Key highlights
- Regency Fincorp has board approval to cap digital lending at 30% of AUM, leaving at least 70% for secured lending.
- JetFund is live and targeted to reach Rs 50 crore to Rs 55 crore of AUM by the end of March.
- Regency Fincorp's digital lending book includes Rs 125 crore added through fresh borrower acquisition, while total AUM has reached Rs 610 crore.
- The company is raising about Rs 313 crore through preferential equity and warrants, including Rs 100 crore to Rs 125 crore earmarked for a digital lending acquisition.
powered by IRIS
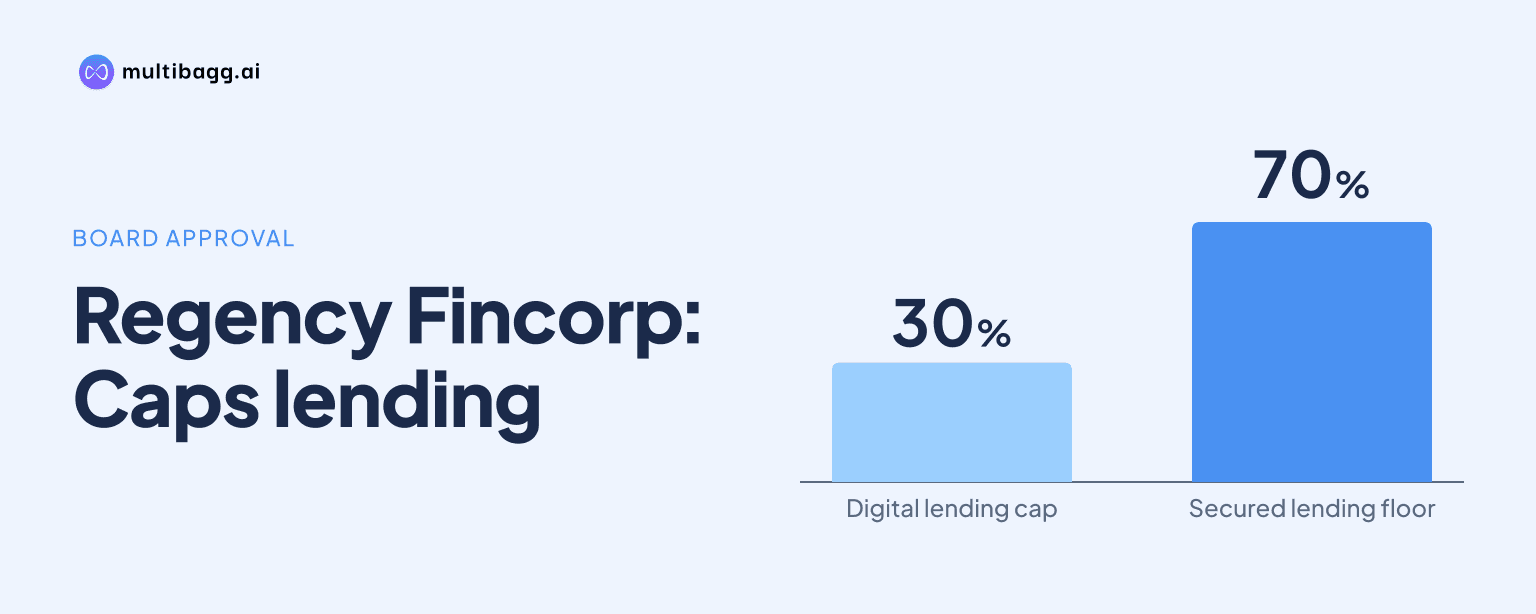
Regency Fincorp Limited has set a board-approved ceiling of 30% of assets under management, or AUM, for digital lending, while retaining 70% in secured lending. Management said JetFund is live and is targeted to reach Rs 50 crore to Rs 55 crore of AUM by the end of March, alongside a Rs 125 crore existing digital book.
Know Regency Fincorp inside out
Results, valuation, peers and who's buying, in one view.
What is Regency Fincorp's digital lending limit?
Regency Fincorp will limit digital lending to no more than 30% of its overall portfolio, while secured lending will account for 70%, management said. The board has approved this maximum exposure framework, placing a numerical boundary on the digital business as the company expands its lending book.
Management illustrated the cap using a Rs 900 crore AUM scenario and said digital exposure would not exceed Rs 250 crore. Thirty per cent of Rs 900 crore is Rs 270 crore, so the example is below the stated ceiling; management did not explain the difference. Earlier, management described its intended mix as 70% to 75% secured lending and 20% to 25% digital lending, making 30% a maximum rather than its normal operating allocation.
The portfolio has expanded from Rs 294 crore at the March 2026 close cited by management to Rs 610 crore. Secured AUM rose from Rs 160 crore in the prior year to about Rs 410 crore to Rs 420 crore, while management identified Rs 125 crore of digital lending added through fresh borrower acquisition. The reported growth therefore spans both lending categories, but the approved mix requires secured loans to remain the larger component.
Management said it was pursuing total AUM of Rs 900 crore to Rs 950 crore by the end of the financial year while maintaining the 70/30 portfolio structure. At the lower end of that target range, a 30% digital cap would imply up to Rs 270 crore of digital lending, subject to management's more conservative Rs 250 crore example. The framework is tied to the overall book size rather than to a fixed digital-loan amount.
How large does Regency Fincorp expect JetFund to become?
Regency Fincorp is targeting Rs 50 crore to Rs 55 crore of AUM in JetFund by the end of March. Management said the salary-advance platform is already live, has built a small AUM base and should begin contributing revenue and profitability as the lending book increases. It did not disclose JetFund's current AUM, disbursements, pricing or credit-loss data.
The JetFund target is separate from the Rs 125 crore that management said had been added through its digital lending activity. Management described the existing digital product as a short-term, approximately 90-day lending model similar to early salary lending. The call did not state whether any portion of the Rs 125 crore digital book is included in JetFund.
Management linked JetFund's prospective revenue and profitability to the build-out of AUM rather than offering a specific earnings target. It said revenue and profit should follow once AUM is in place, but gave no timetable beyond the end-of-March AUM objective. The disclosed measure is therefore a lending-book target, not a forecast for JetFund income or net profit.
Regency Fincorp also said Regency Pay was awaiting Reserve Bank of India, or RBI, approval for a licence. Management expected the licence in the current quarter and said it would operate the business once approval was received. Unlike JetFund, Regency Pay had no disclosed AUM, revenue or profitability target.
Got a follow-up? Ask IRIS
How is Regency Fincorp acquiring and retaining digital borrowers?
Regency Fincorp attributes its reported 70% digital-lending retention ratio to salaried-customer onboarding and internally developed acquisition channels. Management said its initial practice was to focus on quality customers in the salaried segment, with the aim of retaining regular users of the lending product. It did not define the measurement period or methodology for the 70% retention ratio.
The company said it uses in-house digital marketing and internally generated leads instead of relying primarily on external lead facilitators, associates or affiliate channels. Management said this approach reduces vendor acquisition costs and supports customer selection. It also said borrowers acquired through its own platform are more retainable than those sourced through outside associates.
The digital acquisition model operates alongside Regency Fincorp's secured-lending distribution. Management said the company operates from Noida across 15,000 PIN codes in 25 states and intends to retain its branch-based distribution approach while growing the book. Its average loan ticket was Rs 50 lakh to Rs 55 lakh and could rise to Rs 75 lakh, according to management.
The company does not describe digital lending as a replacement for its secured business. Its stated 70% secured allocation, 20% to 25% intended digital mix and 30% board-approved digital ceiling place JetFund and the existing Rs 125 crore digital book within a broader diversified-lending structure. Growth in the digital book must therefore remain linked to growth in total AUM.
How could funding and acquisitions affect Regency Fincorp's digital plan?
Regency Fincorp is raising about Rs 313 crore through preferential equity and preferential warrants, with Rs 100 crore to Rs 125 crore earmarked for acquiring a digital lending company or platform. Management said the acquired entity would become fully owned by Regency Fincorp, and the transaction could take three to nine months to complete in stages.
Management described the proposed digital acquisition as an arm's-length transaction with a third party. It said the target currently generates about Rs 2 crore of monthly profitability, but Regency Fincorp is assessing whether that level is sustainable, as well as the target's AUM and asset quality. No target name, final purchase price or closing date was disclosed.
The company also said up to Rs 75 crore could be used to acquire a majority stake of more than 50% in one of two gold-loan companies being evaluated. Management said this process could take three to four months, while remaining capital from the Rs 313 crore raise would support MSME lending, digital lending, branch expansion and general corporate purposes.
Management said none of the equity proceeds would be used to repay lenders because portfolio cash flows would service borrowings and asset-liability management had no mismatch. It also said it aimed to reduce the cost of funds to 11.5% by the end of the financial year, a further 100-basis-point reduction. One basis point equals one-hundredth of a percentage point.
Conclusion
Regency Fincorp has combined digital-lending expansion with a formal portfolio constraint. The board-approved 30% ceiling leaves secured lending as at least 70% of AUM, while the Rs 50 crore to Rs 55 crore JetFund objective and the Rs 125 crore existing digital book show the scale management is seeking in digitally sourced lending.
What to watch next is whether JetFund reaches its end-of-March AUM target, whether RBI approval enables Regency Pay to begin operations, and whether the proposed digital acquisition progresses within management's three-to-nine-month timeframe. Management's Rs 900 crore to Rs 950 crore year-end AUM target will also show how the 30% cap is applied as the total lending book increases.