










Runwal cuts net debt-to-equity to 1.5x from 3.1x in Q2 FY27
Key highlights
- Runwal’s net debt-to-equity ratio fell to 1.5x in Q2 FY27 from 3.1x.
- Runwal’s equity base rose to Rs 1,566 crore from Rs 689 crore at the end of Q2 FY26.
- Runwal reported Q2 FY27 pre-sales of Rs 609 crore and gross collections of Rs 550 crore.
- Runwal delivered 1.90 million square feet in H1 FY27 versus 0.86 million square feet in H1 FY26.
powered by IRIS
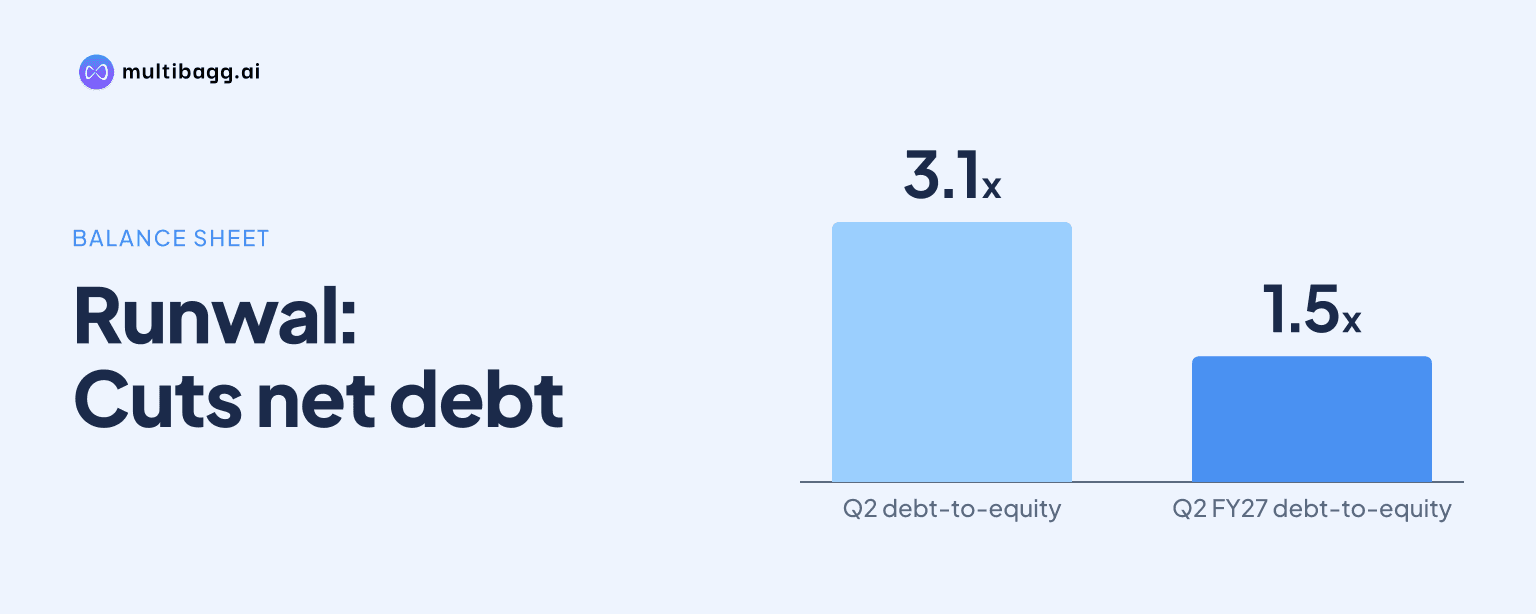
Runwal Enterprises Limited cut its net debt-to-equity ratio to 1.5x at the end of Q2 FY27 from 3.1x, supported by an equity base of Rs 1,566 crore, conversion of convertible debentures, IPO-proceeds recognition and ordinary-course debt repayment. Runwal is also evaluating the sale of a small MyCity land parcel in Dombivli to reduce debt further.
Know Runwal Enterprises inside out
Results, valuation, peers and who's buying, in one view.
How did Runwal cut net debt-to-equity in Q2 FY27?
Runwal cut net debt-to-equity to 1.5x at the end of Q2 FY27 from 3.1x through a larger equity base and debt repayment. Chairman and Managing Director Subodh Subhash Runwal said the ratio reduction was an important development in the quarter and formed part of the company’s continuing deleveraging and balance-sheet plan.
Chief Financial Officer Shashi Bhushan identified three drivers: conversion of convertible debentures into equity, recognition of Rs 500 crore of IPO proceeds in equity, and repayment of debt in the ordinary course of business. The lower ratio therefore reflects both debt-related actions and an increase in the equity denominator.
Runwal’s equity base more than doubled to Rs 1,566 crore at the end of the current quarter from Rs 689 crore at the end of Q2 FY26. The Rs 877 crore increase included the Rs 500 crore of IPO proceeds cited by management, while convertible-debenture conversion also moved funding into equity.
Management did not disclose an absolute net-debt figure, debt maturity profile or interest cost on the November 16, 2026 call. The 1.5x ratio is consequently the clearest disclosed measure of the change in leverage as of September 30, 2026.
What does the lower leverage mean for Runwal’s project funding?
Runwal said its 1.5x net debt-to-equity ratio gives it greater flexibility to invest in new projects and pursue opportunities while maintaining financial discipline. Executive Director Pradumna Kanodia linked the improved capital structure to loan repayment and said a stronger balance sheet could support growth without the earlier level of leverage.
The development portfolio covered about 88.37 million square feet as of September, comprising 18.14 million square feet of ongoing projects and roughly 56 million square feet of upcoming projects. About 75 million square feet was residential, while the balance was in annuity business assets.
Management said redevelopment, joint development, joint ventures, joint development arrangements and partnership models would remain its priority for capital-efficient growth. Runwal said it would assess new opportunities using customer demand, project economics and return on capital.
Runwal is expanding beyond its eastern and central Mumbai suburban base toward south Mumbai and is evaluating potential opportunities in western suburbs. Its portfolio is also being positioned across mid-income, luxury and large-township residential segments.
Will the MyCity land sale reduce Runwal’s debt further?
Runwal plans to monetise a small acreage of land within its MyCity project in Dombivli, and management said the proceeds would reduce debt further. The company appointed JLL to run the mandate and had received interest from around 11 to 12 parties by the Q2 FY27 earnings call.
Management said it was evaluating those expressions of interest and would communicate the outcome soon. It did not disclose the land area, expected sale consideration, potential buyer or transaction timetable.
The proposed monetisation is separate from the IPO-related equity increase and convertible-debt conversion that management said drove the first stage of deleveraging. The CFO said Runwal was evaluating other measures to reduce net debt but did not provide details because significant progress had not yet occurred.
Dombivli also accounted for a substantial part of first-half operating activity. Management said possessions in H1 FY27 were largely at Runwal Gardens and MyCity, both in Dombivli, while certain towers in Phase 3 of Runwal Gardens received occupation certificates during the quarter.
Got a follow-up? Ask IRIS
What operating metrics support Runwal’s deleveraging plan?
Runwal reported higher pre-sales, collections, selling prices and deliveries in Q2 FY27 and H1 FY27. Pre-sales were Rs 609 crore in Q2 FY27, compared with Rs 484 crore in Q1, while gross collections increased 23.5% year on year to Rs 550 crore from Rs 445 crore in Q2 FY26.
Average selling price rose to Rs 14,907 per square foot in Q2 FY27 from Rs 12,600 per square foot in the last quarter of FY26, an increase of around 12%. Management said sales area was broadly similar, so the higher selling price supported the increase in sales value.
Delivered area reached 1.90 million square feet in H1 FY27, compared with 0.86 million square feet in H1 FY26. Runwal delivered just under 1 million square feet in Q2, with occupation certificates for certain Runwal Gardens Phase 3 towers supporting the first-half increase.
Runwal said revenue is recognised when the relevant project receives an occupation certificate and the customer takes possession. Management therefore cautioned that reported revenue and margins can vary between quarters according to the projects and units qualifying for recognition.
What has management said about FY27 sales and revenue?
Management maintained its FY27 pre-sales guidance of roughly Rs 2,500 crore to Rs 3,000 crore, which it described as around 20% growth over the previous year. The CFO said the company expected Q2 to be better than Q1, consistent with the pattern management sees in the sector.
For reported revenue, management said it expected a figure roughly 10% higher than FY26. It attributed the first-half revenue mix largely to Runwal Gardens and MyCity in Dombivli, which it described as affordable-segment projects with relatively lower gross margins.
Management expects an occupation certificate for one tower in a Mumbai mid-income project during the second half of FY27. The CFO said this could result in significant revenue recognition and that margins should revert toward the level achieved in FY26.
Runwal also reported about 300,000 square feet of ongoing commercial projects and around 800,000 square feet in retail-mall assets. These include Runwal BKC and the Dombivli retail mall, which management identified as part of its non-residential and annuity portfolio plan.
Conclusion
Runwal’s reduction in net debt-to-equity from 3.1x to 1.5x reflects a Rs 877 crore increase in equity between Q2 FY26 and Q2 FY27, plus convertible-debenture conversion and ordinary-course debt repayment. Higher Q2 pre-sales of Rs 609 crore, gross collections of Rs 550 crore and H1 deliveries of 1.90 million square feet provide operating context for management’s funding and execution plans.
The next disclosed event to watch is the outcome of the proposed MyCity land monetisation, for which JLL had received interest from around 11 to 12 parties. Management has not given a transaction value or closing date, while it also expects an occupation certificate for a mid-income Mumbai tower in H2 FY27 to support revenue recognition and margins.