










Sagar Cement net debt rose to Rs 1,629.51 crore in Q2 FY27
Key highlights
- Sagar Cement’s net debt rose 2% quarter on quarter to Rs 1,629.51 crore at September 30, 2026.
- Long-term debt increased 3% to Rs 1,481.53 crore, while working-capital debt declined 6% to Rs 253.85 crore.
- Q2 FY27 revenue increased 17% year on year to Rs 705.36 crore, but operating EBITDA fell 12% to Rs 45.31 crore.
- Management projects net debt of Rs 1,552 crore for FY27 and Rs 1,159 crore for FY28.
powered by IRIS
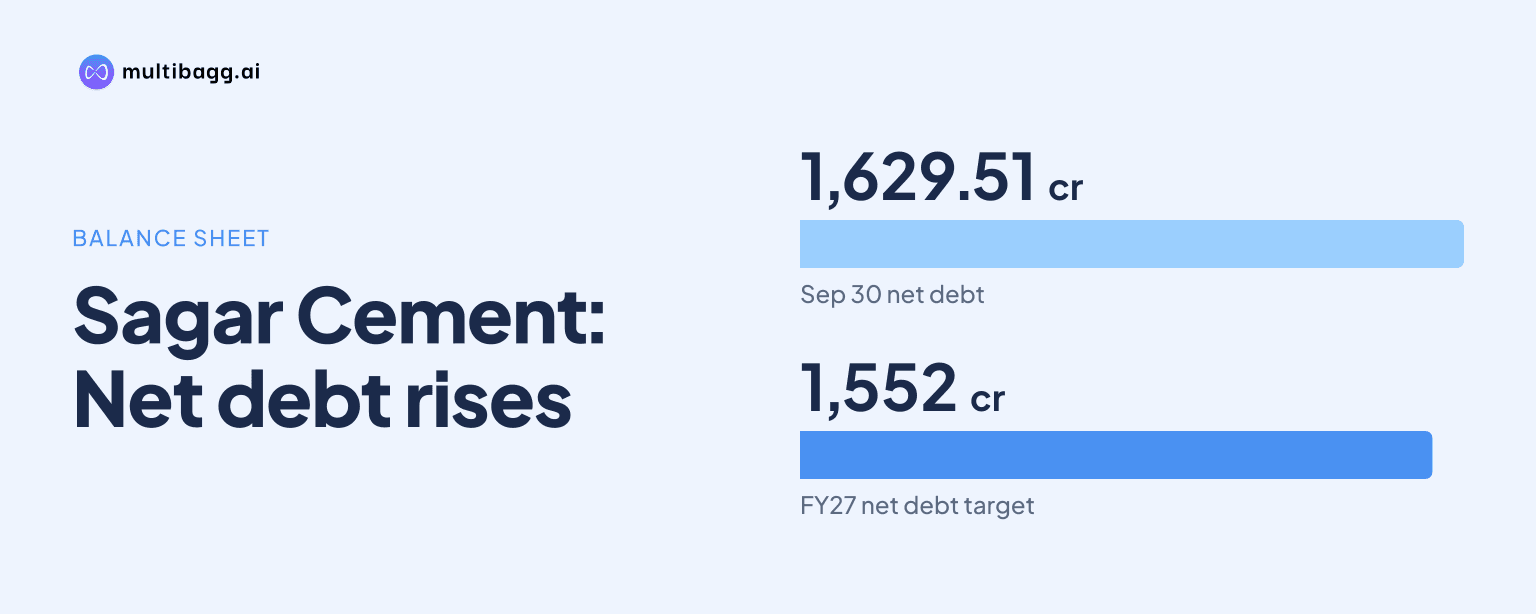
Sagar Cement reported net debt of Rs 1,629.51 crore at September 30, 2026, a 2% increase from Rs 1,598.87 crore at June 30. Its FY27 projected principal and interest payments total Rs 366 crore, while the consolidated cash-flow summary showed Rs 187.24 crore of operating cash flow and Rs 152.10 crore of capital expenditure in the September 30, 2026 column.
Know Sagar Cements inside out
Results, valuation, peers and who's buying, in one view.
Why did Sagar Cement's net debt rise in Q2 FY27?
Sagar Cement's net debt rose because its gross debt increased by more than its cash and bank balance during the quarter. Gross debt stood at Rs 1,735.38 crore on September 30, 2026, against Rs 1,703.60 crore on June 30, 2026, while the cash and bank balance increased to Rs 105.87 crore from Rs 104.73 crore.
Long-term debt increased 3% quarter on quarter to Rs 1,481.53 crore, whereas working-capital debt declined 6% to Rs 253.85 crore. The Rs 31.78 crore increase in gross debt exceeded the Rs 1.14 crore increase in cash and bank balance, resulting in a Rs 30.64 crore rise in net debt.
The debt profile also reported a long-term debt-to-equity ratio of 0.83 on September 30, compared with 0.78 on June 30. Net worth declined 3% to Rs 1,781.24 crore from Rs 1,832.80 crore over the quarter, according to the same debt disclosure.
The consolidated financial-position statement gives a comparison with March 31, 2026. Consolidated borrowings rose to Rs 1,735.38 crore on September 30 from Rs 1,671.99 crore at March 31, while other equity including non-controlling interest fell to Rs 1,755.10 crore from Rs 1,834.78 crore.
What debt payments does Sagar Cement project for FY27?
Sagar Cement projects Rs 366 crore of principal and interest payments for FY27. The disclosed schedule comprises Rs 164 crore of principal repayment and Rs 202 crore of interest on term loans and working capital.
The quarterly schedule lists Rs 84 crore in FY27 Q1, Rs 87 crore in Q2, and Rs 98 crore in each of Q3 and Q4. The figures are projections in the presentation, rather than reported payments.
For FY28, Sagar Cement projects total payments of Rs 397 crore, comprising Rs 195 crore of principal and Rs 203 crore of interest. Each FY28 quarter is scheduled at Rs 99 crore, including Rs 49 crore of principal and Rs 51 crore of interest.
Management's debt outlook projects gross debt of Rs 1,720 crore for FY27, compared with Rs 1,672 crore in FY26, followed by Rs 1,532 crore in FY28. It projects term loans of Rs 1,399 crore and working capital of Rs 321 crore in FY27, with net debt projected at Rs 1,552 crore in FY27 and Rs 1,159 crore in FY28.
Got a follow-up? Ask IRIS
How much cash did Sagar Cement generate after capital expenditure?
Sagar Cement reported Rs 187.24 crore of net cash flow from operating activities in the September 30, 2026 column of its consolidated cash-flow summary. Capital expenditure was Rs 152.10 crore, meaning operating cash flow exceeded capital expenditure by Rs 35.14 crore before investing and financing cash flows.
Net cash used in investing activities was Rs 145.56 crore in that column. This included Rs 152.10 crore of capital expenditure, partly offset by Rs 5.70 crore of interest received and Rs 0.84 crore classified as other items.
The cash-flow summary showed Rs 215.56 crore of operating cash flow and Rs 423.31 crore of capital expenditure in the March 31, 2026 column. In the September 30 column, loss before tax was Rs 105.31 crore, while changes in working capital contributed Rs 71.61 crore and other adjustments contributed Rs 224.94 crore.
Financing activities used Rs 43.34 crore in the September 30 column. Sagar Cement received Rs 173.07 crore from borrowings, repaid Rs 71.97 crore of borrowings and made Rs 99.10 crore of interest or dividend payments, alongside Rs 45.34 crore of other financing outflows.
Can Sagar Cement's operating performance cover its finance cost?
Sagar Cement's Q2 FY27 consolidated operating earnings before interest, tax, depreciation and amortisation, or EBITDA, were below its finance cost. Operating EBITDA was Rs 45.31 crore, while finance cost was Rs 55.16 crore, compared with operating EBITDA of Rs 51.33 crore and finance cost of Rs 46.48 crore in Q2 FY26.
Revenue from operations increased 17% year on year to Rs 705.36 crore in Q2 FY27 and sales volume rose 26% to 17.09 lakh tonnes. However, operating EBITDA declined 12%, and the operating EBITDA margin decreased to 6% from 9% a year earlier.
The per-ton comparison shows that net realisation declined 7% year on year to Rs 4,127 in Q2 FY27. Total expenditure per ton fell 5% to Rs 3,862, but power and fuel cost increased 3% to Rs 1,473 per ton and freight rose 5% to Rs 900 per ton, bringing EBITDA per ton down 30% to Rs 265 from Rs 377.
For H1 FY27, consolidated operating EBITDA was Rs 117.73 crore, down 32% from Rs 172.78 crore in H1 FY26. Finance cost increased 15% to Rs 107.39 crore, and loss after tax widened to Rs 79.64 crore from Rs 36.68 crore; plants operated at around 63% in Q2 FY27.
Management said cement prices were soft in July and August before recovering to some extent in September, with realisations around 6% lower sequentially in Q2 FY27. Management expects demand momentum to improve in H2 FY27 after the monsoon and cited waste-heat recovery systems, renewable-energy use, logistics optimisation and plant efficiencies as its operating initiatives.
Conclusion
Sagar Cement entered the second half of FY27 with net debt of Rs 1,629.51 crore, 2% above the June 30 level, and projected FY27 principal and interest payments of Rs 366 crore. Volume growth and a 17% increase in Q2 revenue did not prevent operating EBITDA per ton from falling to Rs 265, leaving quarterly operating EBITDA of Rs 45.31 crore below finance cost of Rs 55.16 crore.
The next disclosed markers are projected total debt-service payments of Rs 98 crore in each of FY27 Q3 and Q4, alongside management's expectation of a post-monsoon improvement in H2 FY27 demand. Management's outlook also projects net debt of Rs 1,552 crore for FY27 and Rs 1,159 crore for FY28, making operating cash generation, capital expenditure and borrowing movements relevant to that path.