










Sansera ADS reaches 14.6% of sales as Auto ICE share falls
Key highlights
- ADS represented 14.6% of Sansera's H1FY27 product sales, up from 9.6% in FY26.
- Auto ICE represented 65.6% of Sansera's H1FY27 product sales, down from 70.1% in FY26.
- ADS product sales were Rs 288.7 crore in H1FY27, compared with Rs 315.5 crore in FY26.
- Management guided to FY27 ADS revenue of Rs 550 crore to Rs 600 crore and disclosed Rs 586.97 crore of ADS backlog at September 2026.
powered by IRIS
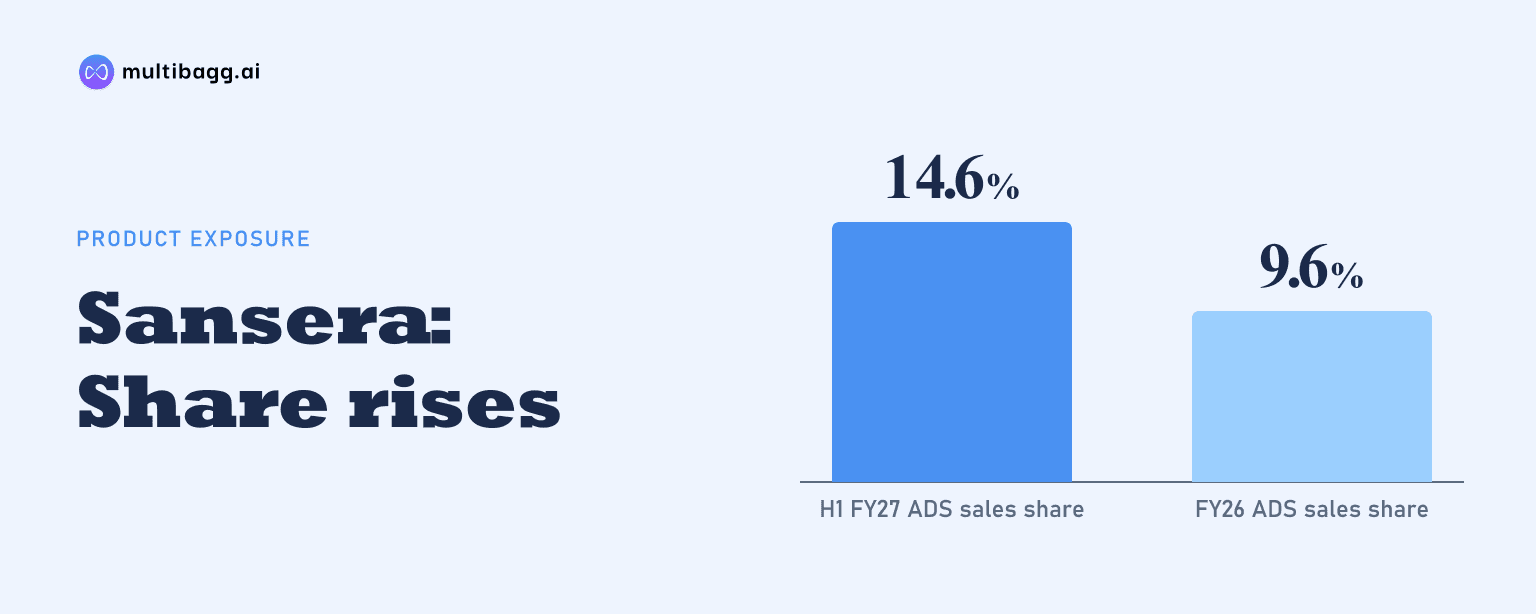
Sansera Engineering Limited reported that Aerospace, Defence and Semiconductor (ADS) product sales were 14.6% of H1FY27 sales, while Auto internal-combustion-engine (ICE) sales were 65.6%, versus 9.6% and 70.1%, respectively, in FY26. ADS sales reached Rs 288.7 crore, nearly matching FY26's Rs 315.5 crore as Sansera's non-ICE businesses took a larger share.
Know Sansera Engineering inside out
Results, valuation, peers and who's buying, in one view.
How did Sansera's product-sales mix change in H1FY27?
Sansera's product-sales mix changed principally because ADS gained 5.0 percentage points from FY26 to 14.6% in H1FY27, while Auto ICE declined 4.5 percentage points to 65.6%. Tech-agnostic and electric-vehicle (xEV) sales held at 13.5%, while other non-auto fell to 6.3% from 6.8%.
The three categories outside Auto ICE represented 34.4% of H1FY27 product sales, compared with 29.9% in FY26. These segment figures exclude other operating income and scrap sales, whereas Sansera reported consolidated revenue of Rs 2,112.7 crore for H1FY27, up 33% year on year.
Sansera's longer-term disclosures show that the mix shift predates H1FY27. Auto ICE represented 83.4% of product sales in FY21, whereas ADS represented 3.8% and tech-agnostic and xEV 5.4%; by FY26, those shares had become 70.1%, 9.6% and 13.5%, respectively.
Why did ADS become a larger Sansera business?
ADS became a larger Sansera business because product sales reached Rs 288.7 crore in H1FY27, against Rs 315.5 crore for all of FY26 and Rs 54.8 crore in FY21. Sansera identifies ADS as its fastest-growing vertical over FY21 to FY26, with 5.7 times sales growth and a 41.6% compound annual growth rate.
The H1FY27 ADS figure was about 91.5% of the FY26 full-year amount, based on the disclosed segment sales, while its mix share rose by 5.0 percentage points within six months. By comparison, tech-agnostic and xEV product sales were Rs 267.9 crore in H1FY27 and retained a 13.5% share, below ADS's 14.6% share.
Sansera lists cargo latch pawls, cargo housings and door beams alongside avionics, aerostructure tailcones, aerostructure beams, end covers and actuation gimbals in ADS. Its stated customer categories include a global European aircraft original-equipment manufacturer, global Tier 1 suppliers and semiconductor fab-equipment original-equipment manufacturers.
Management attributes ADS's multi-year visibility to an aerospace-demand rebound, new customer wins, an additional large aerospace original-equipment manufacturer being added and growth in semiconductor-equipment business. It has disclosed Rs 586.97 crore of unexecuted ADS order backlog as of September 2026 and said capital is being prioritised to ADS, with targeted asset turns of 2.0 to 2.2 times.
Is Sansera's Auto ICE business declining in absolute terms?
Sansera's disclosure does not establish an H1FY27 year-on-year decline in Auto ICE sales, but it does show that Auto ICE's mix share is moderating as other categories grow faster. Auto ICE product sales were Rs 1,297.2 crore in H1FY27, and the segment's share fell to 65.6% from 70.1% in FY26 and 83.4% in FY21.
Across the comparable full financial years, Auto ICE sales increased from Rs 1,209.2 crore in FY21 to Rs 2,304.1 crore in FY26, or 1.9 times, at a stated 13.8% compound annual growth rate. Sansera says its Auto ICE share moderates because emerging segments are expanding faster, rather than describing a contraction in the legacy segment.
The H1FY27 Auto ICE range includes connecting rods, crankshafts, rocker arms, balance shafts, gear-shifter forks and timing sprockets. Two-wheelers accounted for 36.7% of total sales, passenger vehicles 17.4% and commercial vehicles 11.0%, with the balance of Auto ICE sales coming from three-wheelers.
Got a follow-up? Ask IRIS
What other segments are affecting Sansera's mix?
Tech-agnostic and xEV is Sansera's second-largest non-ICE category, with Rs 267.9 crore of H1FY27 product sales and a 13.5% share. The category grew from Rs 79.4 crore in FY21 to Rs 444.9 crore in FY26, representing 5.6 times growth and a stated 41.2% compound annual growth rate.
Within H1FY27 sales, xEV accounted for 5.1% and tech-agnostic products for 8.4%. Sansera cites drivetrain rotor shafts, aluminium balance rings, gear-motor counter drives and hollow shafts in xEV, supported by a dedicated hybrid and electric-component facility in Bengaluru and hybrid programmes with a leading global Japanese original-equipment manufacturer.
Other non-auto product sales were Rs 124.7 crore in H1FY27, after Rs 222.1 crore in FY26 and Rs 137 crore in FY21. This business, reported separately from ADS since FY25, covers off-road, agriculture and industrial products including mounting brackets, pump barrels, camshafts, common rails and valve bridges; its share fell from 7.8% in FY21 to 6.3% in H1FY27.
What will determine Sansera's next mix shift?
Management's FY27 ADS revenue guidance of Rs 550 crore to Rs 600 crore is the immediate measure of whether the segment can extend its 14.6% H1FY27 share. That guidance is forward-looking rather than reported revenue, and its conversion depends on execution of the Rs 586.97 crore backlog disclosed at September 2026.
Sansera also plans about Rs 500 crore of annual capital expenditure across ICE, ADS and forging, including ramp-up of a new aerospace facility for backlog. Management has said it intends to progress toward 40% of revenue from emerging segments, while targeting an 80% robotics ratio on new lines.
A separate operating milestone is commercial production at Sansera's joint venture with Nichidai Corporation of Japan, planned for H2FY27. The presentation says the venture extends the company's reach into driveline and steering parts, while Sansera also plans to scale aluminium forging and tech-agnostic orders.
Conclusion
Sansera's H1FY27 mix shows that Auto ICE remains its largest business at 65.6% of product sales, but ADS has become the largest non-ICE segment at 14.6%, ahead of tech-agnostic and xEV at 13.5%. The change reflects ADS sales of Rs 288.7 crore in H1FY27, compared with Rs 54.8 crore in FY21, alongside a lower Auto ICE share rather than evidence of a reported H1 sales contraction.
The next disclosures to watch are progress toward management's Rs 550 crore to Rs 600 crore FY27 ADS revenue guidance, conversion of the Rs 586.97 crore ADS backlog reported at September 2026 and commercial production at the Nichidai joint venture in H2FY27. Sansera's stated plan to move emerging segments to 40% of revenue will also depend on the planned annual capital expenditure of about Rs 500 crore.