










Sansera non-auto share reaches 20.9% as ADS sales triple
Key highlights
- Sansera’s Non-auto share increased to 20.9% in Q2 FY27 from 13.2% in Q2 FY26.
- ADS sales rose 206.5% year on year in Q2 FY27 and represented 14.9% of revenue.
- Q2 FY27 revenue increased 32% to Rs 1,091.5 crore and EBITDA margin reached 19.4%.
- Sansera disclosed an ADS backlog of Rs 5,869.7 crore as of September 30, 2026.
powered by IRIS
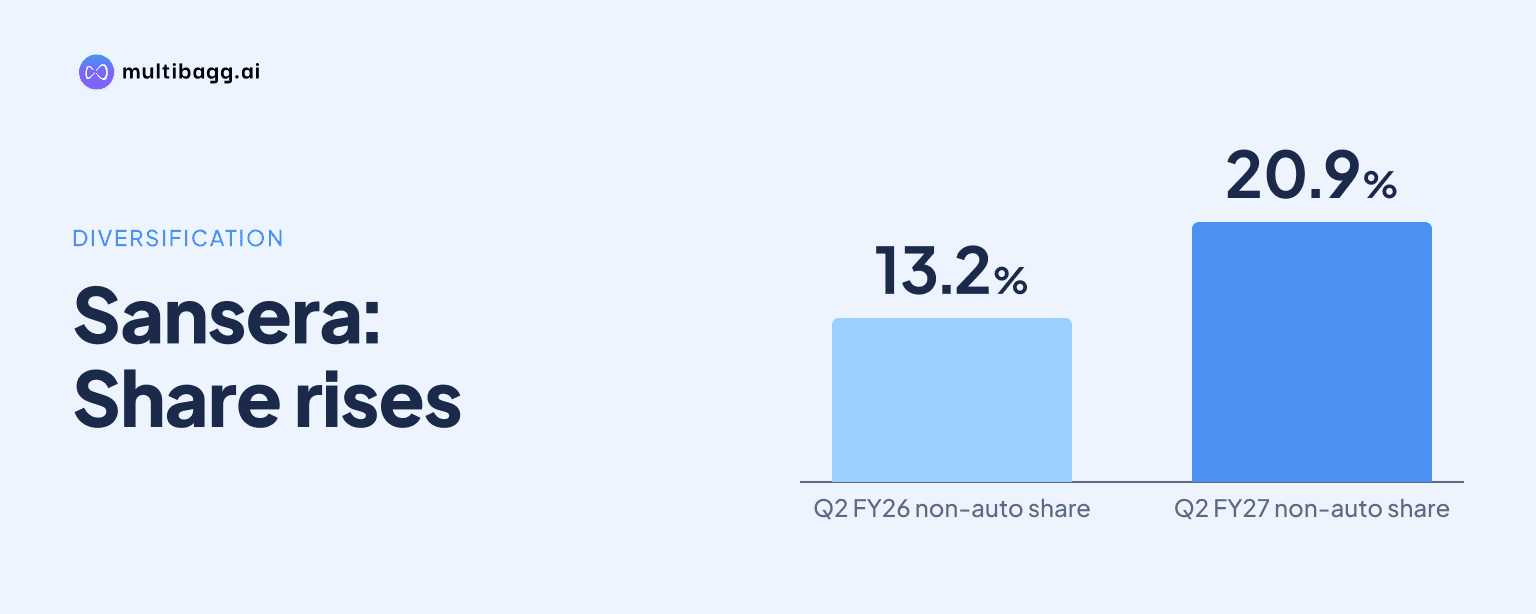
Sansera Engineering Limited reported that Non-auto accounted for 20.9% of consolidated revenue in Q2 FY27, up from 13.2% in Q2 FY26, as ADS sales increased 206.5% year on year and contributed 14.9% of quarterly sales. Consolidated revenue rose 32% to Rs 1,091.5 crore.
Know Sansera Engineering inside out
Results, valuation, peers and who's buying, in one view.
How did Sansera’s sales mix change in Q2 FY27?
Sansera’s Non-auto sales share increased by 7.7 percentage points to 20.9% in Q2 FY27 from 13.2% a year earlier. Auto-ICE remained its largest end-use segment at 65.7% of sales, while Auto-Tech Agnostic and xEV accounted for 13.4%. Together, Non-auto and Auto-Tech Agnostic and xEV represented 34.3% of Q2 FY27 sales.
The H1 FY27 mix was broadly similar, with Non-auto at 20.9%, Auto-Tech Agnostic and xEV at 13.5%, and Auto-ICE at 65.6%. Within Q2 FY27 Auto-ICE sales, motorcycles represented 32.0% of total company revenue, passenger vehicles 17.3%, and scooters 5.9%. Sansera did not disclose comparable Q2 FY26 shares for the two automotive categories.
Sansera said Auto-ICE revenue grew 18.2% year on year even as its share declined to 65.7%. This indicates that the reduced Auto-ICE proportion reflected faster expansion in other segments, rather than a reported fall in ICE sales. Auto-Tech Agnostic and xEV sales grew 27.0% year on year in Q2 FY27.
What drove Sansera’s Non-auto growth?
Sansera identified ADS as the principal Non-auto growth driver, reporting a 206.5% year-on-year rise in ADS sales for Q2 FY27. ADS accounted for 14.9% of total quarterly sales, making it the largest disclosed component of the 20.9% Non-auto contribution. The company’s business-growth table showed Non-auto sales rising 107.7% year on year.
Other disclosed Non-auto activities expanded at lower rates in Q2 FY27. Off-road sales increased 8.5% year on year, while agriculture sales rose 26.1%. International business grew 56.2%, ahead of the India business’s 20.6% growth, with other foreign countries increasing 128.9%, primarily due to semiconductor business performance.
The earnings release contains differing ADS growth figures. Its key-highlights section gives ADS growth of 206.5% and describes it as more than three times year on year, while management commentary refers to 20.7% growth in ADS. Sansera did not reconcile the two figures, although the 206.5% measure is the one used in the release’s operational highlights.
How did Sansera’s Q2 FY27 earnings compare with last year?
Sansera reported Q2 FY27 revenue from operations of Rs 1,091.5 crore, up 32% from Rs 825.2 crore in Q2 FY26. Earnings before interest, tax, depreciation and amortisation, or EBITDA, increased 48% to Rs 211.2 crore, while the EBITDA margin rose to 19.4% from 17.3%. Management said Auto-ICE, Auto-Tech Agnostic and xEV, and Non-auto each recorded their highest quarterly sales.
Reported profit after tax increased 52% to Rs 108.6 crore from Rs 71.4 crore, taking the margin to 10.0% from 8.6%. For H1 FY27, revenue rose 33% to Rs 2,112.7 crore and EBITDA increased 48% to Rs 407.3 crore. The H1 EBITDA margin was 19.3%, compared with 17.3% in H1 FY26.
H1 FY27 profit included a Rs 16.9 crore exceptional litigation-settlement cost recognised in Q1 FY27. Sansera said the settlement was expected to be substantially covered by insurance and was made without admission of liability. The release also states a normalised profit after tax of Rs 100 crore after excluding a Rs 12.7 crore post-tax impact, a figure that is inconsistent with reported H1 profit after tax of Rs 196 crore and is not explained in the document.
Got a follow-up? Ask IRIS
What order visibility supports Sansera’s diversification plan?
Sansera reported an unexecuted ADS order backlog of Rs 5,869.7 crore as of September 30, 2026. Management said this backlog extended over the next five years, making it separate from its order book for new business excluding ADS. The backlog is relevant to the business that delivered 14.9% of Q2 FY27 sales.
The release gives two different values for the non-ADS order-book measure. Its highlights section puts peak annual revenues from new business excluding ADS at Rs 2,241 crore as of September 30, 2026, while management commentary states Rs 224 crore as of September 2026. Sansera did not explain whether the difference arose from a typographical error, a definition change, or another measurement basis.
Management said it was focused on adding customers, increasing wallet share, and moving into larger and more complex parts. It also cited record domestic automotive volumes and recovering exports, while saying original equipment manufacturers were consolidating supplier bases and outsourcing to capable suppliers. These are management’s assessments rather than revenue forecasts.
What is Sansera planning for FY27?
Sansera plans approximately Rs 800 crore of capital expenditure in FY27 to expand manufacturing capabilities and pursue emerging-technology opportunities. The company did not disclose how this spending would be split between Auto-ICE, Auto-Tech Agnostic and xEV, Non-auto, or ADS, despite Non-auto accounting for 20.9% of Q2 FY27 sales.
Management said its diversification journey had “only just begun” and pointed to the ADS backlog and new-business order book as support for the next phase. The release does not specify the timing of ADS backlog conversion, a FY27 revenue target, or the allocation of the planned Rs 800 crore capital expenditure. Those items remain unresolved in assessing the pace of further mix change.
Conclusion
Sansera’s Q2 FY27 results show that faster growth outside Auto-ICE changed its revenue composition. Non-auto rose to 20.9% of sales from 13.2% a year earlier, led by the disclosed 206.5% rise in ADS sales, while Auto-ICE still expanded 18.2% but represented 65.7% of revenue. Revenue growth of 32% and EBITDA growth of 48% accompanied that mix shift.
The next items to watch are execution of the Rs 5,869.7 crore ADS backlog over the five years cited by management, deployment of approximately Rs 800 crore of FY27 capital expenditure, and clarification of the conflicting ADS growth, normalised profit, and non-ADS order-book figures disclosed in the release.