










Sheela Foam: Furlenco subsidiary targets Rs 500 crore revenue
Key highlights
- Sheela Foam made Furlenco a subsidiary from October 1, 2026.
- Furlenco reported H1 FY27 revenue of Rs 229 crore, up 34% year on year.
- Furlenco’s H1 FY27 EBITDA rose 69% to Rs 89 crore, with a margin close to 39%.
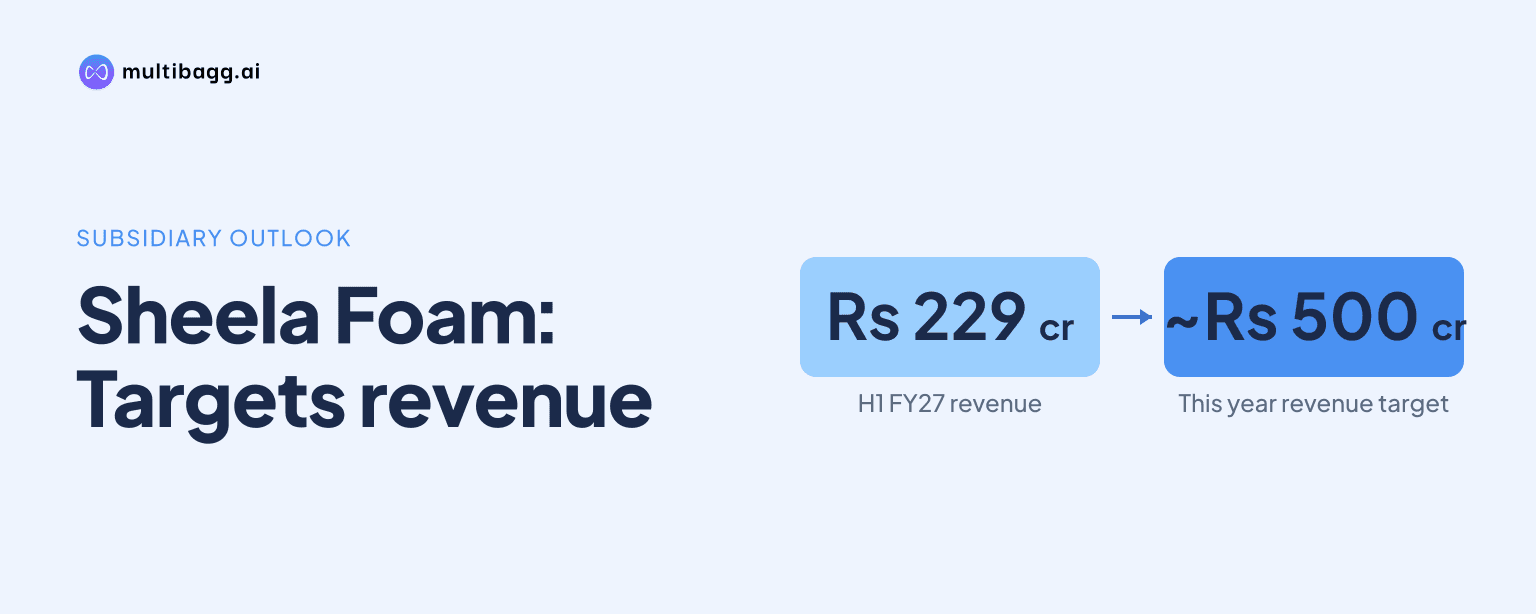
- Management expects Furlenco to reach about Rs 500 crore revenue and about 40% EBITDA margin this year.
powered by IRIS
Sheela Foam Limited made Furlenco a subsidiary from October 1, 2026, after the furniture-rental business moved from an annual loss of about Rs 130 crore in FY24 toward expected revenue of Rs 500 crore and an earnings before interest, tax, depreciation and amortisation (EBITDA) margin of about 40% this year. The change brings Furlenco into Sheela Foam’s consolidated reporting from Q3 FY27.
Know Sheela Foam inside out
Results, valuation, peers and who's buying, in one view.
How did Furlenco become a Sheela Foam subsidiary?
Furlenco became a subsidiary because Sheela Foam obtained control over the company despite holding around 43% on a fully diluted basis. Management said private-equity investors gave up their special rights during the quarter, giving Sheela Foam the control required to classify Furlenco as a subsidiary from October 1, 2026.
The accounting treatment will be a line-by-line consolidation of 100% of Furlenco’s profit and loss account and balance sheet from Q3 FY27, with minority interest deducted below the profit line. Sheela Foam said its current accounting ownership is 35% of converted equity, while its fully diluted holding is 43% because some holdings are compulsorily convertible preference shares (CCPS).
This means group revenue and EBITDA will include Furlenco’s full operating figures rather than only a share of its earnings. Management said the remaining interest held by other shareholders will be reflected as minority interest, while Furlenco’s consolidation is expected to lift the group’s current-year revenue run rate toward Rs 5,000 crore.
How far has Furlenco’s business performance improved?
Furlenco’s performance has improved from about Rs 139 crore of revenue and an annual loss close to Rs 130 crore when Sheela Foam invested in FY24. Management now expects Furlenco to close the current year at around Rs 500 crore of revenue, almost four times the FY24 level, with an EBITDA margin of about 40%.
The H1 FY27 figures indicate the scale of that improvement. Furlenco reported revenue of about Rs 229 crore, up 34% year on year, and EBITDA of Rs 89 crore, up 69%. Its stated EBITDA margin was close to 39%, broadly consistent with management’s expectation of about 40% for the full year.
Management attributed profitability to Furlenco’s asset-based model and utilisation discipline. Furlenco has more than 2 lakh subscribers across more than 30 cities, offers a catalogue of more than 300 products, and maintains asset utilisation above 90%, according to Sheela Foam.
What does Furlenco add to Sheela Foam’s portfolio?
Furlenco adds furniture rental as Sheela Foam’s second major business pillar, alongside mattress, foam and cushioning, and international subsidiaries plus technology initiatives. Management described the group as having more than 13 brands and said Furlenco also sits alongside branded furniture retail activities under the Sleepwell and Kurlon brands.
The rental model differs from Sheela Foam’s established mattress and foam operations because it earns from subscriptions rather than a one-time sale. Management said Furlenco serves people moving homes or cities and consumers seeking flexibility, with younger and Gen Z customers identified as an important audience for furniture rental.
Sheela Foam reported consolidated Q2 FY27 revenue of Rs 1,045 crore, up 19% year on year, while operating EBITDA remained at Rs 87 crore and profit after tax (PAT) rose to Rs 46 crore from Rs 10 crore. Furlenco was not yet consolidated in those Q2 figures because its subsidiary status began on October 1, after the September 30 quarter-end.
For H1 FY27, Sheela Foam’s consolidated revenue rose 22% to Rs 2,077 crore from Rs 1,696 crore, and operating EBITDA increased 23% to Rs 200 crore from Rs 162 crore. Mattress revenue grew 11% during the half year and foam grew 26%, while Furlenco delivered its separately stated Rs 229 crore of H1 revenue before Q3 consolidation.
Got a follow-up? Ask IRIS
How could Furlenco change Sheela Foam’s financial profile?
Furlenco could raise Sheela Foam’s reported revenue and EBITDA because management expects its current-year contribution to be Rs 500 crore to Rs 600 crore of revenue and about Rs 200 crore of EBITDA. Management said Sheela Foam, before adding Furlenco, is anticipated to generate Rs 4,300 crore to Rs 4,400 crore of consolidated revenue in the current year.
On that basis, management expects the combined group to close the year near Rs 5,000 crore of revenue and roughly Rs 600 crore of EBITDA, implying a margin a little above 12%. The expected Furlenco EBITDA contribution of Rs 200 crore is material relative to Sheela Foam’s Rs 400-odd crore EBITDA in the previous year and the additional Rs 50 crore to Rs 100 crore management expects from the pre-Furlenco business this year.
The potential margin effect comes as Sheela Foam’s existing operations faced raw-material inflation in Q2 FY27. Management said consolidated operating EBITDA margin was 8.4% in the quarter, with polyol prices up 65% and toluene diisocyanate (TDI) up 33% since mid-February. It said a return to conditions similar to those before February could support about 12% profitability without Furlenco, and adding Furlenco would contribute about 3 percentage points.
Furlenco’s incorporation also broadens the group’s revenue mix while international businesses expand. Australia’s Joyce reported H1 revenue of Rs 241 crore, up 16%, with a 13.4% EBITDA margin, while Spain’s Interplasp generated Rs 250 crore, up 44%, with a 10.7% EBITDA margin for H1 FY27.
Conclusion
Furlenco’s transition to subsidiary status changes Sheela Foam’s reported group structure because the full rental business will enter consolidated revenue and EBITDA from Q3 FY27. The business has grown from Rs 139 crore of FY24 revenue and a loss close to Rs 130 crore to Rs 229 crore of H1 FY27 revenue and Rs 89 crore of EBITDA, giving the furniture-rental pillar a larger role in the portfolio.
The next result to watch is Q3 FY27, when Sheela Foam plans to begin line-by-line consolidation of Furlenco and deduct minority interest below profit. Management’s current-year benchmarks are Rs 500 crore to Rs 600 crore of Furlenco revenue, about Rs 200 crore of its EBITDA, and approximately Rs 5,000 crore of combined group revenue; raw-material prices and Middle East logistics remain an unresolved influence on the legacy business margins.