










Sheela Foam's Furlenco reaches 39% EBITDA margin in H1 FY27
Key highlights
- Furlenco revenue rose 3.3 times to Rs 229 crore in H1 FY27 from Rs 69 crore in H1 FY24.
- Furlenco EBITDA margin changed from negative 15% at acquisition to 38.8% in H1 FY27.
- Furlenco subscribers increased to 201,000 from 56,000, while AUM rose to Rs 599 crore from Rs 242 crore.
- Furlenco became an SFL subsidiary with effect from October 1, 2026.
powered by IRIS
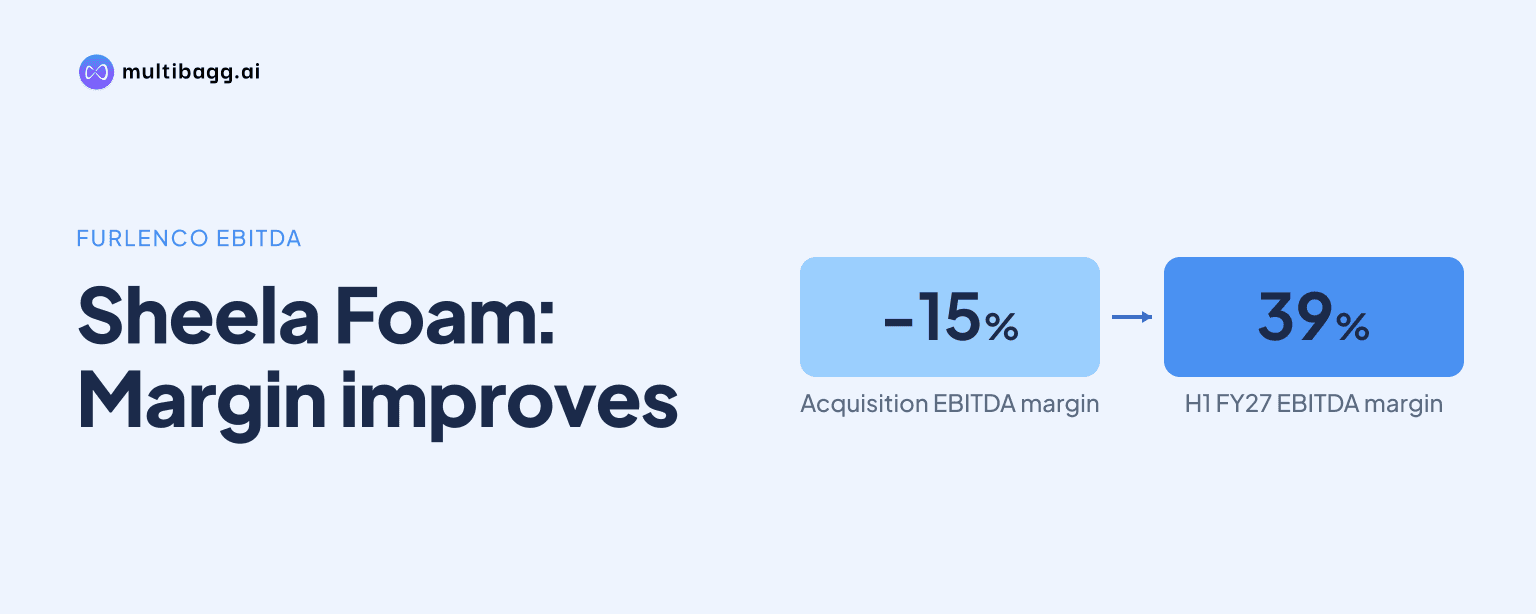
Sheela Foam’s Furlenco recorded Rs 229 crore of revenue and a 38.8% earnings before interest, tax, depreciation and amortisation (EBITDA) margin in H1 FY27, compared with Rs 69 crore and a negative 15% margin at acquisition in H1 FY24. The pro forma figures show Rs 89 crore of EBITDA, and Furlenco became an SFL subsidiary from October 1, 2026.
Know Sheela Foam inside out
Results, valuation, peers and who's buying, in one view.
How did SFL's Furlenco perform in H1 FY27?
SFL’s Furlenco generated Rs 229 crore in revenue and Rs 89 crore in EBITDA in H1 FY27, producing a 38.8% EBITDA margin on the company’s pro forma consolidation basis. The presentation rounds the same margin to 39% in its turnaround comparison and identifies Furlenco as the group’s furniture and living rental business.
Furlenco accounted for Rs 229 crore of the Rs 2,306 crore combined pro forma revenue shown for SFL and Furlenco. Its Rs 89 crore of EBITDA was included in combined EBITDA of Rs 281 crore, while the presentation separately showed SFL revenue of Rs 2,077 crore and EBITDA of Rs 192 crore.
How has SFL's Furlenco changed since acquisition?
SFL’s Furlenco increased revenue 3.3 times from Rs 69 crore at acquisition in H1 FY24 to Rs 229 crore in H1 FY27. Subscribers rose from 56,000 to 201,000, a 3.6-times increase, while assets under management (AUM) expanded 2.5 times from Rs 242 crore to Rs 599 crore.
The EBITDA margin changed from negative 15% in H1 FY24 to 39% in H1 FY27, a 54-percentage-point movement. Return on equity (ROE) changed from negative 143% to positive 18% over the same period. SFL characterises this progression as evidence of its ability to identify and turn around businesses, but the presentation does not break out the individual operating drivers of the margin change.
What does Furlenco's consolidation mean for SFL?
Furlenco became an SFL subsidiary with effect from October 1, 2026, according to the H1 FY27 presentation. SFL presents the Rs 229 crore of Furlenco revenue and Rs 89 crore of EBITDA as pro forma amounts alongside its Rs 2,077 crore revenue and Rs 192 crore EBITDA, rather than within the reported H1 FY27 consolidated income statement presented elsewhere.
On the stated pro forma basis, combined EBITDA margin is 12.2%, compared with 9.2% for SFL, a difference of 3 percentage points. Combined revenue of Rs 2,306 crore is Rs 229 crore above SFL’s figure. These comparisons reflect the presentation’s pro forma arithmetic and do not establish the timing or accounting treatment of Furlenco’s contribution in later reported periods.
Got a follow-up? Ask IRIS
How does SFL's Furlenco margin compare with other businesses?
Furlenco’s 38.8% EBITDA margin was above the 28.1% margin reported for Staqo, 13.4% for Joyce in Australia, 10.7% for Interplasp in Spain and SFL’s 8.4% standalone EBITDA margin in H1 FY27. The presentation therefore places Furlenco at the highest margin among the separately listed businesses, although it does not provide revenue figures for every unit on that page.
SFL’s reported consolidated financial results, which differ from the pro forma combination, showed H1 FY27 operating revenue of Rs 2,077 crore, up 22% year on year, and operating EBITDA of Rs 200 crore, up 23%. Operating EBITDA margin was 9.6%, up 5 basis points, while reported EBITDA margin was 9.2% after a 0.4% provision related to one-time receivable provisions of A.H. Beard in Australia.
What operating milestones has SFL disclosed for Furlenco?
SFL disclosed that Furlenco’s co-branded experience-store programme was live with more than 40 dealers in H1 FY27. The company also reported 48 operational stores in its geographical-footprint update, but did not specify how many were Furlenco locations or provide a store-expansion target.
The wider group’s H1 FY27 mattress business recorded 11% value growth and 1% volume growth, while foam recorded 26% value growth and a 1% volume decline. E-commerce posted 2% volume growth and 13% value growth, and U2O posted 1% volume growth and 41% value growth. These measures provide portfolio context, while Furlenco’s disclosed turnaround measures are revenue, subscribers, AUM, EBITDA margin and ROE.
Conclusion
SFL’s disclosed figures show a substantial change in Furlenco between H1 FY24 and H1 FY27: revenue rose from Rs 69 crore to Rs 229 crore, subscribers from 56,000 to 201,000, and EBITDA margin from negative 15% to 39%. In the H1 FY27 pro forma combination, Furlenco contributed Rs 89 crore of EBITDA and lifted the shown combined EBITDA margin to 12.2% from SFL’s 9.2%.
The next item to watch is how Furlenco appears in SFL’s reported financial results after it became a subsidiary on October 1, 2026. The presentation identifies more than 40 dealers in the co-branded experience-store programme and 48 operational stores, but sets no numerical target for additional dealers, stores, subscribers, revenue or margins.