










Subros reports record Q2 revenue as EBITDA margin drops to 7.66%
Key highlights
- Subros reported record Q2 FY2026-27 revenue from operations of Rs 1,198.90 crore, up 36.27% year on year.
- Q2 FY2026-27 EBITDA was Rs 91.47 crore, while EBITDA margin declined to 7.66% from 10.04% a year earlier.
- Material cost rose to 76.57% of Q2 net sales from 73.08% in Q2 FY2025-26.
- HY FY2026-27 PAT increased 5.86% to Rs 86.02 crore, while PAT margin declined to 3.87% from 4.64%.
powered by IRIS
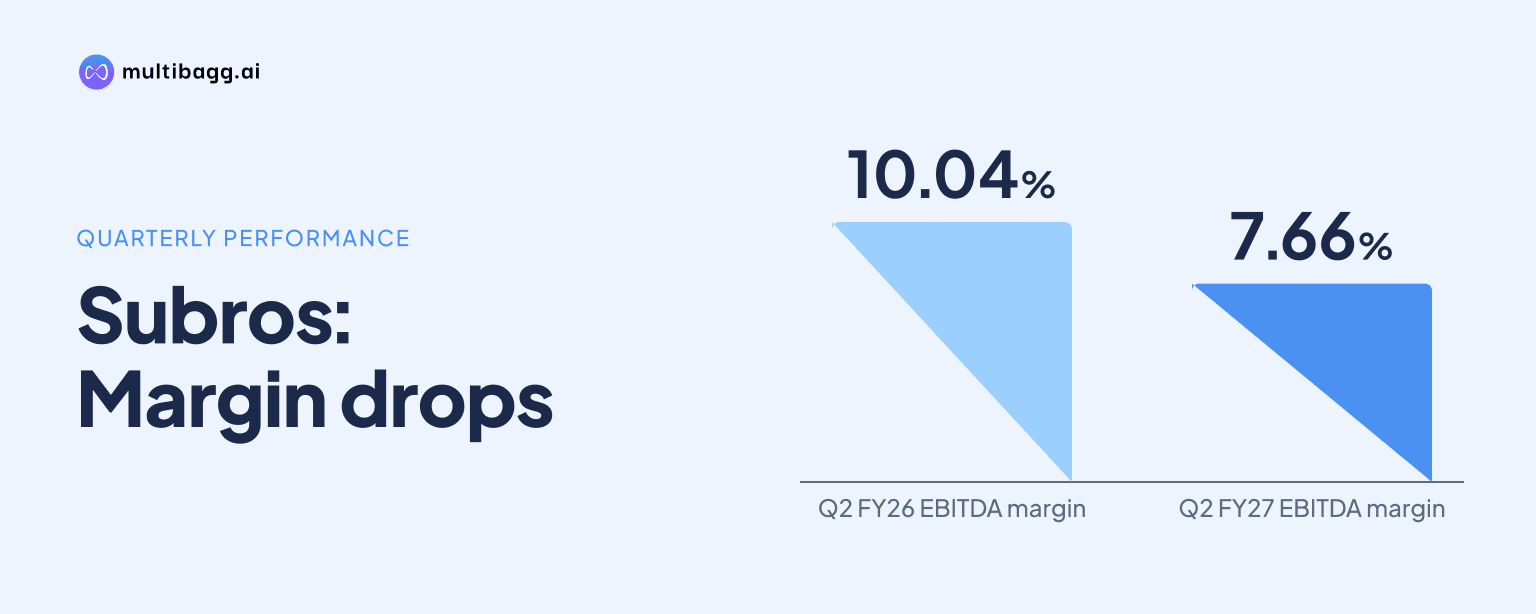
Subros recorded its highest quarterly revenue of Rs 1,198.90 crore in the second quarter of financial year 2026-27 (Q2 FY2026-27), up 36.27% year on year, but earnings before interest, tax, depreciation and amortisation (EBITDA) margin fell to 7.66% from 10.04% as material costs increased.
Know Subros inside out
Results, valuation, peers and who's buying, in one view.
How did Subros reach record Q2 revenue?
Subros reached record revenue from operations of Rs 1,198.90 crore in Q2 FY2026-27, compared with Rs 879.83 crore in Q2 FY2025-26 and Rs 1,032.11 crore in Q1 FY2026-27. Revenue increased by Rs 319.07 crore year on year and Rs 166.79 crore sequentially. Management attributed the increase to higher volumes, customer provisions for commodity prices, currency movements and minimum wages, and new-model start of production (SOP).
Net sales were Rs 1,193.74 crore in the quarter ended September 30, 2026, and other operating income was Rs 5.16 crore, taking net income from operations to Rs 1,198.90 crore. Subros said SOPs for two new internal-combustion-engine vehicle models began during Q2 FY2026-27. It also reported new business awards for future heating, ventilation and air-conditioning, compressor and heat-exchanger programmes, although it did not disclose their value.
The quarterly performance lifted first-half revenue from operations to Rs 2,231.01 crore in HY FY2026-27, up 26.90% from Rs 1,758.08 crore in HY FY2025-26. Q2 revenue exceeded Q1 revenue of Rs 1,032.11 crore, indicating that sales accelerated in the second quarter. The source attributes this growth to volume, customer provisions and new model launches rather than a separately disclosed segment contribution.
Why did Subros EBITDA margin fall to 7.66%?
Subros' EBITDA margin fell to 7.66% of net sales in Q2 FY2026-27, down 2.38 percentage points from 10.04% a year earlier and 0.81 percentage points from 8.47% in Q1 FY2026-27. EBITDA still increased 3.96% year on year to Rs 91.47 crore and 5.15% sequentially. Revenue therefore grew faster than EBITDA during the quarter.
Material cost was the principal disclosed factor behind the margin movement. Raw material consumed was Rs 914.07 crore in Q2 FY2026-27, equal to 76.57% of net sales, compared with Rs 640.64 crore, or 73.08%, in Q2 FY2025-26. The material-cost ratio also rose from 73.79% in Q1 FY2026-27. Management cited upward commodity and currency movements and a change in product mix.
Lower staff and other-expense ratios did not fully offset the increase in material cost. Staff cost declined to 8.48% of net sales from 10.39% a year earlier and 10.05% in Q1, while other expenses declined to 8.33% from 9.08% and 8.75%, respectively. For HY FY2026-27, material cost rose 2.84 percentage points year on year to 75.28%, while EBITDA margin declined 2.00 percentage points to 8.03%. Management said it remained focused on productivity, localisation, cost optimisation and operating leverage.
Got a follow-up? Ask IRIS
How did Subros profit change despite lower operating margins?
Subros reported profit before tax (PBT) of Rs 59.95 crore in Q2 FY2026-27, up 10.02% from Rs 54.49 crore a year earlier and 7.85% from Rs 55.59 crore in Q1 FY2026-27. Its PBT margin nevertheless declined to 5.02% of net sales from 6.22% in Q2 FY2025-26 and 5.41% in Q1. Depreciation was 2.44% of net sales, down from 3.58% a year earlier, while interest cost was 0.20%, down from 0.24%.
Profit after tax (PAT) was Rs 44.62 crore, up 9.93% year on year and 7.85% from Q1. PAT margin fell to 3.74% from 4.63% in Q2 FY2025-26 and 4.03% in Q1 FY2026-27. Tax as a proportion of PBT was broadly unchanged at 25.57%, compared with 25.51% a year earlier, indicating that the reduction in net-profit margin followed lower operating and PBT margins rather than a material tax-rate movement.
Other income was Rs 7.37 crore in Q2 FY2026-27, below Rs 19.51 crore in the comparable quarter. Subros said incentive income was Rs 0.64 crore, against Rs 13.40 crore in Q2 FY2025-26. In HY FY2026-27, other income was Rs 13.56 crore versus Rs 25.20 crore a year earlier, while first-half PAT increased 5.86% to Rs 86.02 crore and PAT margin declined to 3.87% from 4.64%.
What is Subros planning on costs and capacity?
Subros is progressing with the Kharkhoda greenfield plant and an expansion at Karsanpura for compressor capacity and electric-compressor expansion. Its stated Karsanpura plan includes localisation of electric compressors and new fixed-displacement compressor capacity, with a target SOP in 2027-28. The presentation does not disclose capital expenditure, capacity volumes or anticipated revenue from either project.
Management's operating plan includes hedging and aggressive localisation to mitigate foreign-exchange effects, internal efficiency improvements and expansion-led capacity additions. It also identified cost optimisation through improved operational efficiencies. These measures address the factors management cited for the Q2 increase in material cost to 76.57% of net sales, namely commodity prices, currency movements and product mix.
Subros also identified expansion in commercial-vehicle applications including buses, rail, trucks and tractors, alongside product expansion in electric and hybrid mobility applications. It said growth is aligned with industry growth across segments. Technology upgrades to meet regulatory changes, human-skill development, organisational measures and environmental, social and governance goals form part of the stated operational programme.
Conclusion
Subros combined its highest quarterly revenue of Rs 1,198.90 crore with slower operating-profit growth in Q2 FY2026-27. EBITDA rose to Rs 91.47 crore, but margin declined to 7.66% as the material-cost ratio increased 3.49 percentage points year on year to 76.57%, outweighing lower staff and other-expense ratios. PBT and PAT also increased in absolute terms, while their margins declined.
The next disclosed operating milestone is the targeted 2027-28 SOP for Karsanpura's localised electric-compressor and new fixed-displacement compressor capacity. Before then, the key disclosed issue is whether productivity, localisation, hedging and cost-optimisation measures can address the commodity, currency and product-mix factors that reduced first-half EBITDA margin to 8.03% from 10.03%.