










Tamboli Industries Limited Q2 PAT rises 76% as EBITDA margin hits 25%
Key highlights
- TCL reported Q2FY27 PAT of Rs 3.41 crore, up 76% year on year.
- Q2FY27 EBITDA rose 49% to Rs 6.00 crore and EBITDA margin reached 25%.
- H1FY27 total income was Rs 42.55 crore, up 14%, while PAT rose 71% to Rs 5.51 crore.
- TCL's new OEM programme has potential recurring annual revenue of more than Rs 20 crore after full transition.
powered by IRIS
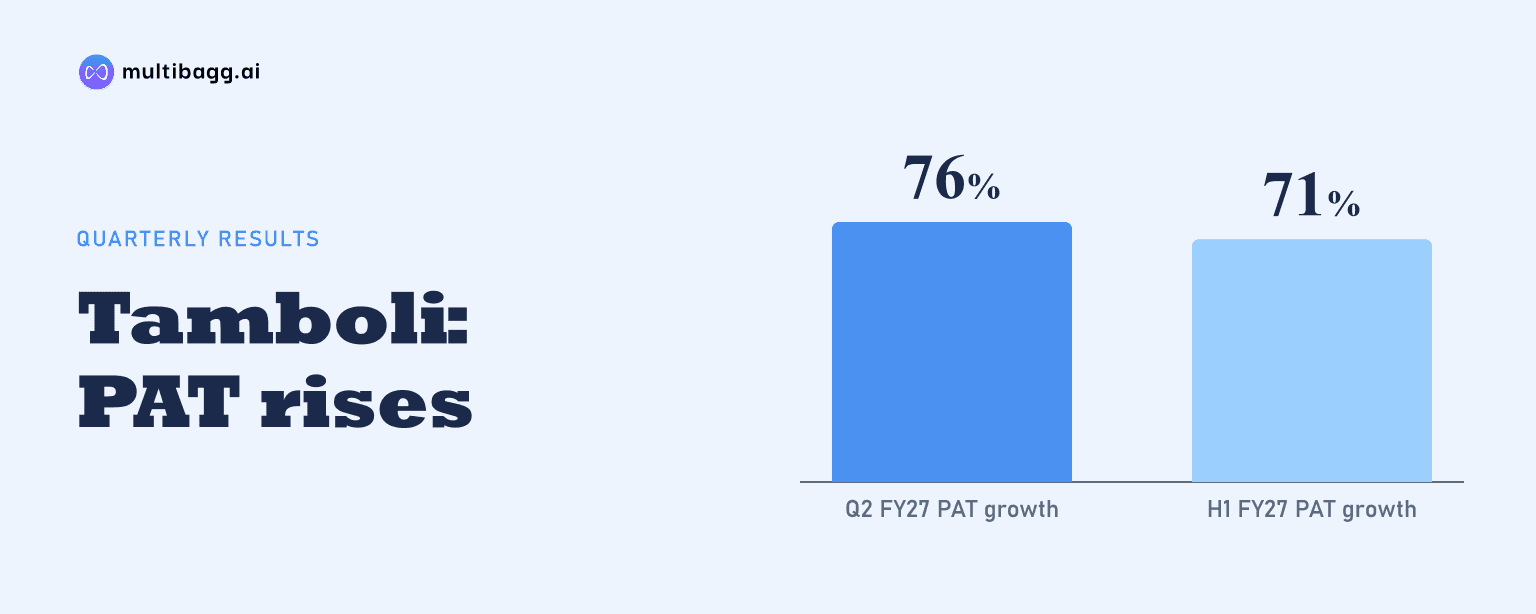
Tamboli Industries Limited reported Q2FY27 profit after tax of Rs 3.41 crore, up 76% year on year, while earnings before interest, tax, depreciation and amortisation margin reached 25% from 20% as total income increased 20% to Rs 23.87 crore and operating expenses rose 13%.
Know Tamboli Industries inside out
Results, valuation, peers and who's buying, in one view.
How did TCL perform in Q2FY27?
TCL increased Q2FY27 total income to Rs 23.87 crore, compared with Rs 19.88 crore in Q2FY26 and Rs 18.68 crore in Q1FY27. The year-on-year rise was 20%, while sequential income was higher by Rs 5.19 crore. Total operating expenses reached Rs 17.87 crore, up from Rs 15.86 crore a year earlier but below the pace of income growth.
TCL's operating profit, measured as earnings before interest, tax, depreciation and amortisation (EBITDA), rose 49% year on year to Rs 6.00 crore in Q2FY27 from Rs 4.02 crore in Q2FY26. EBITDA also increased from Rs 4.00 crore in Q1FY27. The difference between income growth of 20% and operating-expense growth of 13% corresponded with an increase of Rs 1.98 crore in EBITDA from the prior-year quarter.
Why did TCL's Q2FY27 margin increase?
TCL's EBITDA margin increased to 25% in Q2FY27, from 20% in Q2FY26 and 21% in Q1FY27. The company reported the year-on-year expansion as 492 basis points, with one basis point equal to one-hundredth of a percentage point. This margin movement coincided with total income rising by Rs 3.99 crore year on year while total operating expenses increased by Rs 2.01 crore.
Profit after tax (PAT) margin also improved to 14% in Q2FY27, compared with 10% in Q2FY26 and 11% in Q1FY27. PAT increased by Rs 1.47 crore year on year to Rs 3.41 crore. Profit before taxes rose 66% to Rs 4.73 crore from Rs 2.84 crore, while interest cost rose 10% to Rs 14 lakh from Rs 12 lakh and depreciation and amortisation increased 8% to Rs 1.14 crore.
The quarterly figures show that operating expenses represented a smaller share of income than in the comparable quarter. TCL reported Rs 17.87 crore of operating expenses against Rs 23.87 crore of income in Q2FY27, producing Rs 6.00 crore of EBITDA. In Q2FY26, Rs 15.86 crore of expenses against Rs 19.88 crore of income produced Rs 4.02 crore of EBITDA.
What do TCL's first-half FY27 results show?
TCL reported H1FY27 total income of Rs 42.55 crore, up 14% from Rs 37.35 crore in H1FY26. EBITDA rose 43% to Rs 10.00 crore from Rs 6.99 crore, outpacing income growth by 29 percentage points. The H1FY27 EBITDA margin was 24%, compared with 19% in H1FY26, an expansion reported as 481 basis points.
H1FY27 PAT increased 71% to Rs 5.51 crore from Rs 3.21 crore in H1FY26, lifting PAT margin to 13% from 9%. Profit before taxes rose 66% to Rs 7.55 crore from Rs 4.55 crore. Earnings per share increased to Rs 5.55 in H1FY27 from Rs 3.24 in H1FY26, while Q2FY27 earnings per share were Rs 3.44 versus Rs 1.95 a year earlier.
The first-half expense trend moved in the same direction as the quarterly comparison. Total operating expenses increased 7% to Rs 32.55 crore in H1FY27 from Rs 30.36 crore, compared with the 14% increase in total income. Interest cost declined 17% to Rs 21 lakh from Rs 25 lakh, while depreciation and amortisation rose 2% to Rs 2.25 crore from Rs 2.19 crore.
Got a follow-up? Ask IRIS
What business development could support TCL's future revenue?
TCL has secured a component-development and long-term supply programme from a Fortune 100 global original equipment manufacturer (OEM), with potential recurring annual revenue of more than Rs 20 crore upon full transition. The programme covers more than 50 precision-engineered components and follows more than three years of engagement and a competitive evaluation of precision-component manufacturers from emerging markets.
Initial development orders have already been received, according to TCL, with subsequent orders expected in successive phases over coming months. The programme is expected to move through development, customer approvals and commercial production over two to three years. TCL states that the full revenue potential remains subject to customer approvals, the pace of business transition and customer requirements.
TCL says it is optimistic about FY27 and FY28, citing demand traction from key European accounts, large projects in the United States and medium-sized projects in India. The company operates across five industry verticals, with FY26 revenue mix comprising Pneumatics and Automation at 30%, Pumps and Valves at 30%, Automotive at 20%, General Engineering at 18% and Aerospace at 2%.
How is TCL preparing for additional demand?
TCL is strengthening its machining facility and adding computer numerical control (CNC) machining capacity as new opportunities ramp up. Management says scale is central to its business model and expects operating leverage to support margin outcomes as revenue builds. It also anticipates reaching optimum capacity utilisation by FY28, rather than disclosing a specific capacity-utilisation percentage for FY27.
The company describes itself as an export-focused advanced investment-casting producer with 600 tonnes per annum of production capacity and a team of more than 500. It supplies customers in more than 27 countries and says 50% of its proposed global coverage is Europe, followed by India at 25% and the United States at 20%. These geographic proportions provide context for management's stated demand traction in Europe and project pipeline in the United States and India.
TCL's Q2FY27 performance occurred alongside the new OEM programme, but the presentation does not quantify any Q2FY27 revenue contribution from that programme. Its stated annual potential of more than Rs 20 crore applies only after the full component portfolio transitions over the disclosed two-to-three-year timeline. The immediate disclosed milestone is receipt of initial development orders rather than completion of commercial production.
Conclusion
TCL's Q2FY27 results show profit growing faster than income: PAT rose 76% to Rs 3.41 crore against a 20% increase in total income to Rs 23.87 crore. EBITDA rose 49% to Rs 6.00 crore, and the margin moved to 25% from 20%, while operating expenses increased 13%. The H1FY27 pattern was similar, with EBITDA up 43% and PAT up 71%.
Next, investors can watch the phased development, approval and commercial-production process for the more than 50-component Fortune 100 OEM programme, which TCL says could generate more than Rs 20 crore in recurring annual revenue after full transition in two to three years. Management also plans additional CNC machining capacity and expects optimum capacity utilisation by FY28.