










Tega says Molycop deal costs tapered sharply by Q2 FY27
Key highlights
- Tega reported an H1 FY27 loss after tax of Rs 167 crore, while adjusted profit after tax was Rs 45.2 crore.
- Molycop transaction costs fell from Rs 191 crore in Q1 FY27 to Rs 66.6 crore in Q2 FY27.
- Tega's legacy business grew H1 FY27 revenue 20% to Rs 914.3 crore and EBITDA 25% to Rs 194.9 crore.
- Tega had net debt of about Rs 10,461.2 crore at September 30, 2026.
powered by IRIS
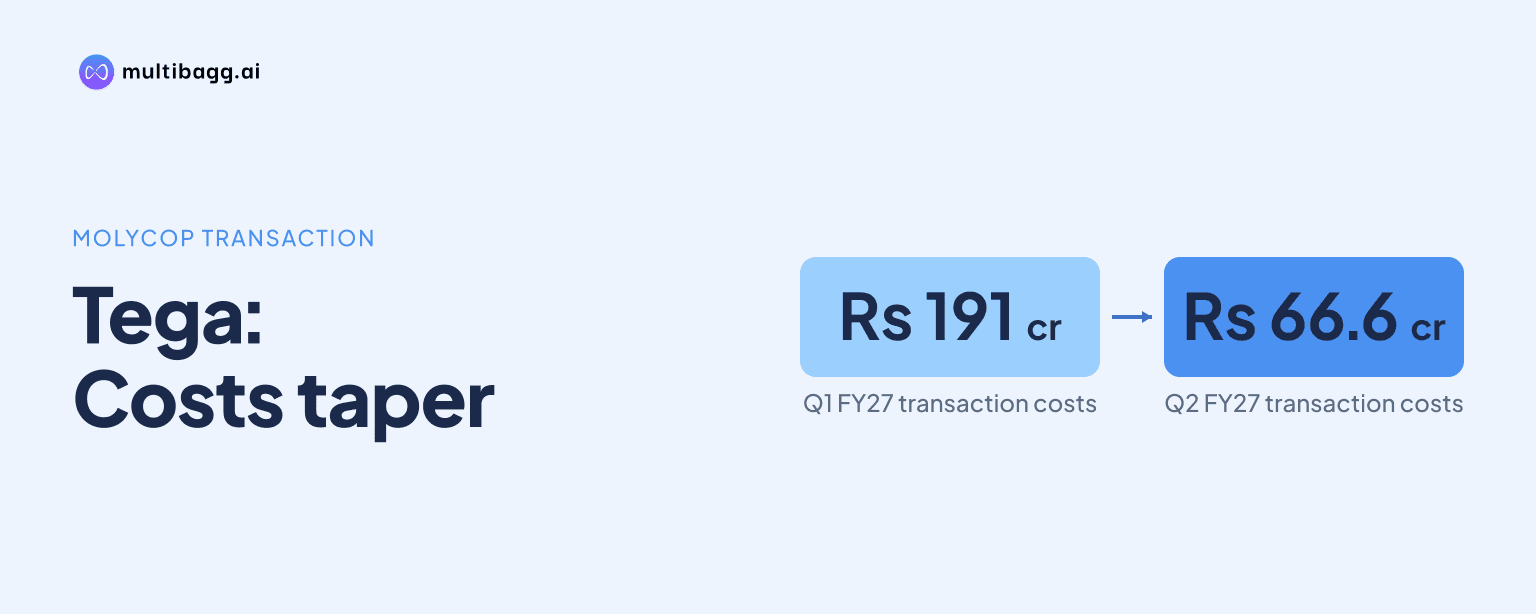
In H1 FY27, Tega Industries Limited recorded Rs 257.6 crore of Molycop acquisition transaction costs, helping produce a reported Rs 167 crore loss after tax even as adjusted profit after tax was Rs 45.2 crore; Tega said those costs fell to Rs 66.6 crore in Q2.
Know Tega Industries inside out
Results, valuation, peers and who's buying, in one view.
How did acquisition costs affect Tega's H1 FY27 earnings?
Tega's reported H1 FY27 loss reflected acquisition-related charges rather than its adjusted profit measure. The group reported a Rs 167 crore loss after tax for the half year, while adjusted profit after tax was Rs 45.2 crore after excluding one-time items. The largest disclosed item was Rs 257.6 crore of Molycop transaction costs, which Tega said were expensed as required under Indian Accounting Standards, or Ind AS.
Molycop was consolidated from June 1, 2026, so H1 FY27 included four months of its operations and associated acquisition accounting. Tega also recorded a Rs 11.7 crore inventory step-up charge under the purchase-price allocation. Management described the inventory charge as one-time and non-cash, separating it from operating expenses incurred in the ordinary course of the business.
The disclosed figures are not a complete arithmetic bridge from reported to adjusted profit because Tega did not provide a full adjustment reconciliation during the call. Finance cost was Rs 408.6 crore in H1 FY27 and included a dividend on redeemable preference shares at Molycop under Ind AS. Management also said the Rs 123.5 crore tax expense was expected to normalise over coming quarters.
Why may Tega's Q3 FY27 earnings be easier to assess?
Tega said Q3 FY27 earnings may carry a lower acquisition-cost burden because the bulk of transaction costs was behind it by the end of H1 FY27. The chief financial officer said transaction costs declined from Rs 191 crore in Q1 FY27 to Rs 66.6 crore in Q2 FY27, a reduction during the first full quarter of Molycop consolidation.
This reduction makes the December quarter more useful for assessing ongoing operations, although Tega did not provide Q3 revenue, margin or profit-after-tax guidance. Management said costs had tapered quickly, not that all acquisition-related accounting effects had ended. The purchase-price allocation, including Rs 3,471.8 crore of identifiable intangible assets and Rs 5,057.1 crore of goodwill, remains provisional within the 12-month measurement period permitted under Ind AS 103.
Finance and tax items also remain relevant to any comparison with H1. Management said it expects the effective tax rate to normalise over coming quarters, while H1 finance cost reflected the post-acquisition capital structure. Lower transaction expenses therefore remove a major H1 distortion, but they do not establish a specific Q3 profit outcome.
Got a follow-up? Ask IRIS
What did Tega's operating businesses deliver in H1 FY27?
Tega's legacy consumables and equipment business increased H1 FY27 revenue by 20% to Rs 914.3 crore from Rs 761.4 crore in H1 FY26. Earnings before interest, tax, depreciation and amortisation, or EBITDA, rose 25% to Rs 194.9 crore from Rs 156.1 crore. The EBITDA margin increased by 70 basis points to 20.4% from 19.7%.
Consumables were the main contributor to legacy growth, with H1 FY27 revenue increasing 30% to Rs 811.7 crore from Rs 626.4 crore. Consumables EBITDA rose 42% to Rs 191.6 crore from Rs 134.6 crore, and its margin expanded by 190 basis points to 22.4%. Tega said legacy gross margin improved to 61% from 59%, supported by product mix and pricing discipline.
Equipment revenue was Rs 97.3 crore in H1 FY27, reflecting the timing of project execution, but the business recovered during Q2. Q2 equipment revenue rose 72% sequentially to Rs 61.5 crore from Rs 35.8 crore in Q1 and returned to positive EBITDA. Legacy Q2 revenue reached Rs 482.5 crore, up 19% year on year and 11% sequentially.
Molycop generated Q2 FY27 revenue of Rs 3,771.6 crore and EBITDA of Rs 514.4 crore, equivalent to a 14% EBITDA margin. That business accounted for most of Tega's consolidated Q2 revenue of Rs 4,254 crore and EBITDA before one-time expenses of Rs 608.1 crore. For the four months from June through September, Molycop reported revenue of Rs 5,063.2 crore and EBITDA of Rs 677.2 crore.
What balance-sheet effects remain after the Molycop acquisition?
Tega's acquisition increased both its operating scale and its balance-sheet obligations. Total assets stood at Rs 22,706.6 crore on September 30, 2026, compared with Rs 4,314.5 crore in March 2026. Molycop added about Rs 20,404.2 crore of assets and Rs 16,789.5 crore of liabilities, while purchase consideration was Rs 4,242.2 crore.
Gross borrowings were Rs 11,492.3 crore at September 30, 2026, of which Rs 11,034.6 crore, or almost 96%, was long term. Cash, bank balances and liquid investments were about Rs 1,031.1 crore, resulting in net debt of about Rs 10,461.2 crore. In October, after the reporting date, Tega prepaid Rs 100 crore of term loans using proceeds from a preferential issue.
Management said deleveraging was its top financial priority and identified operating cash flow, working-capital efficiencies and integration synergies as the mechanisms for reducing leverage. Group net trade working capital was Rs 3,323.6 crore, or about 71 days when Q2 revenue is annualised. Tega said legacy trade receivables fell almost 15% since March despite higher sales volumes.
Molycop's working capital at September 30 was higher than in the previous quarter because of the timing of bar purchases, according to management. Tega also said capital expenditure would remain disciplined and focused on maintenance and high-return projects. These measures sit alongside the group’s effort to release inventory across the combined business.
Conclusion
Tega's H1 FY27 loss should be considered alongside Rs 257.6 crore of Molycop transaction costs and a Rs 11.7 crore non-cash inventory step-up charge. The legacy business increased revenue and EBITDA from H1 FY26, while Molycop contributed Rs 3,771.6 crore of Q2 revenue and Rs 514.4 crore of Q2 EBITDA, materially expanding the group’s scale.
The next result to watch is Q3 FY27, when the lower transaction-cost run rate may make underlying earnings easier to compare. Management plans to deleverage through internal accruals and working-capital releases while pursuing cross-selling, including a 500-ton Molycop grinding-media trial that it said could create annualised supply potential of more than 30,000 tons.