










Triveni Turbine targets $80-90m South African refurbishment
Key highlights
- Triveni Turbine estimates $80 million to $90 million of South African gas-turbine refurbishment potential over four to five years.
- Triveni Turbine's aftermarket closing order book grew 105.4% year on year to Rs 639 crore in Q2 FY27.
- Export orders made up 59.2% of Triveni Turbine's Rs 2,453 crore closing order book, versus 50% a year earlier.
- Triveni Turbine's Q2 FY27 order booking rose 17.2% year on year to Rs 764 crore.
powered by IRIS
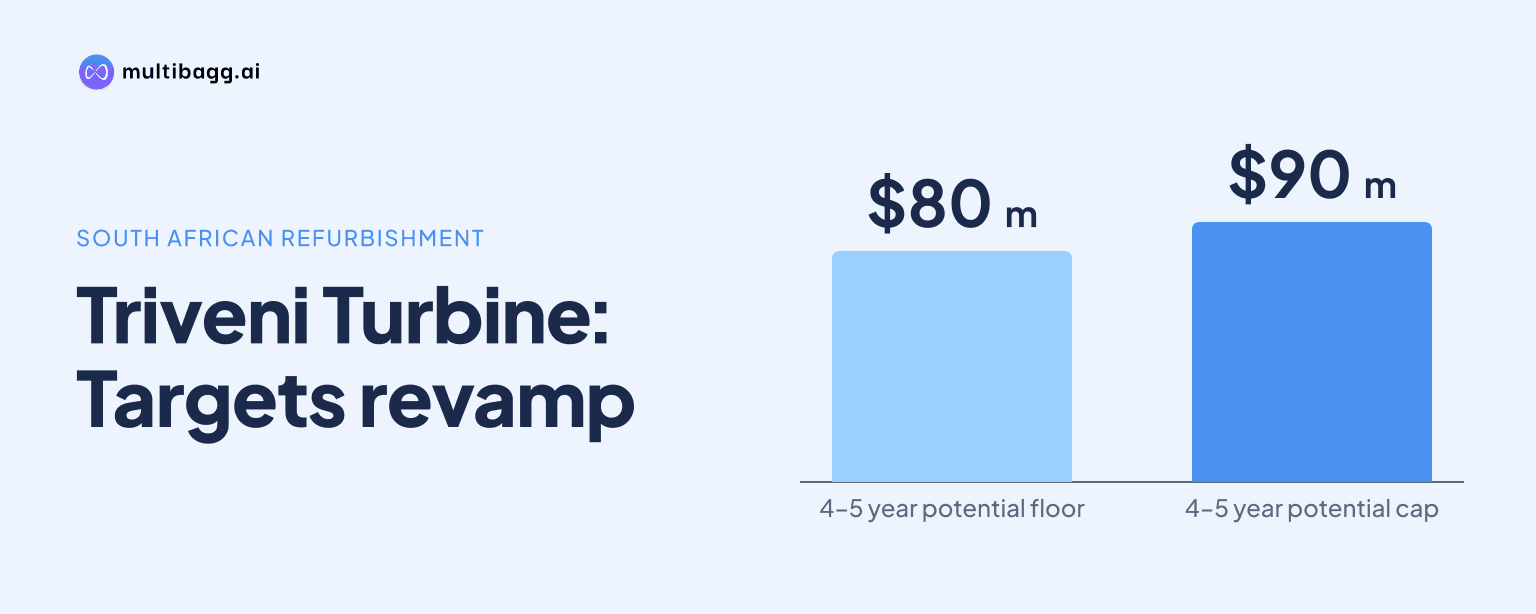
On its November 12, 2026 Q2 FY27 earnings call, Triveni Turbine Limited said its South African gas-turbine refurbishment work has a total potential market of $80 million to $90 million over four to five years, with billings dependent on overhaul assessments and annual executable scope.
Know Triveni Turbine inside out
Results, valuation, peers and who's buying, in one view.
What is Triveni Turbine's South African gas-turbine opportunity?
Triveni Turbine's opportunity is a long-term gas-turbine refurbishment contract in the Southern African Development Community, or SADC, region through its South African subsidiary. Management said the customer is one of the region's largest utility providers, and the scope covers parts upgrades, replacement, manufacturing, supply and installation.
The work will be undertaken with a European partner that is to provide components, technology, knowledge and intellectual property. Triveni Turbine said the contract creates a route into gas-turbine services and parts, while its existing turbine product business remains focused on steam turbines.
The South African initiative does not mean Triveni Turbine is making gas turbines for power generation. Management said its separate small gas-turbine development is intended for thrust applications and represents a multi-year product-development cycle; it identified services as the nearer-term opportunity.
What does the $80-90 million opportunity represent?
The $80 million to $90 million figure is the total potential market from the South African refurbishment contract over four to five years, not a confirmed single-period order value. Management said actual requirements will be established once overhauls are completed and the equipment's condition is assessed.
Triveni Turbine said it will recognise only the work billable in a particular financial year. This means potential value could translate into revenue in stages, based on authorised parts supply, manufacturing and installation rather than being recognised when the total opportunity is identified.
The potential is separate from Q2 FY27 order booking of Rs 764 crore, which was 17.2% above Rs 652 crore in Q2 FY26. Export order booking grew more than 49% and represented 48% of quarterly bookings, while product order booking increased 32.5% to Rs 601 crore.
For H1 FY27, Triveni Turbine recorded total order booking of Rs 1,333 crore, up 12.2% year on year. Export orders rose 51.6% to Rs 752 crore and formed 56% of H1 booking, compared with 42% in the prior-year half, but management did not quantify how much of the South African potential has become firm purchase orders.
Got a follow-up? Ask IRIS
How does the South African work fit Triveni Turbine's order book?
The South African work fits Triveni Turbine's expanding aftermarket order book, which management said grew 105.4% year on year to Rs 639 crore at the end of Q2 FY27. The aftermarket represented 26% of the Rs 2,453 crore closing order book, compared with 14% a year earlier.
Management attributed aftermarket order-book growth to wins across thermal, renewable, combined-cycle, utility, geothermal and other value-added service segments. The gas-turbine contract adds a parts-and-services category to that mix, though management did not identify its booked value within the Rs 639 crore aftermarket balance.
The total closing order book was 10.5% above the year-earlier level, while export orders within it rose 29.3% and reached 59.2% of the balance, up from 50%. This contrasts with Q2 FY27 revenue, where exports accounted for 30% of Rs 491 crore revenue from operations, against 55% in Q2 FY26.
That difference between the order book and reported revenue reflects execution timing. In Q2 FY27, aftermarket revenue fell 16.7% to Rs 148 crore despite the larger aftermarket order book, while management said export dispatches deferred by freight issues, mainly for Middle East customers, were expected in Q3 and Q4 FY27.
What could determine Triveni Turbine's near-term financial impact?
Overhaul assessments and the utility's resulting replacement requirements will determine the timing and scale of South African work. Triveni Turbine said the European partner will support the contract with components and technology, while its own scope includes supply, manufacturing and installation.
Management said the first contract could allow Triveni Turbine to provide similar services in other regions, but it must first establish how the South African arrangement is leveraged. The company did not offer a timeline for expansion beyond the four-to-five-year potential period or disclose a separate annual revenue target for this business.
For the wider business, management expects exports and aftermarket to contribute more of H2 FY27 revenue than in H1. Q2 FY27 earnings before interest, tax, depreciation and amortisation, or EBITDA, were Rs 85.8 crore at a 17.5% margin, compared with a 26.3% margin in Q2 FY26, as domestic revenue rose 51.8% to Rs 340 crore while export revenue declined 46.6% to Rs 151 crore.
A separate NTPC order is expected to be commissioned in Q4 FY27, with about 15% of its order value left to bill equally across Q3 and Q4, according to management. Management said it had already accounted conservatively for a marginal loss on that order and expects higher export and aftermarket billing to limit its effect on margins.
Conclusion
Triveni Turbine is extending its services portfolio through a South African gas-turbine refurbishment contract with an estimated $80 million to $90 million potential market over four to five years. The opportunity is conditional on overhaul findings, but it arrives as the company's aftermarket order book reached Rs 639 crore and accounted for 26% of its Rs 2,453 crore closing order book in Q2 FY27.
The next items to watch are the overhaul assessments that define billable scope, the conversion of potential work into orders and the pace of execution in Q3 and Q4 FY27. Management expects deferred export shipments to be delivered in those quarters and expects the NTPC order to be commissioned in Q4 FY27, with its remaining 15% billing spread across the second half.