










Updater Services Limited Q2 PAT rises 62% as margin expands
Key highlights
- UDS reported Q2 FY27 PAT of Rs 32.13 crore, up 62% year on year from Rs 19.80 crore.
- Q2 FY27 revenue from operations increased 11% to Rs 812.24 crore, while EBITDA rose 37% to Rs 43.15 crore.
- BSS EBITDA margin expanded 240 basis points to 7.7%, with EBITDA increasing to Rs 20.60 crore.
- IFM delivered record quarterly revenue of Rs 559.7 crore and increased its EBITDA margin to 4.2%.
powered by IRIS
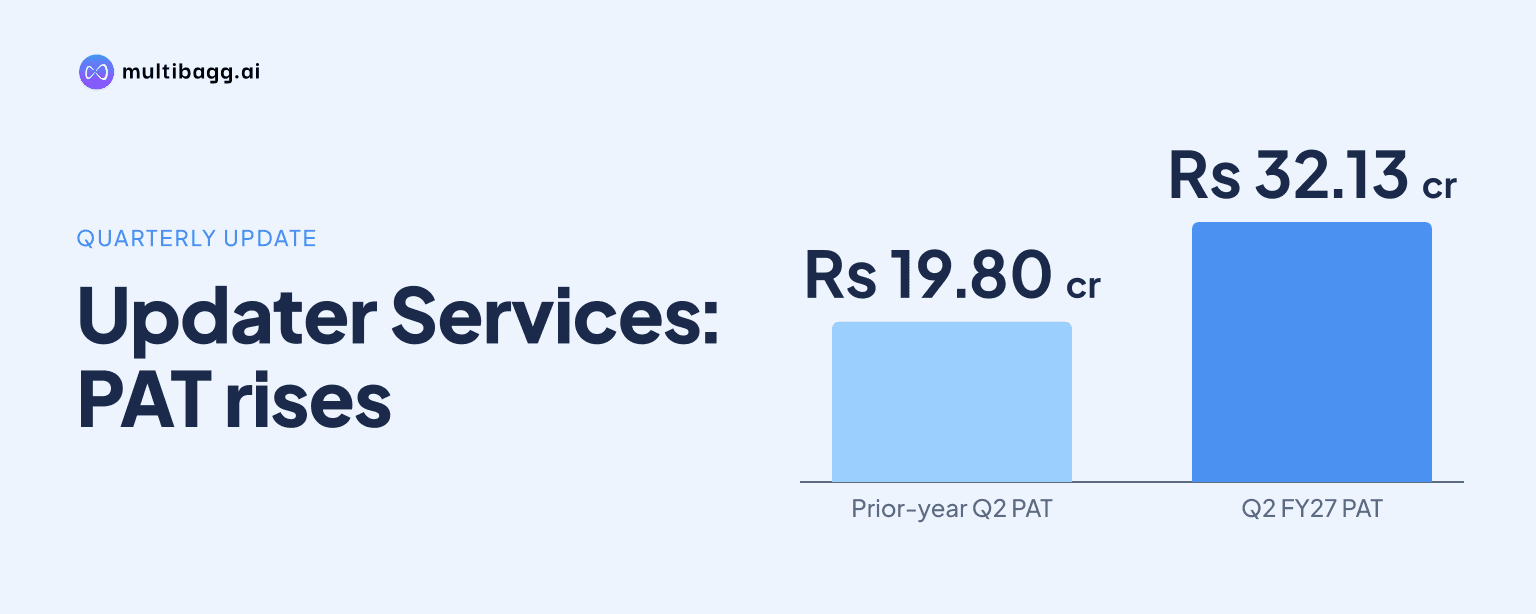
Updater Services Limited reported Q2 FY27 profit after tax (PAT) of Rs 32.13 crore, 62% above Q2 FY26, while revenue from operations increased 11% to Rs 812.24 crore. The result followed a rise in consolidated EBITDA margin to 5.3%, with Business Support Services (BSS) margin reaching 7.7% and Integrated Facilities Management (IFM) margin at 4.2%.
Know Updater Services inside out
Results, valuation, peers and who's buying, in one view.
How did UDS perform in Q2 FY27?
UDS increased Q2 FY27 revenue from operations to Rs 812.24 crore from Rs 729.34 crore in Q2 FY26, an 11% increase. Earnings before interest, tax, depreciation and amortisation (EBITDA) rose 37% to Rs 43.15 crore from Rs 31.56 crore, lifting the consolidated EBITDA margin by 100 basis points to 5.3% from 4.3%.
PAT increased to Rs 32.13 crore from Rs 19.80 crore, raising the PAT margin to 4.0% from 2.7%. Profit before tax grew 47% to Rs 34.70 crore, while finance cost declined to Rs 1.10 crore from Rs 1.59 crore and tax expense fell to Rs 2.57 crore from Rs 3.77 crore. Basic earnings per share increased to Rs 4.82 from Rs 2.96.
The difference between revenue and profit growth coincided with EBITDA rising by Rs 11.59 crore on an Rs 82.90 crore increase in revenue, as the consolidated EBITDA margin moved up by 100 basis points. UDS also reported other income of Rs 4.86 crore, below Rs 5.53 crore in Q2 FY26, meaning the reported profit increase occurred despite lower other income.
Which UDS division drove the Q2 margin increase?
BSS drove the larger Q2 margin movement, with EBITDA rising to Rs 20.60 crore from Rs 12.70 crore and margin increasing to 7.7% from 5.3%. BSS revenue rose 11% to Rs 267.2 crore from Rs 239.8 crore, while its share of total sales remained 32% in both Q2 FY26 and Q2 FY27.
IFM revenue also rose 11%, reaching Rs 559.7 crore from Rs 502.8 crore, and its EBITDA increased to Rs 23.7 crore from Rs 19.1 crore. IFM margin improved by 40 basis points to 4.2%, compared with BSS’s 240-basis-point increase. IFM remained the larger division, accounting for 68% of Q2 sales in both periods.
UDS recorded an EBITDA elimination of negative Rs 1.2 crore in Q2 FY27, compared with negative Rs 0.2 crore a year earlier. Combined segment EBITDA was therefore Rs 44.3 crore, above reported consolidated EBITDA of Rs 43.15 crore. BSS added Rs 7.9 crore of year-on-year EBITDA, exceeding IFM’s Rs 4.6 crore increase.
Got a follow-up? Ask IRIS
What explains the BSS and IFM operating trends?
Management said Denave’s demand-generation business turned around in Q2, helped by higher outcome-linked income from artificial intelligence-led delivery through Intellibank, its sales-intelligence platform. Management also said Athena performed in line with internal plans, had zero client attrition, won two new clients and started generating revenue from agentic artificial intelligence deployments.
Sales-enablement services represented 74.3% of BSS revenue as of H1 FY27, followed by audit and assurances at 7.3%, warehouse management and niche logistics solutions at 6.7%, airport ground handling services at 5.6%, employee background verification services at 5.0%, and technology services at 1.1%. The top 10 BSS customers contributed 76.5% of revenue, compared with 29.6% for IFM’s top 10 customers.
Management described IFM’s Rs 559.7 crore Q2 FY27 revenue as its highest-ever quarterly revenue. It attributed growth to 11 new logos in the first half (H1) of FY27, strategic contract ramp-ups and a higher share of spend from existing accounts. As of H1 FY27, industrial customers accounted for 20.1% of IFM revenue, followed by manufacturing and engineering services at 12.2%, banking, financial services and insurance at 11.0%, and education at 8.0%.
What do UDS's half-year results and balance sheet show?
UDS reported H1 FY27 revenue from operations of Rs 1,576.53 crore, up 10% from Rs 1,429.59 crore in H1 FY26. EBITDA increased 21% to Rs 85.47 crore from Rs 70.87 crore, lifting margin to 5.4% from 5.0%, while PAT rose 28% to Rs 62.41 crore from Rs 48.79 crore and PAT margin reached 4.0% from 3.4%.
The H1 segment comparison again showed the larger margin change in BSS. BSS EBITDA increased to Rs 39.5 crore from Rs 28.9 crore and its margin rose to 7.5% from 6.0%; IFM EBITDA increased to Rs 47.3 crore from Rs 42.1 crore while its margin remained 4.3%. IFM revenue grew 11% to Rs 1,084.3 crore, compared with 9% BSS revenue growth to Rs 519.9 crore.
As of September 2026, total equity was Rs 1,110.63 crore, up from Rs 1,055.82 crore in March 2026, while total assets increased to Rs 1,764.39 crore from Rs 1,639.83 crore. Cash and cash equivalents were Rs 158.96 crore, down from Rs 208.53 crore at March 2026, while cash and cash equivalents including mutual funds and fixed deposits were Rs 403.97 crore, compared with Rs 277.08 crore in September 2025.
Conclusion
UDS’s Q2 FY27 results showed PAT growing faster than revenue, with profit increasing 62% to Rs 32.13 crore against 11% revenue growth to Rs 812.24 crore. The key operating change was the BSS margin increase to 7.7%, while IFM generated record quarterly revenue of Rs 559.7 crore and raised its margin to 4.2%.
The next measure to watch is whether the H1 FY27 consolidated EBITDA margin of 5.4% can improve as management seeks to rationalise employee costs through artificial intelligence and automation. Management also identified Denave’s outcome-linked income, Athena’s two client wins and agentic deployments, and IFM contract ramp-ups as factors behind the Rs 1,576.53 crore H1 FY27 revenue base.