










Visdem expects stronger H2 after H1 revenue rises 23% in FY27
Key highlights
- Visdem's H1 FY27 revenue rose 23% to Rs 67.14 crore from Rs 54.64 crore in H1 FY26.
- H1 FY27 EBITDA increased to Rs 9.09 crore, but EBITDA margin declined to 13.55% from 14.73%.
- Management expects Rs 80-85 crore of H2 FY27 revenue to reach about Rs 150-155 crore for the full year.
- Visdem reported sales of Rs 81.58 crore through October 2026, versus Rs 63.24 crore through October 2025.
powered by IRIS
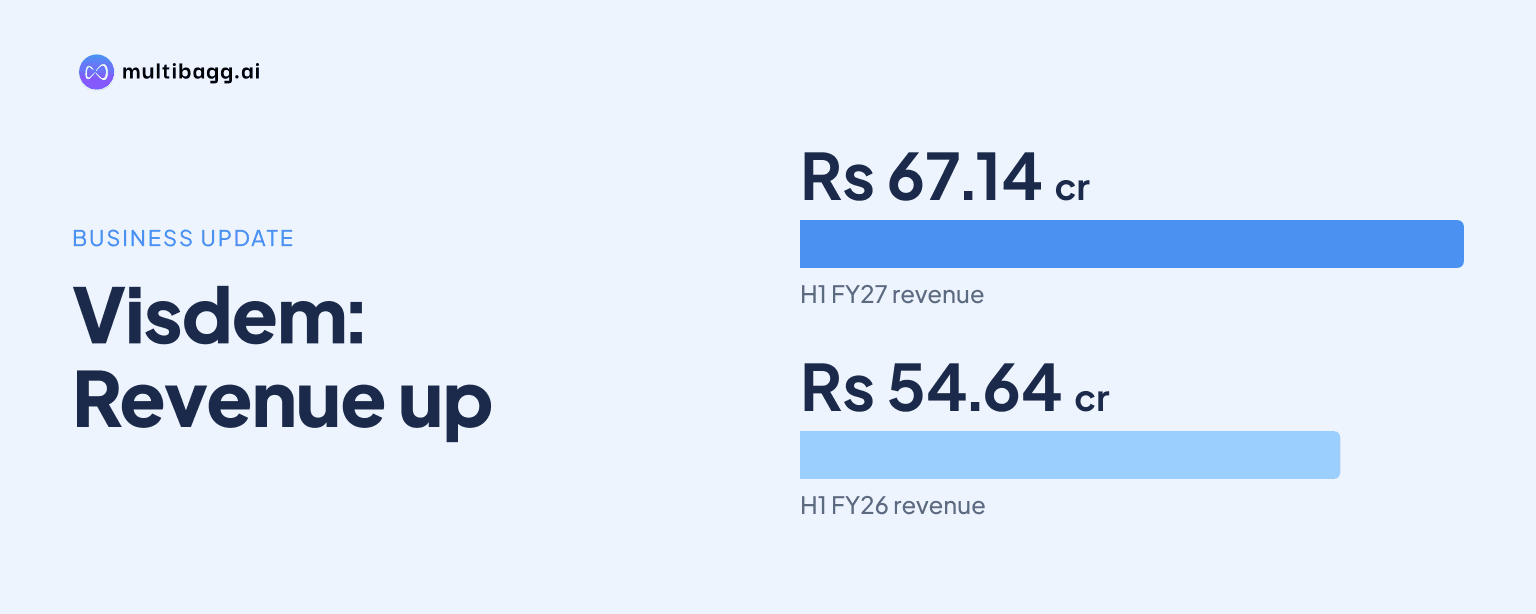
Visdem Technosys Limited expects Rs 80-85 crore of revenue in H2 FY27 after reporting Rs 67.14 crore in H1 FY27, up 23% from Rs 54.64 crore a year earlier. Management said its Q3 order book supports a stronger second half, while H1 EBITDA margin declined to 13.55% from 14.73%.
Know Visdem Technosys inside out
Results, valuation, peers and who's buying, in one view.
What did Visdem report for H1 FY27?
Visdem reported H1 FY27 revenue of Rs 67.14 crore for the half year ended September 30, 2026, compared with Rs 54.64 crore in H1 FY26. The Rs 12.50 crore increase represented 23% growth, according to Chief Financial Officer Tejal Dias, and reflected progress in the company’s flexible linear LED lighting and electronic power-supply operations.
Earnings increased in absolute terms, although they rose more slowly than revenue. EBITDA, or earnings before interest, tax, depreciation and amortisation, was Rs 9.09 crore in H1 FY27, against Rs 8 crore in H1 FY26, an increase of 13.06%. Profit before tax rose to Rs 6.54 crore from Rs 6.02 crore, while profit after tax increased to Rs 4.90 crore from Rs 4.51 crore.
Visdem also reported sales of Rs 81.58 crore through October 2026, compared with Rs 63.24 crore through October 2025. This update covers a later point than the September-ended H1 results and indicates that reported sales had moved beyond the Rs 67.14 crore recorded for H1 FY27.
Why did Visdem's H1 FY27 margins decline?
Visdem’s EBITDA margin was 13.55% in H1 FY27, down 1.18 percentage points from 14.73% in H1 FY26, despite EBITDA increasing by Rs 1.09 crore. The difference between 23% revenue growth and 13.06% EBITDA growth meant operating profit did not keep pace with sales during the September-ended half year.
Gross margin fell to 37.70% in H1 FY27 from 41.89% in FY26, a decline of 4.19 percentage points as presented by management. Profit before tax margin declined to 9.73% from 11.03%, and profit after tax margin fell to 7.33% from 8.26%, even as post-tax profit rose by Rs 39 lakh year on year.
Management did not quantify the separate effects of costs or product mix on the margin movement. Dias said Visdem was monitoring its cost structure, product mix and operating efficiency, with a continuing focus on improving profitability while maintaining growth. That leaves H2 margin performance dependent on how these factors develop alongside the planned Rs 80-85 crore revenue contribution.
How does Visdem expect to reach its FY27 revenue plan?
Visdem management said it was targeting roughly Rs 150-155 crore of revenue in FY27, implying about 50% growth over the prior year. With Rs 67.14 crore reported in H1 FY27, management said the remaining requirement was Rs 80-85 crore in H2 FY27, making the second half larger than the first by about Rs 13-18 crore.
The company said its Q3 order book looked “pretty strong” and gave it visibility that Q3 and Q4 performance would be comparatively better than Q1 and Q2. This is management’s outlook rather than reported revenue: the call did not disclose the value of the order book, a quarterly revenue target, or a specific H2 profitability forecast.
Management also said it anticipated better H2 numbers than the Rs 67.14 crore revenue and approximately 13.5% EBITDA margin recorded in H1 FY27. The comment establishes an expectation of improved second-half performance, but Visdem did not state whether the expected improvement referred to revenue alone, EBITDA margin alone, or both measures.
Got a follow-up? Ask IRIS
Which segments support Visdem's second-half and longer-term plan?
Visdem said about 90% of its present business comes from retail or household applications, principally its established flexible linear lighting business. Management is seeking additional revenue from furniture, facade, underwater, automobile and festive-lighting applications, as well as electronic power supplies, which it described as relatively small within the present product mix.
For H1 FY27, management said it created opportunities in festive lighting, added clients in furniture lighting, international markets, facade lighting and electronic power supplies, and expected festive-lighting activity to fructify in H2. These disclosures identify the product and customer-development mechanisms behind the H2 outlook, but the company did not provide revenue earned from any one of these new segments.
Looking beyond FY27, management said each application category could potentially become similar in size to the generic-lighting business. During the call, the chairman initially referred to Rs 400-450 crore by 2030, then clarified that Visdem’s target being worked toward was Rs 500 crore. He cited furniture lighting as a potential Rs 100 crore revenue category over the next three to four years, based on discussions with Hettich and other prospective customers.
Management said Visdem has global approvals from Hettich’s Germany head office and is Hettich’s only flexible linear lighting vendor in India. It also said that, among existing clients, it generally has 80% to 100% wallet share in the flexible linear lighting category. Those comments relate to management’s customer strategy and do not establish a contracted revenue amount for FY27 or subsequent periods.
Conclusion
Visdem’s H1 FY27 results show revenue rising faster than operating and net profit: sales increased 23% to Rs 67.14 crore, while EBITDA rose 13.06% to Rs 9.09 crore and EBITDA margin declined to 13.55%. The company’s FY27 revenue target of Rs 150-155 crore therefore requires a materially larger H2, supported by management’s stated Q3 order-book visibility and new application segments.
The next point to watch is whether Q3 delivers the stronger performance management expects and advances the Rs 80-85 crore H2 revenue requirement. Investors can also track whether Visdem’s cost structure, product mix and operating-efficiency measures address the H1 margin declines, while furniture, festive, facade and power-supply initiatives begin to contribute measurable revenue.