










AIA Engineering Limited Gives No Near-Term NGDS Trial Timeline
Key highlights
- AIA Engineering sold about 126,000 metric tonnes in H1 FY27, versus roughly 124,000 to 125,000 tonnes in the prior-year half.
- Management gave no date for NGDS trial results and said mining-site trials had been elongated.
- AIA Engineering is internally planning for 25,000 to 30,000 tonnes of annual growth in FY28 and FY29, not formal guidance.
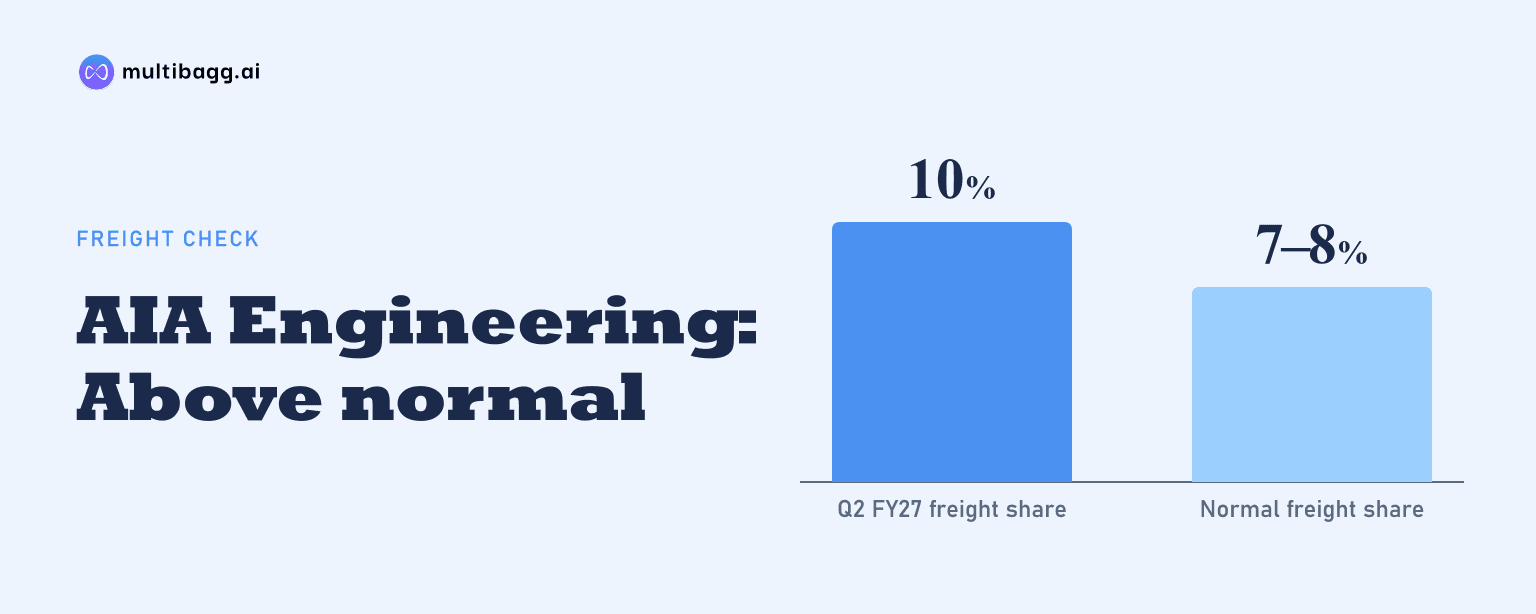
- Freight was close to 10% of Q2 FY27 sales, compared with management's stated 7% to 8% normal range.
powered by IRIS
On its November 3, 2026 earnings call, AIA Engineering gave no timetable for commercial NGDS trial results, saying trials at several mining sites had been elongated while H1 FY27 sales reached about 126,000 metric tonnes, only slightly above roughly 124,000 to 125,000 tonnes a year earlier.
Know AIA Engineering inside out
Results, valuation, peers and who's buying, in one view.
What did AIA Engineering disclose about NGDS trials?
AIA Engineering said NGDS and liner trials continued at various mining sites, including large mines, but that the trials had been elongated. Management described its mining strategy as selling a value-added package of liners and NGDS, with grinding-media volumes expected to follow when that package produces volume gains. It said it was internally positive on the trials but could not make an exact time commitment on results.
Management said success in the NGDS-plus-liner package could start becoming visible in the second half of FY27, the fiscal year ending March 2027, but called it too early to give clear guidance. This was a possible outcome rather than a volume forecast, customer conversion date or contract target. Management said it expected possible upside in H2 FY27, while stressing that the timing remained uncertain.
In the question-and-answer session, management called NGDS a structural opportunity and said its potential volumes were exciting, but said assigning a timeline would not do justice to the effort. When asked whether NGDS volume would be included in the internally discussed 25,000 to 30,000 tonnes of annual growth for FY28 and FY29, management said it could be a top-up. It did not confirm that any NGDS conversion was included in that planning range.
Were Peru and Ghana NGDS trial delays disclosed?
No Peru-specific NGDS trial, delay, result or redesign was disclosed in the November 3, 2026 transcript. AIA Engineering referred only to trials at various mining locations, including large mines, and said their duration had lengthened. It did not name a Peruvian mine, customer, trial milestone or engineering change.
Ghana appeared in the call in connection with geographic capacity expansion rather than an NGDS trial. AIA Engineering said the Ghana and China expansion plans would remain on hold for one more quarter, although management expected to reconsider them soon, potentially by the end of the next quarter. The transcript does not link that decision to a Ghana technical trial, a redesign or a commercial NGDS outcome.
The disclosed position is therefore narrower than a site-specific trial account: NGDS trials are ongoing, their duration has extended, and management has not committed to a result date. As of the November 2026 call, there was no disclosed conversion volume, named-site result or contract associated with Peru or Ghana. That leaves commercial timing, rather than a reported redesign at either location, as the documented uncertainty.
Got a follow-up? Ask IRIS
How do volumes compare with AIA Engineering's growth plan?
AIA Engineering sold about 61,500 metric tonnes in Q2 FY27, on production of about 63,600 metric tonnes, and about 126,000 tonnes in H1 FY27. The H1 figure was slightly above roughly 124,000 to 125,000 tonnes in the corresponding prior-year half, which management described as practically flat. Mining sales were about 39,700 tonnes in Q2 and about 79,000 tonnes in H1, with management citing improvement in that segment on both year-on-year and quarter-on-quarter comparisons.
Management is internally planning for annual growth of at least 25,000 to 30,000 tonnes in each of FY28 and FY29, but explicitly said this was not volume guidance. It said the range reflected what appeared possible under current conditions and that it would issue firmer guidance only when confidence improved. Management suggested it could provide more colour in the next quarter or the quarter after, without promising an update date.
The volume backdrop includes lower dispatches to one Chilean mine that stopped production for almost two months during Q2 FY27. Management said that mine had resumed normal operations from the current quarter. Separately, it said a 50% Mexican duty on imports from most countries, including India, had affected a material volume, though it did not quantify the annual tonnage involved.
What affected AIA Engineering's FY27 operating performance?
AIA Engineering reported Q2 FY27 revenue of Rs 1,093 crore and other operating income of about Rs 19.5 crore, followed by H1 revenue of Rs 2,246 crore and other operating income of about Rs 34 crore. Management said other operating income primarily comprised export benefits. Earnings before interest, tax, depreciation and amortisation, or EBITDA, were about Rs 361 crore in Q2 and Rs 786 crore in H1.
Profit after tax, or PAT, was about Rs 249 crore in Q2 and about Rs 550 crore in H1. Management said both EBITDA and PAT declined slightly year on year, with reported EBITDA down by almost 5% and operating EBITDA down by about 2.5% to 3%. It attributed the operating-margin movement chiefly to export freight costs that increased by more than 3.5% year on year in both Q2 and H1.
Freight was close to 10% of Q2 FY27 sales, an estimate raised by an analyst and confirmed by management. Management said a normal freight range would be 7% to 8%, and attributed the Q2 level partly to air freight and elevated sea freight. It expected freight to move towards the 7% to 8% range in the current quarter, while also citing product mix and the timing of freight pass-through as factors in quarterly profitability.
AIA Engineering spent Rs 86 crore on capital expenditure in H1 FY27 and expected about Rs 250 crore more in H2. That planned outlay largely includes a corporate-house land transaction, alongside about Rs 50 crore to Rs 75 crore of maintenance and incremental capital expenditure. These spending plans are separate from the Ghana and China capacity expansion, which management kept on hold for one more quarter.
Conclusion
AIA Engineering's November 2026 disclosures show that NGDS remains an active strategic trial programme rather than a dated commercial volume driver. H1 FY27 sales of about 126,000 tonnes were broadly flat against roughly 124,000 to 125,000 tonnes a year earlier, while the 25,000 to 30,000-tonne annual growth ambition for FY28 and FY29 remains internal planning, not formal guidance. The call does not disclose a Peru trial outcome or a Ghana NGDS redesign.
The next disclosed milestones are potential visibility from the liner-and-NGDS package in H2 FY27, firmer volume commentary in the next quarter or the quarter after, and a possible reconsideration of Ghana and China expansion by the end of the next quarter. Freight also remains a near-term operating variable after reaching close to 10% of Q2 sales, above management's stated 7% to 8% normal range.