










Avadh Sugar returns to profit as realisations lift margins
Key highlights
- Avadh Sugar reported H1FY27 PAT of Rs 10 crore, versus a Rs 15 crore loss in H1FY26.
- Average sugar realisation rose 8% year on year to Rs 4,321 per quintal in H1FY27.
- Sugar segment EBIT improved to Rs 45 crore in H1FY27 from a Rs 3 crore loss a year earlier.
- Distillery revenue fell to Rs 230 crore in H1FY27 from Rs 285 crore as ethanol sales volume declined 19%.
powered by IRIS
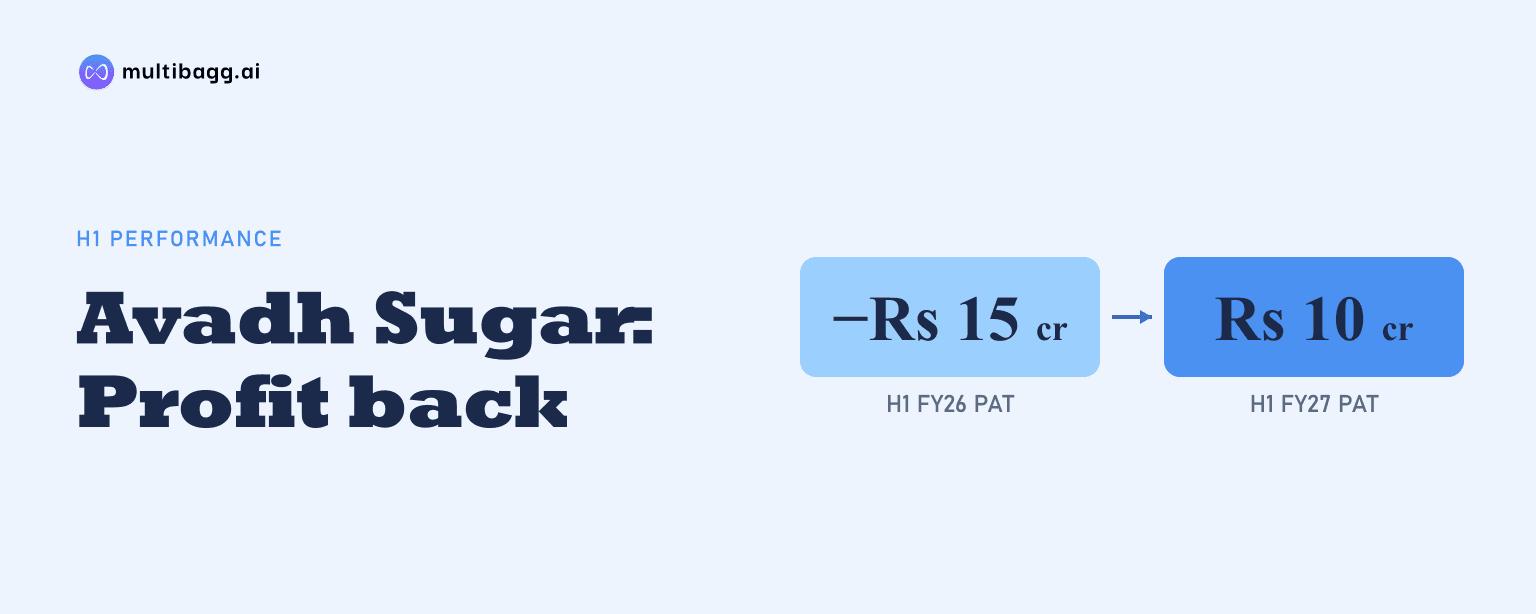
Avadh Sugar & Energy Ltd returned to a Rs 10 crore profit in H1FY27 from a Rs 15 crore loss in H1FY26, as average sugar realisation increased 8% to Rs 4,321 per quintal despite a 19% decline in ethanol sales volume. The recovery was led by the sugar segment, whose EBIT turned positive at Rs 45 crore.
Know Avadh Sugar & Energy inside out
Results, valuation, peers and who's buying, in one view.
How did Avadh Sugar return to profit in H1FY27?
Avadh Sugar returned to profit because higher sugar realisations lifted operating earnings even as total income grew by only 3.5%. Total income rose to Rs 1,436 crore in H1FY27 from Rs 1,387 crore in H1FY26, while earnings before interest, tax, depreciation and amortisation, or EBITDA, increased to Rs 80 crore from Rs 49 crore. Profit after tax, or PAT, moved to Rs 10 crore from a Rs 15 crore loss.
The quarterly figures show a similar pattern. Q2FY27 total income declined to Rs 655 crore from Rs 670 crore in Q2FY26, but EBITDA increased to Rs 42 crore from Rs 20 crore and PAT turned to a Rs 10 crore profit from a Rs 7 crore loss. Management attributed the 210% increase in Q2FY27 EBITDA and the 163% increase in H1FY27 EBITDA primarily to improved sugar realisations.
The first-half comparison shows that profit growth exceeded revenue growth. Total income rose by Rs 49 crore year on year, while EBITDA rose by Rs 31 crore and PAT improved by Rs 25 crore. The presentation identifies a 2% increase in sugar sales volume as a contributor to income growth, but identifies pricing as the main driver of the operating-profit recovery.
How much did Avadh Sugar's sugar realisation increase?
Avadh Sugar's average sugar realisation increased to Rs 4,600 per quintal in Q2FY27 from Rs 3,985 per quintal in Q2FY26, a 15% rise. The H1FY27 average was Rs 4,321 per quintal, compared with Rs 3,994 per quintal a year earlier. Management said the higher realisations strengthened margins and contributed significantly to the operating-profit recovery.
Sugar revenue, including inter-segment revenue, rose to Rs 594 crore in Q2FY27 from Rs 582 crore in Q2FY26. Revenue increased to Rs 1,257 crore in H1FY27 from Rs 1,170 crore in H1FY26, while sugar sold rose to 27.26 lakh quintals from 26.66 lakh quintals over the first half. In contrast, Q2FY27 sugar sold declined to 12.40 lakh quintals from 13.21 lakh quintals, yet quarterly sugar revenue still increased.
Sugar segment earnings before interest and tax, or EBIT, changed from losses to profits. The segment reported EBIT of Rs 36 crore in Q2FY27 against a Rs 7 crore loss in Q2FY26, and Rs 45 crore in H1FY27 against a Rs 3 crore loss in H1FY26. Management specifically linked the segment turnaround to improved sugar realisations during the current quarter.
Which Avadh Sugar segments improved and which weakened?
Avadh Sugar's sugar segment led the earnings recovery, while distillery and co-generation and other operations recorded lower revenue and weaker EBIT. Sugar revenue increased by Rs 87 crore year on year in H1FY27, whereas distillery revenue declined by Rs 55 crore and co-generation and other revenue fell by Rs 21 crore. This changed the earnings mix despite the Rs 49 crore increase in total income.
The distillery business reported revenue of Rs 73 crore in Q2FY27, down from Rs 120 crore a year earlier, and Rs 230 crore in H1FY27, down from Rs 285 crore. The presentation attributes the pressure to a 19% decline in ethanol sales volume. Distillery EBIT fell to Rs 20 lakh in Q2FY27 from Rs 12 crore and to Rs 21 crore in H1FY27 from Rs 30 crore.
Co-generation and other revenue declined to Rs 4 crore in Q2FY27 from Rs 22 crore in Q2FY26, and to Rs 20 crore in H1FY27 from Rs 41 crore. Its Q2FY27 EBIT was a Rs 9 crore loss compared with a Rs 3 crore profit a year earlier, while its H1FY27 loss widened to Rs 12 crore from Rs 1 crore. Higher sugar pricing therefore offset deterioration in the other two reported operating segments.
Got a follow-up? Ask IRIS
What do Avadh Sugar's operating metrics show?
Avadh Sugar sold 27.26 lakh quintals of sugar in H1FY27, compared with 26.66 lakh quintals in H1FY26, while reported sugar production was 0.86 lakh quintals against 1.81 lakh quintals. Sugarcane crushing declined to 6.19 lakh quintals from 14.44 lakh quintals. The displayed operational table does not provide Q2FY27 or Q2FY26 production and crushing figures.
Average recovery was 11.18% in H1FY27, marginally below 11.23% in H1FY26. The 0.05-percentage-point decline was reported alongside the reduction in sugarcane crushing. The presentation does not explain the relationship between the reported first-half production, sales and inventory figures.
The policy dashboard identifies a higher cane-cost benchmark for 2026-27. The fair and remunerative price, or FRP, was Rs 365 per quintal at 10.25% recovery, Rs 10 above the level cited for the preceding year. Uttar Pradesh's state advised price, or SAP, for 2026-27 had not been announced; the prior year's rates were Rs 400 per quintal for early variety and Rs 390 per quintal for general variety.
What could affect Avadh Sugar after H1FY27?
Avadh Sugar faces disclosed sugar-pricing and cane-cost variables in the second half. The sugar minimum selling price remained Rs 31 per kilogram, where it has stood since 2019, and was under committee review. Management said a higher floor would de-risk H2, while restricted exports meant no export upside was expected in the current season.
The distillery business also faces a feedstock restriction after the 19% decline in H1FY27 ethanol sales volume. Juice and B-heavy molasses were barred as ethanol feedstock for ethanol supply year 2026-27 under a notification dated 22 October, leaving C-heavy molasses or grain as permitted routes. The presentation said price revision and interest aid had been sought, while relief for idle distilleries remained pending.
Avadh Sugar has disclosed a plan to establish a sugar refinery at its Seohara unit. Management expects the facility to make refined sugar for premium, industrial and institutional customers and to improve sales realisations through value-added products. The presentation does not disclose the refinery's capacity, capital expenditure or commissioning date.
Conclusion
Avadh Sugar's H1FY27 turnaround was primarily a sugar-pricing recovery: the 8% rise in average first-half realisation to Rs 4,321 per quintal helped turn a Rs 15 crore PAT loss into a Rs 10 crore profit. Sugar EBIT improved to Rs 45 crore from a Rs 3 crore loss, while distillery EBIT declined to Rs 21 crore and co-generation and other EBIT recorded a Rs 12 crore loss.
Next, management's disclosed variables include the pending Uttar Pradesh SAP for 2026-27, the review of the Rs 31-per-kilogram sugar minimum selling price and any ethanol-support measures following the 22 October feedstock notification. The Seohara refinery plan also requires further disclosures on capacity, cost and commissioning timing.