










Avadh Sugar debt falls to Rs 411 crore on inventory sale
Key highlights
- Avadh Sugar reported gross debt of Rs 411 crore at September 2026, down from Rs 593 crore a year earlier.
- Cash credit and WCDL borrowings fell to Rs 19 crore at September 2026 from Rs 975 crore at 1 March 2026.
- Inventory was Rs 268 crore at 30 September 2026, compared with Rs 360 crore a year earlier.
- Avadh Sugar reported net debt of Rs 398 crore at September 2026, versus Rs 591 crore at September 2025.
powered by IRIS
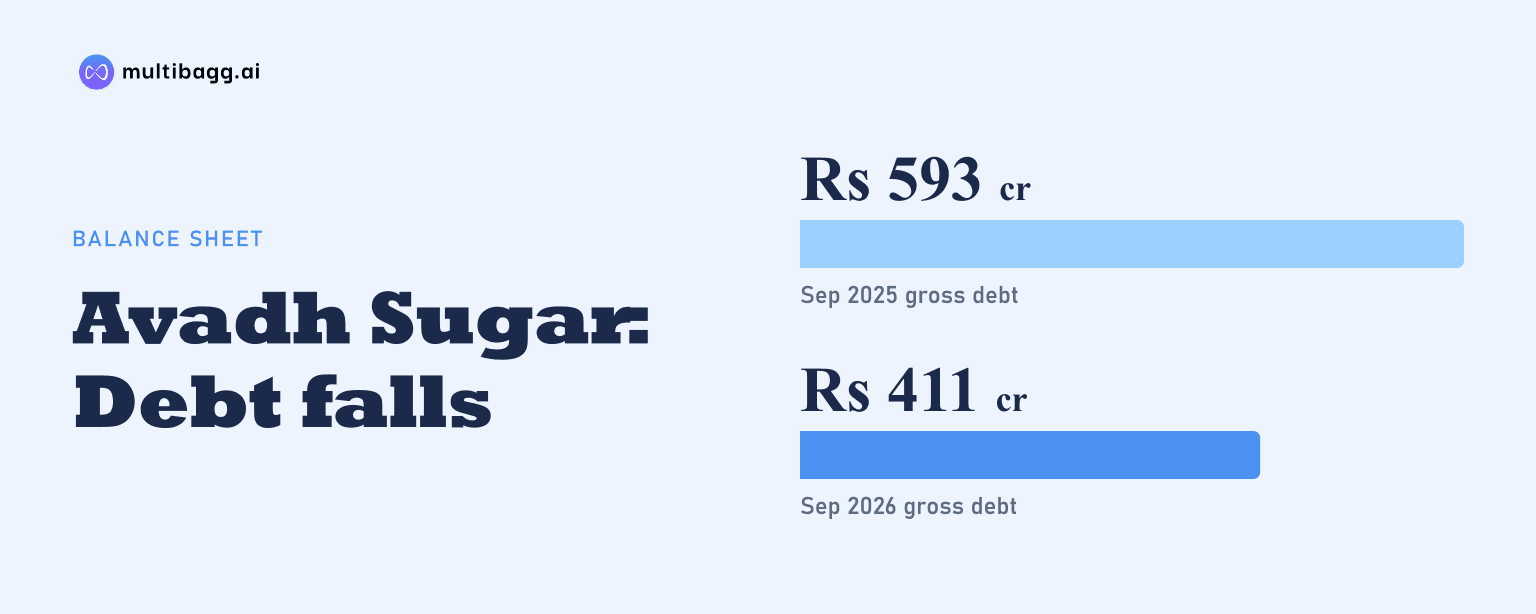
Avadh Sugar & Energy Ltd reported gross debt of Rs 411 crore at 30 September 2026, down from Rs 593 crore a year earlier, chiefly because cash-credit and working-capital debt fell to Rs 19 crore as inventory was liquidated. Avadh Sugar expects this seasonal borrowing release to reverse when sugar crushing resumes from November.
Know Avadh Sugar & Energy inside out
Results, valuation, peers and who's buying, in one view.
Why did Avadh Sugar's gross debt fall to Rs 411 crore?
Avadh Sugar's gross debt declined mainly because short-term working-capital borrowings fell to Rs 19 crore at September 2026 from Rs 202 crore at September 2025 and Rs 975 crore at 1 March 2026. Total debt declined to Rs 411 crore from Rs 593 crore a year earlier and Rs 1,406 crore at 1 March 2026.
The movement was concentrated in cash credit and working-capital demand loan, or WCDL, balances. Cash credit and WCDL declined by Rs 956 crore between 1 March 2026 and September 2026, while term loans declined by Rs 39 crore to Rs 392 crore over the same period. This means the working-capital release accounted for most of the Rs 995 crore reduction in total debt across those two dates.
The year-on-year comparison shows a similar pattern. Term loans were Rs 392 crore at September 2026, compared with Rs 391 crore at September 2025, while cash credit and WCDL fell by Rs 183 crore to Rs 19 crore. The Rs 182 crore fall in gross debt was therefore predominantly a short-term borrowing movement rather than a reduction in term loans.
How did inventory liquidation affect Avadh Sugar's borrowings?
Inventory liquidation reduced the funding requirement during the off-season quarter. Avadh Sugar reported inventory of Rs 268 crore at 30 September 2026, comprising sugar worth Rs 223 crore and molasses, ethanol and other inventory worth Rs 45 crore, compared with total inventory of Rs 360 crore a year earlier.
The company described Q2FY27 as an off-season quarter for Uttar Pradesh sugar mills, when earnings were primarily generated from sales of stock accumulated during the crushing season. That operating cycle coincided with the reduction in inventory from Rs 360 crore at September 2025 to Rs 268 crore at September 2026 and the fall in working-capital borrowings from Rs 202 crore to Rs 19 crore.
Avadh Sugar has cautioned that the September position will not necessarily persist through the crushing cycle. Management said working-capital debt declined during Q2FY27 but is expected to rebuild from November with the start of sugar crushing. It also said exclusive use of C-heavy molasses at the distillery is expected to increase sugar availability and contribute to higher sugar inventory.
Got a follow-up? Ask IRIS
What was Avadh Sugar's net debt and available liquidity?
Avadh Sugar reported net debt of Rs 398 crore at September 2026, down from Rs 591 crore at September 2025. Gross debt was Rs 411 crore and cash and liquid investments were Rs 13 crore, compared with gross debt of Rs 593 crore and cash and liquid investments of Rs 2 crore a year earlier.
Cash, cash equivalents and bank balances were Rs 3 crore at September 2026, while surplus funds in liquid or debt mutual funds were Rs 10 crore. The Rs 11 crore increase in cash and liquid investments meant net debt fell by Rs 193 crore year on year, slightly more than the Rs 182 crore reduction in gross debt.
H1FY27 cash-flow figures showed Rs 1,095.84 crore of net cash generated from operating activities and Rs 1,052.03 crore used in financing activities. In H1FY26, operating cash generation was Rs 915.77 crore and financing cash outflow was Rs 842.61 crore. Cash used in investing activities declined to Rs 42.72 crore in H1FY27 from Rs 74.60 crore in H1FY26.
What do Avadh Sugar's earnings and borrowing costs indicate?
Avadh Sugar reported an average Q2FY27 cost of 7.96% for long-term borrowings and 6.89% for short-term borrowings. Interest expense declined to Rs 13 crore in Q2FY27 from Rs 16 crore in Q2FY26, while H1FY27 interest expense fell to Rs 35 crore from Rs 42 crore.
Q2FY27 total income declined 2.2% year on year to Rs 655 crore, but earnings before interest, tax, depreciation and amortisation, or EBITDA, increased to Rs 42 crore from Rs 20 crore. EBITDA margin rose to 6.4% from 3.0%, and profit after tax was Rs 10 crore compared with a Rs 7 crore loss in Q2FY26.
Management attributed the Q2FY27 margin improvement to higher sugar realisations and lower cost of inventory sold. It said lower ethanol sales volumes adversely affected revenue and profitability, while the increase in molasses levy obligation for the 2025-26 sugar season had an adverse profitability impact of about Rs 10 crore. For H1FY27, EBITDA rose to Rs 80 crore from Rs 49 crore and profit after tax turned to Rs 10 crore from a Rs 15 crore loss.
Conclusion
Avadh Sugar's September 2026 debt reduction was principally a seasonal working-capital release. Gross debt fell by Rs 182 crore year on year to Rs 411 crore, while term loans were broadly unchanged at Rs 392 crore and cash credit and WCDL fell to Rs 19 crore. Lower inventory of Rs 268 crore and off-season stock sales were central to that movement.
The next balance-sheet measure to watch is the rebuilding of working-capital debt from November, which management expects with the commencement of crushing. Management's plan to run the distillery exclusively on C-heavy molasses is also expected to increase sugar availability and inventory, creating a disclosed mechanism for renewed inventory funding needs.