










BlackBuck record device sales defer telematics revenue recognition
Key highlights
- BlackBuck set a new record for new telematics-device sales in Q2 FY27, with revenue recognised over a year rather than at sale.
- BlackBuck's revenue from operations rose 56% year on year and 15% sequentially in Q2 FY27.
- BlackBuck reported net revenue of Rs 183 crore in Q2 FY27, up 35% year on year.
- BlackBuck reported adjusted EBITDA of Rs 55 crore in Q2 FY27, up close to 30% year on year.
powered by IRIS
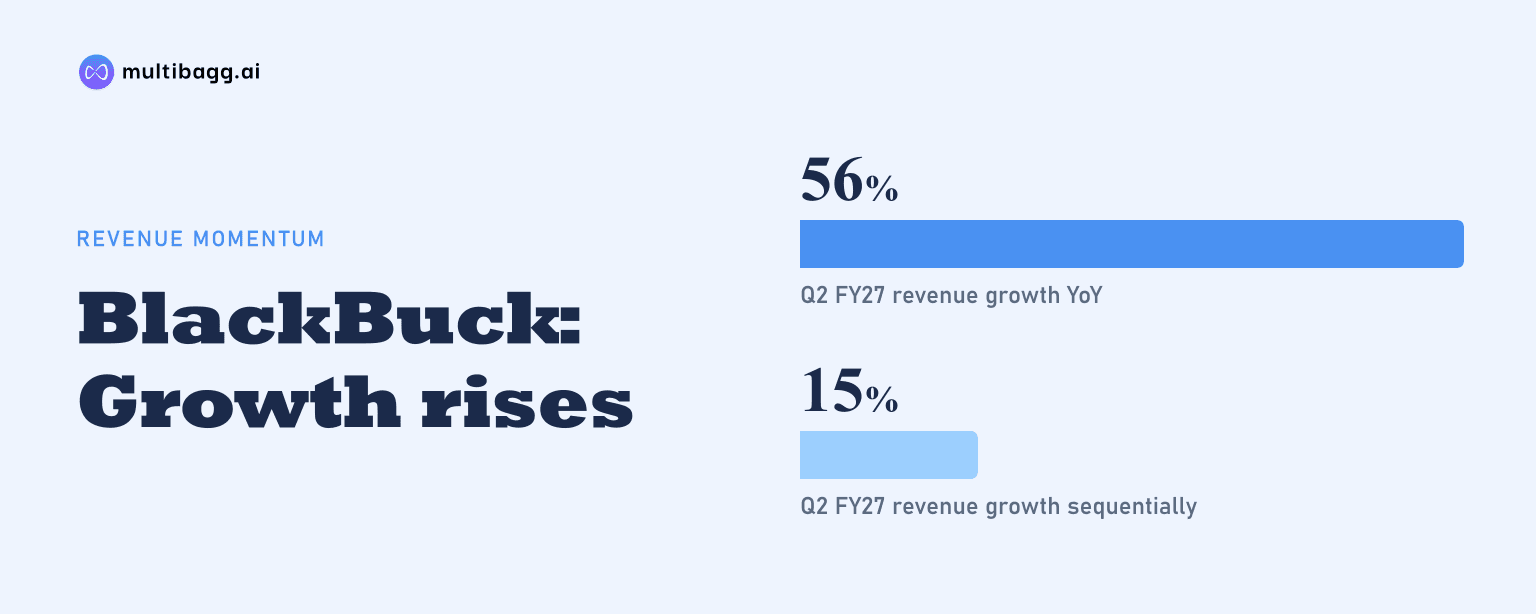
BlackBuck Limited set a new record for new telematics-device sales in Q2 FY27, but recognises the related revenue over a year rather than in the sale month, while revenue from operations rose 56% year on year in the same period. The accounting treatment increased deferred revenue and means reported telematics revenue will follow device sales over future quarters.
Know Blackbuck inside out
Results, valuation, peers and who's buying, in one view.
Why did BlackBuck's record telematics sales not fully appear in Q2 revenue?
BlackBuck said revenue from a telematics device is recognised across a year, so a device sale made in Q2 FY27 did not produce its full revenue contribution in the month it was sold. Management said it had surpassed the previous quarter's record for new-device sales, while the deferred-revenue item on the balance sheet continued to increase. It did not disclose device volumes, the deferred-revenue balance or telematics revenue for the quarter.
This creates a timing difference between the operational sales record and reported income. BlackBuck said some benefit from accelerating telematics sales was visible in Q2 FY27, but the remaining revenue recognition would continue in later quarters. Revenue from operations rose 56% year on year and 15% sequentially, while net revenue rose 35% year on year to Rs 183 crore, indicating that the reported quarterly figure includes only the recognised portion of telematics sales.
Were AIS mandates the stated reason for BlackBuck's device-sales record?
No, BlackBuck did not mention AIS, state-level mandates, compliance requirements or any other specific regulation as the reason for the Q2 FY27 telematics-device sales record. Management said telematics sales had accelerated in the preceding quarter and continued to accelerate in Q2 FY27, but provided no stated external demand trigger. The call also did not identify states, customer categories or vehicle types behind the record.
BlackBuck instead positioned telematics as one of several newer streams within its core business. Management said mature core activities were growing in the higher teens to about 20% range, while newer streams were supporting faster overall core growth. Core businesses grew 31% year on year and roughly 11% sequentially in Q2 FY27, but the company did not quantify telematics' contribution to either measure.
The absence of a stated regulatory driver limits what can be concluded about the durability or composition of device demand from this call alone. BlackBuck did not say how many sales went to new customers versus existing users, whether devices were incremental installations or replacements, or what proportion of its roughly 9 lakh transacting customers used telematics. The disclosed evidence supports a sales record and deferred recognition, not an attribution to mandates.
How did faster telematics sales affect BlackBuck's margin mix?
BlackBuck said telematics carries a lower contribution margin than its other revenue streams, creating a slight dip in the blended contribution-margin profile in Q2 FY27. Management nevertheless said overall contribution margin remained much above 90% and grew 33% year on year. It did not provide a precise contribution-margin percentage or a separate margin for the telematics business.
The mix effect occurred alongside growth in both profit and investment. Adjusted earnings before interest, tax, depreciation and amortisation, or adjusted EBITDA, reached Rs 55 crore, up close to 30% year on year, while reported EBITDA was Rs 51 crore, up 40%. BlackBuck said the adjusted measure includes investments in newer and emerging businesses, meaning it includes the cost of initiatives that management intends to explain separately later.
Total expenses rose 36% year on year in Q2 FY27, compared with growth generally in the teens in earlier periods, according to management. BlackBuck attributed the increase to expansion across core businesses and investment in Super Loads, its loads business. Therefore, the change in blended margin reflects telematics mix as well as a wider cost base for growth, rather than a disclosed standalone telematics-profit measure.
Got a follow-up? Ask IRIS
How does telematics compare with BlackBuck's other growth indicators?
Telematics was the only core-business stream for which BlackBuck highlighted a new quarterly sales record, but it did not publish a rupee sales value. By comparison, tolling gross transaction value, or GTV, was about Rs 7,070 crore in Q2 FY27, up 17% year on year. Management described the rainy quarter as seasonally weaker and said tolling activity typically begins to improve in Q3 and Q4.
The separately reported growth businesses, comprising Loads and vehicle finance, grew about 2.7 times, or 166% year on year, and 25% sequentially in Q2 FY27. That exceeded the 31% year-on-year core-business growth rate, although BlackBuck did not disclose revenue or profitability for either group. Management said Super Loads had expanded into new cities while existing cities improved productivity through work on artificial intelligence-based matchmaking.
BlackBuck's customer and distribution measures provide context for selling new services, though not telematics penetration. Transacting customers were close to 9 lakh, up about 13% year on year, and power users who use more than two services were close to 4.80 lakh, up roughly 20%. The company also reported 10,000 distribution touchpoints and presence in 80% of districts, but gave no figure for devices sold through those channels.
What should readers watch in BlackBuck's next results?
Readers should watch for evidence that the rising deferred-revenue item is converting into recognised telematics revenue after Q2 FY27. Management said the record device sales would contribute in subsequent quarters because recognition occurs over a year. Useful disclosures would include device volumes, deferred-revenue balances, separate telematics revenue and the precise movement in contribution margin, none of which was provided on this call.
The broader operating backdrop is also relevant because BlackBuck expects customary seasonal improvement in tolling in Q3 and Q4 after Q2 GTV of Rs 7,070 crore. Management said the core business continued to generate operating cash flow, while it had stepped up investment in Super Loads. It also said vehicle finance, a partner-led model with partner-managed assets under management rising steadily, remained on track for EBITDA break-even in FY27.
Conclusion
BlackBuck's Q2 FY27 disclosure shows that its telematics sales momentum and its reported revenue will not move in lockstep. The company achieved a new high in new-device sales while recognising those sales over a year, alongside 56% year-on-year growth in revenue from operations and Rs 183 crore of net revenue. Telematics also contributed to a modestly lower blended contribution-margin profile because its margin is below that of BlackBuck's other revenue streams.
The next updates should clarify whether deferred revenue from the device-sales record supports continued reported growth, and whether BlackBuck provides separate telematics metrics. Management's disclosed milestones are vehicle finance reaching EBITDA break-even during FY27, continued investment in Super Loads as its playbook develops, and the historically stronger Q3 and Q4 period for tolling activity.