










Blue Star Q2 revenue rises 21% as core margins decline
Key highlights
- Blue Star’s Q2FY27 consolidated revenue rose 21.0% to Rs 2,930.95 crore, while net profit increased 25.4% to Rs 123.91 crore.
- Consolidated EBITDA increased to Rs 202.58 crore, but the margin excluding other income declined to 6.9% from 7.6%.
- Segment II revenue grew 29.4% to Rs 897.66 crore, while its result margin fell to 2.3% from 6.2%.
- Blue Star’s carried-forward order book stood at Rs 7,229.22 crore as of September 30, 2026, and the company moved to net cash of Rs 289.43 crore.
powered by IRIS
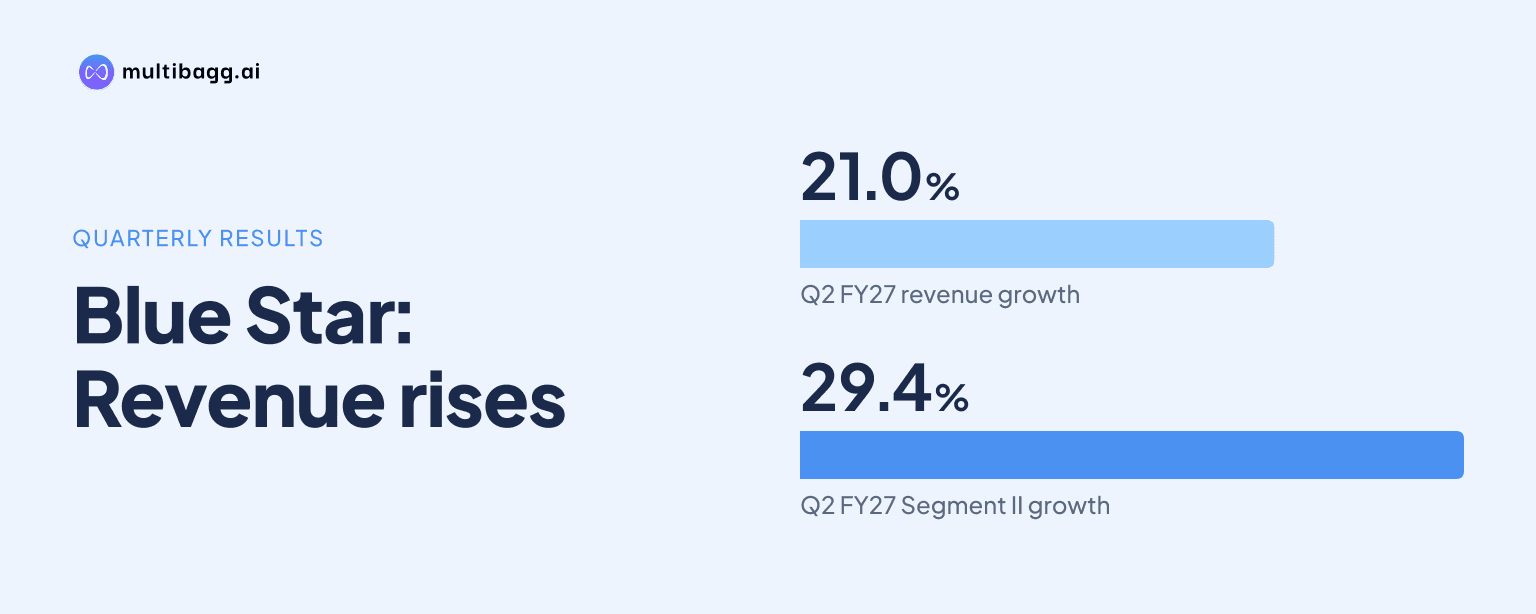
Blue Star Limited reported Q2FY27 consolidated revenue from operations of Rs 2,930.95 crore, up 21.0% from Rs 2,422.37 crore a year earlier, while net profit rose 25.4% to Rs 123.91 crore. Blue Star’s EBITDA margin excluding other income fell to 6.9% from 7.6% as material-cost increases were not fully recovered through pricing.
Know Blue Star inside out
Results, valuation, peers and who's buying, in one view.
Why did Blue Star’s Q2FY27 revenue increase?
Blue Star’s Q2FY27 revenue increased as an extended summer and delayed monsoon supported Room AC demand, while all three reported segments recorded revenue growth. Consolidated revenue increased by Rs 508.58 crore from Rs 2,422.37 crore in Q2FY26 to Rs 2,930.95 crore in Q2FY27. Management said the extended summer season produced robust demand for Room ACs.
Segment I, Electro-Mechanical Projects and Commercial Air Conditioning Systems, remained Blue Star’s largest business, reporting revenue of Rs 1,935.99 crore, up 16.3%. Segment II, Unitary Products, grew 29.4% to Rs 897.66 crore, while Segment III, Professional Electronics and Industrial Systems, grew 51.2% to Rs 97.30 crore. The comparison shows that growth was broad-based, although segment profitability moved differently.
Within Segment I, Blue Star attributed Commercial Air Conditioning Systems growth to demand from healthcare, education and industrial customers. It launched new-generation variable refrigerant flow, or VRF, systems and ducted systems during Q2FY27. Electro-Mechanical Projects received order inflows mainly from data centres, although billing growth was sluggish because execution of a few projects was delayed.
How did Blue Star’s profitability change in Q2FY27?
Blue Star’s EBITDA increased in rupee terms, but the EBITDA margin excluding other income declined by 0.7 percentage points to 6.9% in Q2FY27 from 7.6% in Q2FY26. EBITDA rose to Rs 202.58 crore from Rs 183.41 crore. The company attributed the margin movement to continuing material-cost escalation and its inability to fully pass the increase on to customers.
Profit before tax, before the share of profit or loss of joint ventures and exceptional items, was Rs 133.61 crore in Q2FY27, compared with Rs 133.16 crore in Q2FY26. Tax expense was unchanged at Rs 33.39 crore, while net profit rose by Rs 25.13 crore to Rs 123.91 crore. Blue Star said cost-optimisation initiatives were beginning to show results.
The two largest operating segments recorded lower result margins despite revenue growth. Segment I’s result declined to Rs 133.15 crore from Rs 147.14 crore, reducing its margin to 6.9% from 8.8%. Segment II’s result fell to Rs 20.74 crore from Rs 42.72 crore, with its margin declining to 2.3% from 6.2%.
Got a follow-up? Ask IRIS
Which Blue Star businesses drove the margin movements?
Blue Star’s Unitary Products margin declined because price increases in Room ACs and commercial refrigeration did not recover all material-cost escalation. The company said it periodically increased prices in Cooling and Purification Products, but passed on only part of the higher costs. It has begun a programme to reshape the product portfolio with differentiated and cost-optimised stock-keeping units, or SKUs, to improve margins.
Commercial refrigeration showed a revival in demand during Q2FY27, but faced the same gap between material costs and price recovery. Segment II revenue increased by Rs 203.85 crore year on year, while its result decreased by Rs 21.98 crore. This reported contrast shows that the division’s higher revenue did not produce a higher segment result.
Segment III recorded a different outcome, with its result rising to Rs 23.10 crore from Rs 6.17 crore and its margin increasing to 23.7% from 9.6%. Blue Star completed the sale of its MedTech business for Rs 35.65 crore on August 31, 2026. The company said a warranty provision was written back because it no longer had MedTech warranty obligations, improving profitability.
Industrial solutions continued to grow on manufacturing and testing demand, while Data Security Solutions had steady performance driven by banking, financial services and insurance customers and large enterprises. In international operations, Blue Star continued heat-pump supplies to the United States despite supply-chain and logistics challenges, and is developing and testing products for additional original equipment manufacturers in the United States and Europe.
What is Blue Star’s outlook for H2FY27?
Blue Star expects revenue-growth momentum in H2FY27 and says its margin focus will be price revisions and product-cost optimisation. Management cited robust Room AC demand during the festival season, expected more data-centre mechanical, electrical and plumbing project orders to be finalised in coming months, and reported reviving demand for commercial air-conditioning and refrigeration products.
Blue Star’s carried-forward consolidated order book was Rs 7,229.22 crore at September 30, 2026, compared with Rs 7,120.44 crore at September 30, 2025 and Rs 6,923.00 crore at March 31, 2026. The Electro-Mechanical Projects order book increased 6.2% year on year to Rs 5,141.78 crore, with data centres the main source of order inflows during the quarter.
Blue Star’s capital employed decreased to Rs 3,200.36 crore at September 30, 2026 from Rs 3,530.88 crore a year earlier. Its position changed to net cash of Rs 289.43 crore, compared with net borrowings of Rs 417.06 crore at September 30, 2025.
Management said a monsoon shortfall, lower farm income and an interest-rate increase could affect demand. It also said the conclusion of a United States trade deal and a possible resolution of the West Asia crisis could be supportive, while tariff-related uncertainty could affect the pace of international heat-pump business development.
Conclusion
Blue Star’s Q2FY27 results combined 21.0% consolidated revenue growth with lower margins in its two largest segments. Segment I revenue reached Rs 1,935.99 crore but its result margin fell to 6.9%, while Segment II revenue reached Rs 897.66 crore and its margin declined to 2.3%, reflecting incomplete recovery of material-cost increases through pricing.
The next measures to watch are Blue Star’s planned price revisions and cost-optimised SKU programme, alongside the finalisation of expected data-centre mechanical, electrical and plumbing orders. Management’s H2FY27 outlook also depends on festival-season Room AC demand, commercial-product demand and the resolution of tariff uncertainty affecting heat-pump development for original equipment manufacturers.