










Blue Star H1 revenue rose 16.7% while EBITDA slipped 1.5%
Key highlights
- Blue Star’s H1FY27 revenue from operations rose 16.7% to Rs 6,308.87 crore.
- H1FY27 EBITDA excluding other income fell 1.5% to Rs 377.53 crore, while profit before tax before exceptional items declined 12.1% to Rs 259.70 crore.
- Blue Star’s Q2FY27 Unitary Products revenue increased 29.4% to Rs 897.66 crore, but its EBIT margin fell 390 basis points to 2.3%.
- Blue Star moved from net borrowings of Rs 417.06 crore in H1FY26 to a net cash position of Rs 289.43 crore in H1FY27.
powered by IRIS
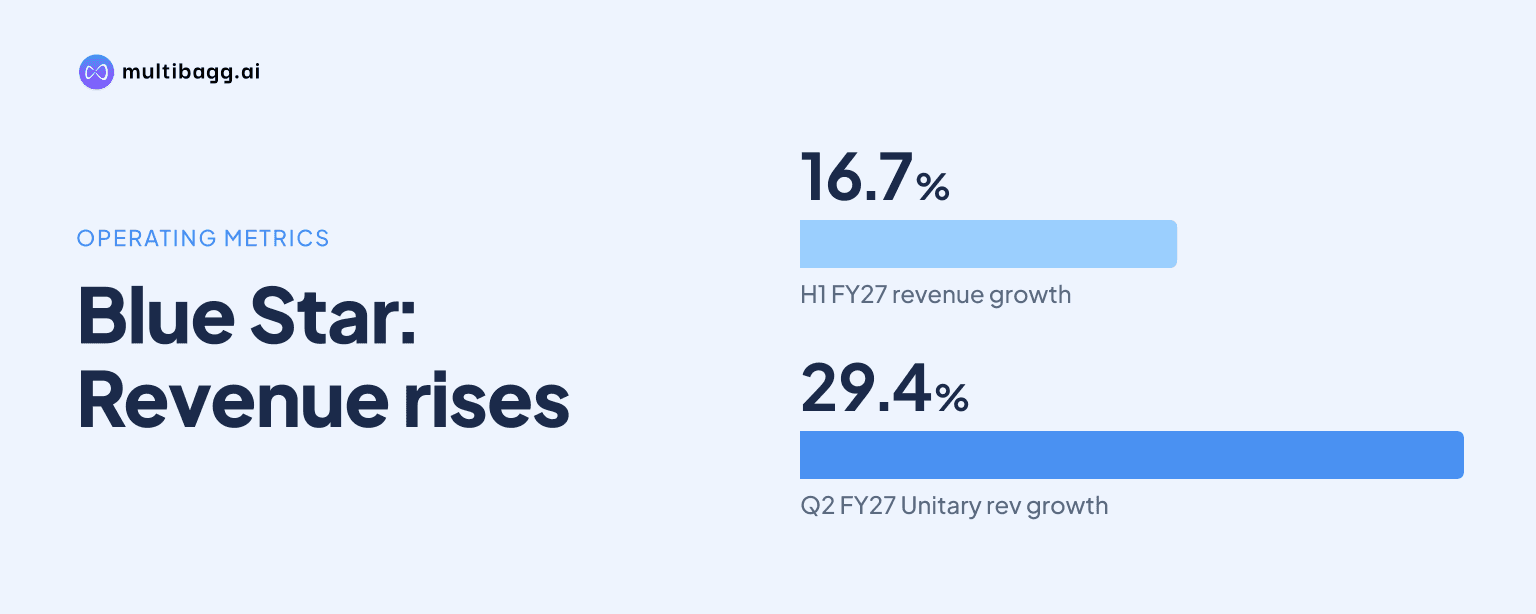
Blue Star reported H1FY27 revenue from operations of Rs 6,308.87 crore, up 16.7% from Rs 5,404.62 crore in H1FY26, but EBITDA excluding other income declined 1.5% to Rs 377.53 crore. In Q2FY27, its two largest segments increased revenue while lower price recovery of material-cost escalation reduced earnings before interest and tax margins.
Know Blue Star inside out
Results, valuation, peers and who's buying, in one view.
What changed in Blue Star’s H1FY27 earnings?
Blue Star’s H1FY27 revenue increased by Rs 904.25 crore from H1FY26, while earnings before interest, tax, depreciation and amortisation, or EBITDA, excluding other income fell to Rs 377.53 crore from Rs 383.41 crore. Profit before tax before exceptional items declined 12.1% to Rs 259.70 crore from Rs 295.40 crore, showing that higher sales did not translate into higher underlying earnings.
Blue Star reported H1FY27 net profit of Rs 226.42 crore, compared with Rs 219.60 crore in H1FY26, while earnings per share rose to Rs 11.01 from Rs 10.68. Net profit included Rs 32.19 crore of exceptional gains, comprising Rs 23.02 crore on the sale of the MedTech business and Rs 9.17 crore profit on the sale of property.
Why did Blue Star’s operating earnings decline?
Blue Star attributed pressure in its Electro-Mechanical Projects and Commercial Air Conditioning Systems segment to material-cost escalation that it could not fully pass on to customers. Q2FY27 revenue in the segment rose 16.3% to Rs 1,935.99 crore from Rs 1,664.21 crore, but segment result declined 9.5% to Rs 133.15 crore from Rs 147.14 crore.
The segment’s earnings before interest and tax, or EBIT, margin fell 190 basis points to 6.9% in Q2FY27 from 8.8% in Q2FY26. Blue Star said product-business revenue grew robustly, while project-business revenue remained subdued because of execution delays, creating a different revenue outcome within the same Rs 1,935.99 crore segment.
The pricing and cost pattern also affected Unitary Products, Blue Star’s second-largest Q2FY27 segment by revenue. Revenue rose 29.4% to Rs 897.66 crore from Rs 693.81 crore, but segment result fell 51.4% to Rs 20.74 crore from Rs 42.72 crore as periodic price increases recovered only part of material-cost escalation.
Which businesses drove Blue Star’s Q2FY27 revenue growth?
Blue Star’s Electro-Mechanical Projects and Commercial Air Conditioning Systems segment remained its largest Q2FY27 business, with Rs 1,935.99 crore in revenue, compared with Rs 897.66 crore for Unitary Products. Product-business growth supported the larger segment, while US heat-pump supplies continued despite supply-chain and logistics challenges, supported by growing market acceptance.
Unitary Products recorded 29.4% revenue growth in Q2FY27, supported by an extended summer that increased demand for room air conditioners. Blue Star also said Commercial Refrigeration had begun to see demand revival in deep freezers, bottled-water dispensers and storage water coolers, although the segment’s EBIT margin fell to 2.3% from 6.2%.
Professional Equipment and Industrial Solutions was smaller at Rs 97.30 crore of Q2FY27 revenue, but it posted the fastest segment revenue growth at 51.2%, from Rs 64.35 crore. Segment result rose 274.4% to Rs 23.10 crore and EBIT margin increased to 23.7% from 9.6%, following a write-back of warranty provisions after MedTech product-related obligations ceased.
Got a follow-up? Ask IRIS
How did the MedTech sale affect Blue Star’s results?
Blue Star completed the sale of its MedTech business on August 31, 2026, and recorded an exceptional gain of Rs 23.02 crore from the transaction in H1FY27. The sale was part of the Rs 32.19 crore exceptional gains included in H1FY27 net profit of Rs 226.42 crore.
The MedTech sale also affected the Professional Equipment and Industrial Solutions segment in Q2FY27. Blue Star said the cessation of MedTech product-related obligations enabled a write-back of warranty provisions, contributing to the segment’s 1,410-basis-point increase in EBIT margin to 23.7%.
The gain and warranty-provision write-back distinguish the smaller segment’s earnings movement from the margin pressure disclosed in the two larger businesses. Electro-Mechanical Projects and Commercial Air Conditioning Systems generated Rs 133.15 crore of Q2FY27 segment result and Unitary Products generated Rs 20.74 crore, both below their Q2FY26 results despite revenue growth.
What do Blue Star’s order book and balance sheet show?
Blue Star reported a carried-forward order book of Rs 7,229.22 crore, up 1.5% from Rs 7,120.44 crore reported as of September 30, 2026. Management said order enquiry remained strong in Electro-Mechanical Projects and Commercial Air Conditioning Systems and expected significant growth in order inflows, despite Q2FY27 project execution delays.
Blue Star’s balance-sheet presentation showed net borrowings of Rs 417.06 crore in H1FY26 changing to a net cash position of Rs 289.43 crore in H1FY27. Net debt to equity moved from 0.13 times to negative 0.08 times, while net worth increased to Rs 3,486.70 crore from Rs 3,110.96 crore.
Capital turns remained unchanged at 4.0 times in H1FY27 and H1FY26. The presentation provides order-book and balance-sheet data alongside the H1FY27 revenue increase of 16.7%, but it does not provide an H1FY27 segment-by-segment profit table.
Conclusion
Blue Star’s H1FY27 results show a gap between revenue growth and underlying operating earnings. Revenue reached Rs 6,308.87 crore, but EBITDA excluding other income fell to Rs 377.53 crore and profit before tax before exceptional items declined to Rs 259.70 crore. Q2FY27 disclosures link that gap to incomplete recovery of material-cost escalation in the company’s two largest segments.
The next indicators are the order inflows management expects in Electro-Mechanical Projects and Commercial Air Conditioning Systems, the resolution of project execution delays, and the extent to which price increases recover material-cost escalation. Blue Star also reported continued US heat-pump supplies despite logistics challenges and a Rs 7,229.22 crore carried-forward order book, both of which may affect subsequent revenue conversion.