










Blue Star Ltd revenue rises 21% as Q2 margins narrow on costs
Key highlights
- Blue Star Ltd’s Q2FY27 revenue from operations rose 21% year on year to ₹2,930.95 crore.
- Q2FY27 EBITDA increased 10.5% to ₹202.58 crore, while EBITDA margin narrowed to 6.9% from 7.6%.
- The Unitary Products segment’s Q2FY27 revenue grew 29.4% to ₹897.66 crore, supported by room air-conditioner demand.
- Blue Star ended September 2026 with net cash of ₹289.43 crore, compared with net borrowings of ₹417.06 crore a year earlier.
powered by IRIS
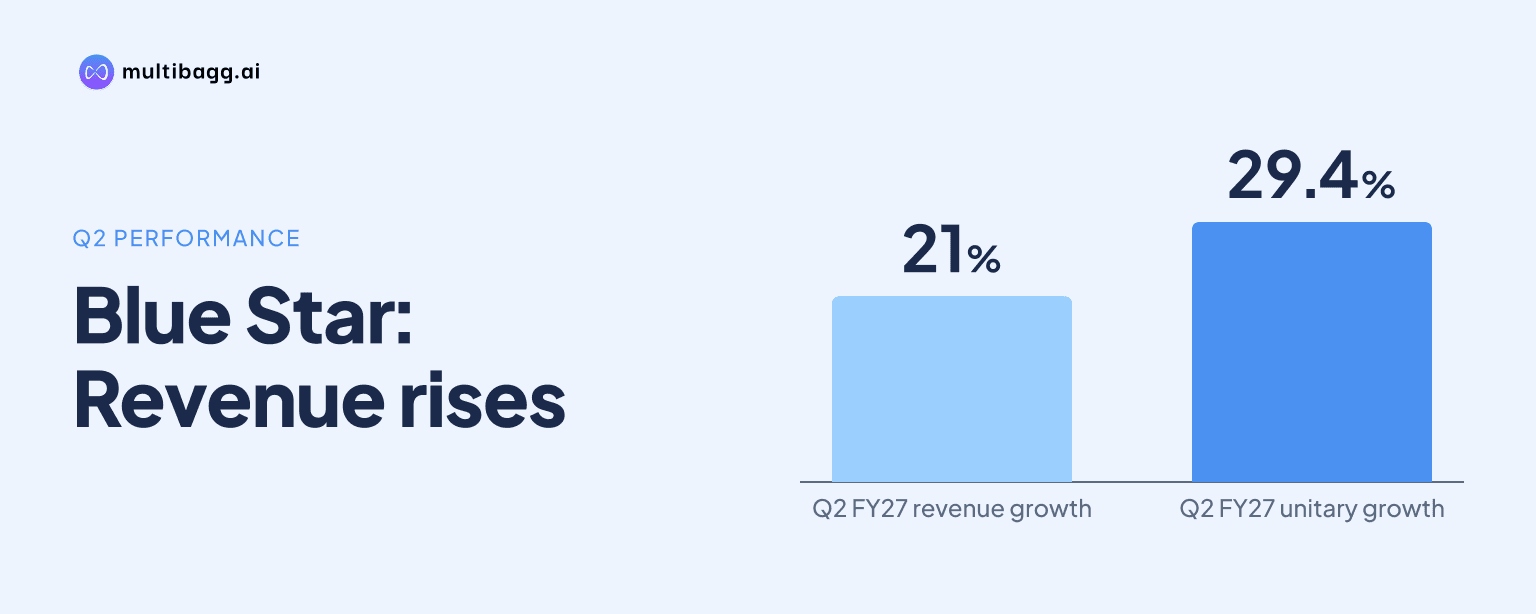
Blue Star Ltd reported consolidated revenue from operations of ₹2,930.95 crore in Q2FY27, a 21% increase from a year earlier, supported by room air-conditioner demand. However, EBITDA margin declined to 6.9% from 7.6% as higher material costs could not be fully passed on to customers.
Know Blue Star inside out
Results, valuation, peers and who's buying, in one view.
What did Blue Star Ltd report for Q2FY27?
Blue Star Ltd reported a 21% year-on-year increase in consolidated revenue from operations to ₹2,930.95 crore for the quarter ended September 30, 2026, compared with ₹2,422.37 crore in Q2FY26. Consolidated net profit rose 25.4% to ₹123.91 crore from ₹98.78 crore in the corresponding quarter a year earlier.
The profit figure included an exceptional gain of ₹23.02 crore from the sale of the MedTech business. Before exceptional items and the share of profit or loss from joint ventures, profit before tax was ₹133.61 crore, only marginally higher than ₹133.16 crore in the year-ago quarter. This indicates that the rise in reported net profit was partly supported by the exceptional gain.
Operating profit, measured as EBITDA excluding other income, increased 10.5% to ₹202.58 crore from ₹183.41 crore. Its growth lagged revenue growth, resulting in a decline in operating margin. The company said rising input costs and limited ability to transfer the increase to customers affected margins across its businesses.
Why did Blue Star Ltd revenue grow during the quarter?
Blue Star attributed the revenue growth partly to robust demand for room air-conditioners, aided by an extended summer season and a delayed monsoon. The Unitary Products segment, which includes room air-conditioners and commercial refrigeration products, recorded revenue growth of 29.4% to ₹897.66 crore during the quarter.
The performance shows continued demand for cooling products even as the company faced pressure on pricing and input costs. Revenue momentum was also reflected in the company’s Electro-Mechanical Projects and Commercial Air Conditioning Systems business, which generated ₹1,935.99 crore in the quarter.
For the first half of FY27, consolidated revenue rose 16.7% to ₹6,308.87 crore. But EBITDA for the six-month period declined to ₹377.53 crore from ₹383.41 crore in the corresponding period of the previous year, underlining that margin pressure has extended beyond the September quarter.
The difference between revenue and operating-profit growth is relevant for investors because it shows that higher sales have not translated proportionately into operating earnings. Blue Star’s ability to manage material costs and realise appropriate pricing remains important to its profitability.
Got a follow-up? Ask IRIS
How is Blue Star Ltd strengthening its senior leadership?
Blue Star has appointed Nithianand S, Group President, Supply Chain & Procurement, and Senthil Thangam, President, Air Conditioning & Refrigeration Solutions Group, as senior management personnel with effect from November 1, 2026. The appointments come as the company manages growth across its air-conditioning, refrigeration and project businesses.
Nithianand S leads the supply chain and procurement function, an area of direct relevance while material costs are affecting margins. Senthil Thangam heads the Air Conditioning & Refrigeration Solutions Group. His previous association included the launch of inverter VRF systems, inverter ducted machines, configured screw chillers, side-discharge VRF systems and centrifugal chillers.
The leadership changes follow the board meeting held on October 29, 2026, when directors approved and took on record unaudited standalone and consolidated results for the second quarter and first half ended September 30, 2026. Deloitte Haskins & Sells LLP’s limited review reports were also taken on record.
No revised financial guidance was disclosed in the board-meeting filing. However, the appointments place supply-chain oversight and the commercial cooling portfolio under formally designated senior management personnel at a time when the company is balancing demand growth with cost management.
What does Blue Star Ltd's order book and cash position indicate?
Blue Star ended September 2026 with a carried-forward order book of ₹7,229.22 crore, marginally above ₹7,120.44 crore a year earlier. The order book provides visibility for its project and commercial businesses, although its execution and profitability will depend on project schedules, costs and customer demand.
The company also reported a net cash position of ₹289.43 crore at the end of the quarter, compared with net borrowings of ₹417.06 crore as of September 30, 2025. The movement from net borrowings to net cash marks a material improvement in the balance-sheet position based on the reported figures.
Chairman and Managing Director Vir S Advani said the company expects strong room air-conditioner demand and significant order inflows for data-centre MEP projects. He also noted a revival in demand across commercial air-conditioning and commercial refrigeration businesses. These comments identify the segments that Blue Star is monitoring for growth in the second half.
For the wider cooling-products industry, the quarter highlights the effect of seasonal weather on room AC demand and the operational significance of raw-material costs. Demand can support revenue growth, but the reported decline in margin demonstrates the importance of procurement discipline and pricing flexibility.
Conclusion
Blue Star’s Q2FY27 results showed strong revenue growth, led by room air-conditioner demand, alongside a 25.4% increase in reported net profit. Yet EBITDA margin declined as operating-profit growth trailed sales growth, and the exceptional gain from the MedTech business sale contributed to the net-profit outcome.
The next factors to watch are room AC demand, data-centre MEP order inflows and the stated revival in commercial cooling demand. Investors will also monitor whether the company can improve cost recovery, especially after first-half EBITDA declined despite a 16.7% rise in revenue.