










Blue Water Logistics H1 revenue reaches 125% of full FY26 sales
Key highlights
- Blue Water Logistics reported H1 FY27 revenue of Rs 483.3 crore, up 249.5% year on year.
- Q2 FY27 EBITDA margin increased 270 basis points to 13.0% from 10.3%.
- Q2 FY27 ocean freight volume increased 148% year on year to 6,820 TEUs.
- Blue Water Logistics launched a dry-container NVOCC division with 3,000-plus TEUs of capacity.
powered by IRIS
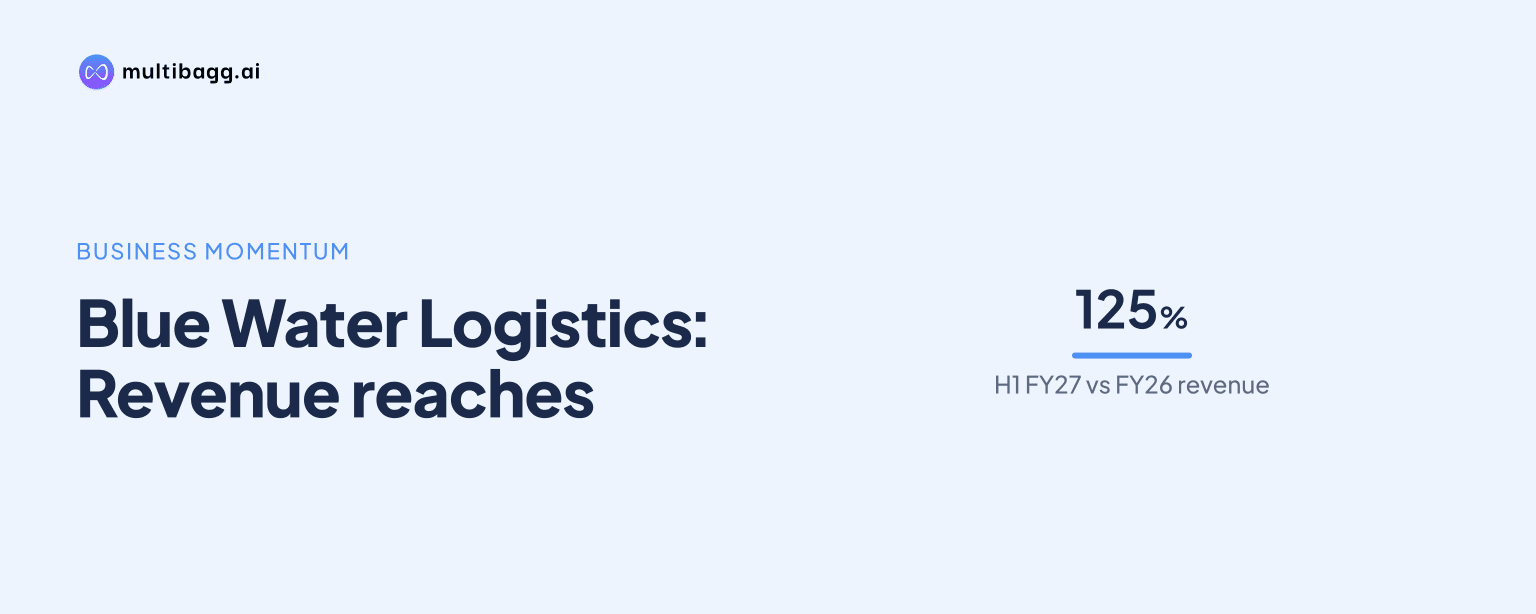
Blue Water Logistics Limited reported Rs 483.3 crore of revenue from operations in H1 FY27, equal to 125.2% of its Rs 386 crore FY26 revenue, after Q2 FY27 EBITDA margin rose to 13% from 10.3%. Higher freight volumes and fixed-cost operating leverage drove the result, management said on November 12, 2026.
Know Blue Water Logistics inside out
Results, valuation, peers and who's buying, in one view.
What drove Blue Water Logistics' H1 FY27 revenue growth?
Blue Water Logistics' H1 FY27 revenue from operations increased 249.5% year on year to Rs 483.3 crore from Rs 138.3 crore in H1 FY26. Q2 FY27 revenue was Rs 272.1 crore, up 211.2% from Rs 87.42 crore in Q2 FY26, and management described it as the company's highest revenue-generating quarter since listing.
Higher freight activity across three services underpinned the increase. Ocean freight volume reached 6,820 twenty-foot equivalent units, or TEUs, in Q2 FY27, up 148% from 2,750 TEUs in Q2 FY26 and 18% from Q1 FY27. Air freight volume rose to 1,201 tonnes from 250 tonnes, while non-vessel-operating common carrier, or NVOCC, volume rose 113% year on year and 21% sequentially to 1,595 TEUs.
Customer additions and the ramp-up of newer branches also supported Q2 FY27 volumes, according to management. The company named Atul Limited, RDB Liners, Indus Petrochem Limited, Anupam Rasayan India Limited, Vacmet India Limited and Hindustan National Glass and Industries Limited among customers added during the quarter.
How did Blue Water Logistics expand Q2 FY27 margins?
Blue Water Logistics expanded Q2 FY27 earnings before interest, tax, depreciation and amortisation, or EBITDA, margin by 270 basis points to 13% from 10.3% in Q2 FY26. EBITDA rose 292.0% year on year to Rs 35.4 crore, while profit after tax increased 213.8% to Rs 16 crore from Rs 5.1 crore.
Management attributed the margin movement to operating leverage from higher sales volumes over the previous three months. Managing Director Lalit Panda said staff and office costs were fixed, so increased sales raised profitability. He said management intended to continue improving margins, but the call also stated that forward-looking statements involve risks and actual results could differ.
The first-half comparison showed a smaller margin expansion than Q2. H1 FY27 EBITDA was Rs 59 crore, up 278.4% year on year, and its margin rose 90 basis points to 12.2% from 11.3% in H1 FY26. H1 profit after tax increased 247.4% to Rs 30 crore from Rs 8.6 crore, while the profit-after-tax margin remained at 6.2%.
Got a follow-up? Ask IRIS
Which Blue Water Logistics operations supported the revenue increase?
Blue Water Logistics' ocean freight business remained its largest H1 FY27 revenue source, accounting for 67.9% of revenue, followed by air freight at 20.3% and NVOCC at 8.2%. Surface and railway freight contributed 3.0%, while customs house clearance contributed 0.6%, showing that ocean freight remained the principal business despite faster growth in air cargo and NVOCC volumes.
Blue Water Logistics began its dry-container NVOCC division in Q2 FY27 with an initial fleet of up to 2,000 dry-container boxes, equivalent to 3,000-plus TEUs. Management said the operation extends its NVOCC business from specialised liquid cargo handled through ISO tank containers into general containerised freight, and expects the division to ramp up during H2 FY27.
As of H1 FY27, Blue Water Logistics had 1,708-plus ISO tank containers, 150-plus container trailers and 3,000 TEUs of dry containers. During Q2 FY27, it established an associate company in Thailand, incorporated BWL East Africa Limited in Tanzania and Blue Water Logistics Vietnam Company Limited as a wholly owned subsidiary, and opened an Indonesia branch alongside its existing Dubai branch.
Management said the overseas network could enable the company to originate and control cargo at both ends of key trade lanes rather than rely entirely on overseas agents. Its stated remainder-of-FY27 plan includes operationalising the Thailand, Tanzania and Vietnam entities, progressing Indonesia, Malaysia and China, adding airline partnerships, and entering project cargo.
What is Blue Water Logistics expecting in H2 FY27?
Blue Water Logistics expects H2 FY27 revenue to exceed H1 FY27 revenue because management said the second half is normally better than the first half for its industry. Panda did not provide a revised forecast and said more precise commentary could be given with the next quarterly results.
At the beginning of FY27, management had indicated revenue of about Rs 650 crore to Rs 700 crore for the full year and said on the call that it was almost on track to achieve that level. Management also said it would seek sequential growth, although Panda said quarterly outcomes would depend on market conditions and orders held by exporters and importers.
External shipping conditions remained a disclosed variable in Q2 FY27. Management said geopolitical tensions in West Asia, disruption in the Strait of Hormuz and Red Sea corridor, and elevated fuel costs affected routes, transit times and operating expenses across ocean and air freight. It said container freight surges moderated in the middle of the quarter but remained significantly above the prior-year period at the end of September 2026.
Management cited global air-cargo volume growth of 7.7% year on year in September 2026, based on International Air Transport Association data. It also cited Indian merchandise exports of USD259.89 billion in H1 FY27, up 18.5%, and major-port cargo of 472.75 million tonnes, up 8%, as indicators of trade activity relevant to the logistics sector.
Conclusion
Blue Water Logistics' Rs 483.3 crore H1 FY27 revenue exceeded its Rs 386 crore FY26 revenue base, while Q2 EBITDA margin reached 13% as higher ocean, air and NVOCC volumes spread fixed staff and office costs. Ocean freight, at 67.9% of H1 revenue, remained the largest contributor even as air freight accounted for 20.3% and NVOCC accounted for 8.2%.
The next quarterly result is the key scheduled update, as management said it could then provide more precision on H2 FY27 performance. The disclosed execution points to watch are the H2 ramp-up of the 3,000-TEU dry-container fleet, operational progress in Thailand, Tanzania and Vietnam, airline partnerships, and the effect of Red Sea and Strait of Hormuz conditions on costs and transit times.