










Bodal Chemicals says Saykha unit added revenue in H1FY27
Key highlights
- Bodal Chemicals reported H1FY27 consolidated revenue of Rs 1,599.1 crore, up 67% year on year.
- Bodal Chemicals said the Saykha benzene downstream products division began contributing to revenue in H1FY27.
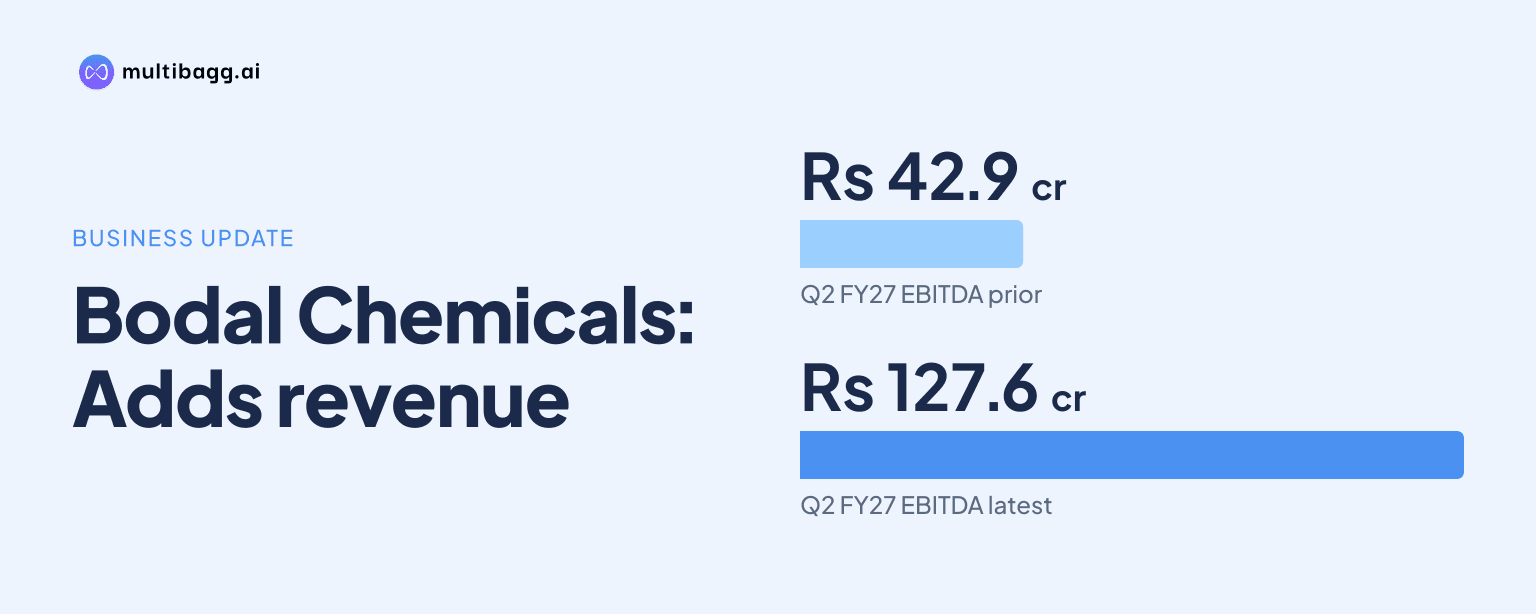
- Bodal Chemicals' Q2FY27 EBITDA rose to Rs 127.6 crore from Rs 42.9 crore, and margin increased to 14.4%.
- Bodal Chemicals' Q2FY27 dye-intermediates revenue was Rs 344.9 crore, up 88% year on year.
powered by IRIS
Bodal Chemicals Limited said its Saykha benzene downstream products division began contributing to revenue in H1FY27, when consolidated revenue reached Rs 1,599.1 crore, 67% higher year on year. Management said better realisations and volumes could make the division’s contribution meaningful quarter on quarter, without quantifying the new division’s sales.
Know Bodal Chemicals inside out
Results, valuation, peers and who's buying, in one view.
What did Bodal Chemicals report about the Saykha division?
Bodal Chemicals reported that its benzene downstream products division at Saykha started contributing to revenue during H1FY27. The presentation does not disclose the division’s revenue, production volume, capacity utilisation, margin, customer base or the date within H1FY27 when sales began.
Management said recent better realisations and improved volume would lead to meaningful contribution on a quarter-on-quarter basis. This is a management expectation rather than quantified guidance because Bodal Chemicals provided no sales, earnings before interest, tax, depreciation and amortisation (EBITDA), or profitability target for the Saykha division.
The Saykha update came in a half year when Bodal Chemicals reported all-time-high consolidated revenue of Rs 1,599.1 crore and EBITDA of Rs 202.7 crore. The company attributed the wider H1FY27 result to better realisations and volume across divisions, margins in key dye intermediates, and the pass-through of higher raw-material costs.
How did Bodal Chemicals' H1FY27 financial performance change?
Bodal Chemicals' consolidated revenue rose to Rs 1,599.1 crore in H1FY27 from Rs 958.6 crore in H1FY26, while EBITDA increased to Rs 202.7 crore from Rs 94.6 crore. The company reported 67% year-on-year revenue growth and 114% growth in absolute EBITDA for the half year.
Profit after tax, or PAT, increased to Rs 111.8 crore from Rs 15.5 crore, while PAT margin rose to 7.0% from 1.6%. Bodal Chemicals did not allocate any part of this H1FY27 improvement to Saykha, so the financial contribution of the benzene downstream division cannot be calculated from the presentation.
Q2FY27 growth was higher than the H1FY27 rate on the reported comparisons. Revenue was Rs 884 crore against Rs 500.4 crore in Q2FY26, EBITDA was Rs 127.6 crore against Rs 42.9 crore, and PAT was Rs 81.4 crore against Rs 6 crore; EBITDA margin rose to 14.4% from 8.6%.
Which Bodal Chemicals businesses drove reported revenue growth?
Bodal Chemicals said dye intermediates led the H1FY27 outcome, with divisional revenue up 68% year on year, supported by volume and margin. In Q2FY27, dye intermediates revenue was Rs 344.9 crore, up 88% from Rs 183.4 crore in Q2FY26, the highest revenue among the four reported business categories.
Dyestuff revenue rose 60% to Rs 211.5 crore in Q2FY27 from Rs 132.2 crore a year earlier. Basic Chemicals revenue increased 199% to Rs 99 crore from Rs 33.1 crore, while Bodal Chemicals attributed the division’s H1FY27 growth of 136% mainly to higher sulphur prices.
Chlor Alkali revenue increased by 8% to Rs 90.8 crore in Q2FY27, although standalone caustic-soda production volume fell to 20,123 metric tonnes from 20,332 metric tonnes in Q2FY26. The presentation therefore shows higher reported quarterly revenue alongside lower reported caustic-soda output for that business.
Got a follow-up? Ask IRIS
How did Bodal Chemicals' sales mix and production volumes shift?
Bodal Chemicals' Basic Chemicals share of product sales increased to 12% in H1FY27 from 8% in H1FY26, based on consolidated product sales excluding other non-operating income. The applicable product-sales base increased to Rs 1,544.2 crore from Rs 916.6 crore over the same periods.
Dye intermediates remained the largest product-sales category at 36% in H1FY27, compared with 37% in H1FY26. Dyestuff fell to 23% from 28%, caustic soda declined to 12% from 18%, and Others increased to 17% from 9%; these proportions differ from total consolidated revenue because the sales-mix calculation excludes other non-operating income.
Standalone production volumes rose in dye intermediates and dyestuff but declined in Basic Chemicals and caustic soda during H1FY27. Dye-intermediates output increased to 16,956 metric tonnes from 14,727 metric tonnes and dyestuff output rose to 9,056 metric tonnes from 7,834 metric tonnes.
Basic Chemicals output was 113,312 metric tonnes in H1FY27, down from 115,248 metric tonnes, while caustic-soda output decreased to 38,886 metric tonnes from 40,889 metric tonnes. Bodal Chemicals states that production data are standalone because subsidiary information is limited, whereas the revenue breakup is consolidated.
What does Bodal Chemicals say could affect the next quarters?
Bodal Chemicals said better realisations, improved volumes and stabilisation of the benzene downstream products plant could support a better run in coming quarters. Management also cited structural changes in China as part of its expectation, while providing no financial target or stated timetable for Saykha's stabilisation.
The current group-level reference point is Q2FY27 revenue of Rs 884 crore, EBITDA of Rs 127.6 crore and a 14.4% EBITDA margin. Bodal Chemicals has not disclosed separate Saykha revenue, operating cost, EBITDA or utilisation data, so its effect on those measures remains unspecified.
Bodal Chemicals said integrated manufacturing capacity, raw-material cost pass-through, higher volumes and dye-intermediates performance supported Q2FY27 results. It also said the Senor Beya-Turkish, Chinese and BCTPL subsidiaries performed overall satisfactorily during Q2FY27, without providing separate financial figures.
Conclusion
Bodal Chemicals has confirmed an operational milestone at Saykha: the benzene downstream products division began contributing to revenue in H1FY27. However, the presentation does not quantify that contribution, and the reported financial improvement remains attributable at group level to realisations, volumes, dye-intermediates margins and raw-material cost pass-through.
The next disclosure to watch is whether Bodal Chemicals reports separate Saykha sales, production, utilisation or profitability as management seeks meaningful quarter-on-quarter contribution. Management has identified improved realisations, higher volumes and plant stabilisation as the stated basis for further progress, while Q2FY27 EBITDA margin of 14.4% is the available consolidated benchmark.