










Bodal FY26 profit recovery still trails FY22 return levels
Key highlights
- Bodal’s FY26 revenue was Rs 2,053.9 crore, up from Rs 1,419.4 crore in FY24.
- Bodal’s FY26 profit after tax rose to Rs 47.8 crore from Rs 6.5 crore in FY24.
- Bodal’s FY26 ROE was 4.1%, compared with 9.4% in FY22.
- Bodal’s net working-capital days fell to 104.8 in FY26 from 164.8 in FY22.
powered by IRIS
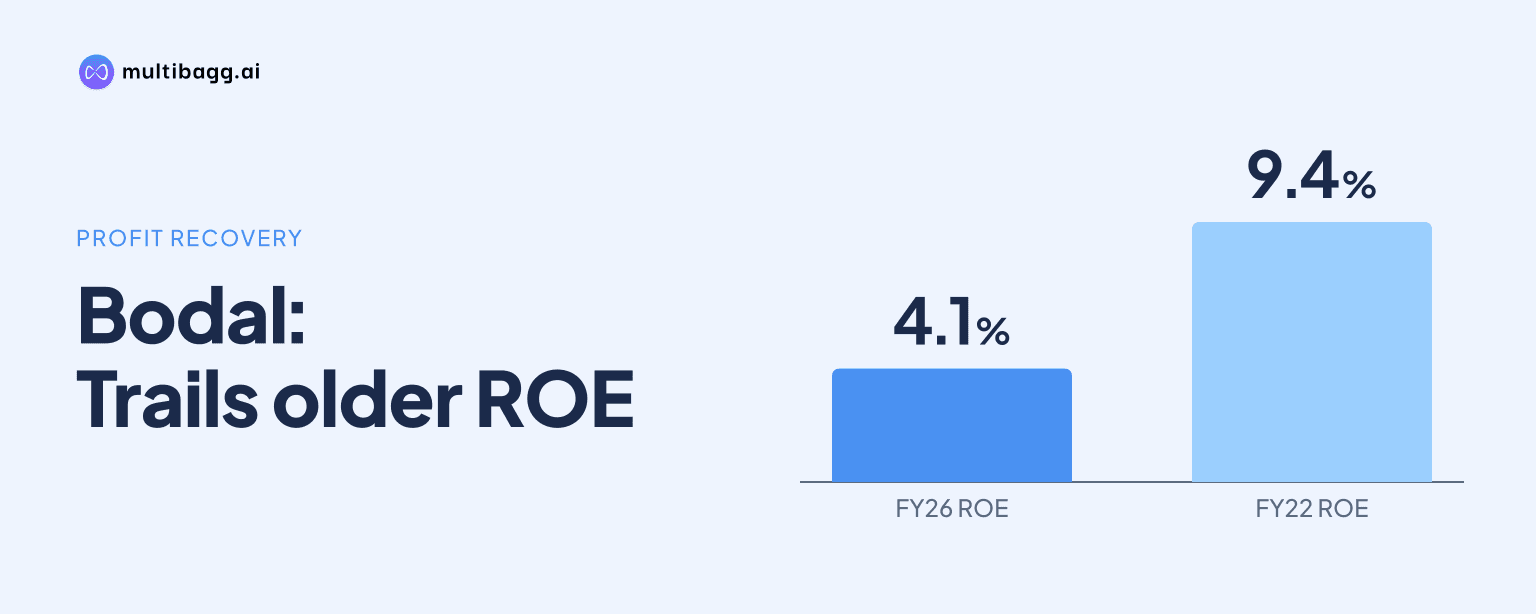
Bodal Chemicals Ltd. recovered FY26 profit after tax to Rs 47.8 crore from Rs 6.5 crore in FY24, but its 4.1% return on equity remained below the 9.4% reported in FY22. Revenue reached Rs 2,053.9 crore in FY26, near the restated FY22 level of Rs 2,072.4 crore, while EBITDA and capital returns remained lower.
Know Bodal Chemicals inside out
Results, valuation, peers and who's buying, in one view.
How much did Bodal’s financial performance recover by FY26?
Bodal’s FY26 revenue, earnings before interest, tax, depreciation and amortisation (EBITDA), and profit after tax all rose from their FY24 levels, although EBITDA and profit remained below FY22. Consolidated revenue increased by Rs 634.5 crore from FY24 to Rs 2,053.9 crore in FY26, while EBITDA rose by Rs 83.3 crore to Rs 202.8 crore and profit after tax increased by Rs 41.3 crore to Rs 47.8 crore.
The recovery extended over FY25 and FY26 after the FY24 low point. Revenue rose from Rs 1,419.4 crore in FY24 to Rs 1,756.7 crore in FY25 and Rs 2,053.9 crore in FY26, while profit after tax moved from Rs 6.5 crore to Rs 18.5 crore and then Rs 47.8 crore. FY26 revenue was Rs 18.5 crore below FY22, whereas EBITDA was Rs 34.1 crore lower and profit after tax was Rs 50.9 crore lower.
Have Bodal’s margins returned to FY22 levels?
Bodal’s FY26 EBITDA margin was 9.9% and its profit-after-tax margin was 2.3%, both above FY24 but below FY22. EBITDA margin rose 1.5 percentage points from 8.4% in FY24, and profit-after-tax margin increased 1.8 percentage points from 0.5%. The margin data are reported on a consolidated basis, and revenue includes other income.
The FY26 EBITDA margin remained 1.5 percentage points below the 11.4% recorded in FY22, while the profit-after-tax margin was 2.5 percentage points below the FY22 level of 4.8%. EBITDA margin was 9.1% in FY23 and 9.7% in FY25. Profit-after-tax margin was 2.4% in FY23 before falling to 1.1% in FY25, showing that the recovery in reported profitability did not move in a straight line.
How far are Bodal’s FY26 returns below FY22?
Bodal’s return on equity (ROE) was 4.1% in FY26 and return on capital employed (ROCE) was 8.9%, compared with 9.4% and 15.0%, respectively, in FY22. ROE improved from 0.6% in FY24, while ROCE rose from 3.9%. Even after those gains, ROE was 5.3 percentage points and ROCE 6.1 percentage points below their FY22 readings.
The other disclosed efficiency measures improved from FY24. Net debt to equity declined to 0.67 times in FY26 from 0.80 times in FY24, though it remained above the FY22 level of 0.63 times. Net working-capital days fell to 104.8 in FY26 from 137.2 in FY24 and 164.8 in FY22, alongside the recovery in EBITDA from Rs 119.5 crore to Rs 202.8 crore.
Got a follow-up? Ask IRIS
Which Bodal segments led the FY26 revenue recovery?
Bodal’s dye intermediates business reported the largest FY26 revenue among the four disclosed segments, at Rs 709.7 crore. Dyestuffs generated Rs 529.4 crore, chlor alkali generated Rs 338.7 crore and basic chemicals generated Rs 165.5 crore. The presentation describes these figures as a revenue breakup and states that revenue includes other income.
Basic chemicals recorded the largest increase from FY24 among the disclosed revenue lines, rising by Rs 82.8 crore from Rs 82.7 crore to Rs 165.5 crore in FY26. Dye intermediates rose by Rs 218.7 crore from Rs 491 crore, compared with increases of Rs 58.9 crore for dyestuffs and Rs 70.2 crore for chlor alkali. Against FY22, FY26 revenue remained below the earlier levels in basic chemicals, dyestuffs and dye intermediates, while chlor alkali rose from Rs 258.7 crore to Rs 338.7 crore.
Did Bodal’s production volumes rise with segment revenue?
Bodal’s dye-intermediates production reached 30,877 metric tonnes in FY26, above 24,833 metric tonnes in FY24 and 25,985 metric tonnes in FY22. Dyestuffs production also increased to 16,834 metric tonnes from 14,209 metric tonnes in FY24, but remained below the FY22 volume of 20,058 metric tonnes. The presentation identifies the production data as standalone rather than consolidated.
Basic-chemical production, including thionyl chloride, was 216,196 metric tonnes in FY26, compared with 210,129 metric tonnes in FY24 and 225,908 metric tonnes in FY22. Chlor-alkali production, defined as caustic soda only, declined to 81,014 metric tonnes in FY26 from 85,501 metric tonnes in FY25, although it was above 79,027 metric tonnes in FY24. FY22 financial figures were restated following the amalgamation of SPS Processors Pvt. Ltd., providing the stated base for the five-year financial comparison.
Conclusion
Bodal’s FY26 data show a recovery from the FY24 trough in revenue, EBITDA, profit after tax and margins. Revenue of Rs 2,053.9 crore approached the restated FY22 amount of Rs 2,072.4 crore, but EBITDA of Rs 202.8 crore and profit after tax of Rs 47.8 crore remained below FY22 levels of Rs 236.9 crore and Rs 98.7 crore. The remaining gap is also reflected in FY26 ROE of 4.1% and ROCE of 8.9%.
The next reported periods will indicate whether lower net working-capital days of 104.8 and net debt to equity of 0.67 times support further improvement in profit and returns. The presentation does not disclose a future ROE or ROCE target, leaving the pace at which returns can move toward FY22 levels unresolved.