










Capital Infra Trust targets 60% leverage, Rs 2,500 crore capacity
Key highlights
- Capital Infra Trust plans to keep leverage near 60%, below the 70% level management cited.
- Management said Capital Infra Trust has Rs 2,000 crore to Rs 2,500 crore of debt-only acquisition capacity.
- Capital Infra Trust expects its post-acquisition net borrowing ratio to be around 45%.
- Capital Infra Trust’s sponsor ROFO pipeline includes 12 projects with BPC of around Rs 15,500 crore.
powered by IRIS
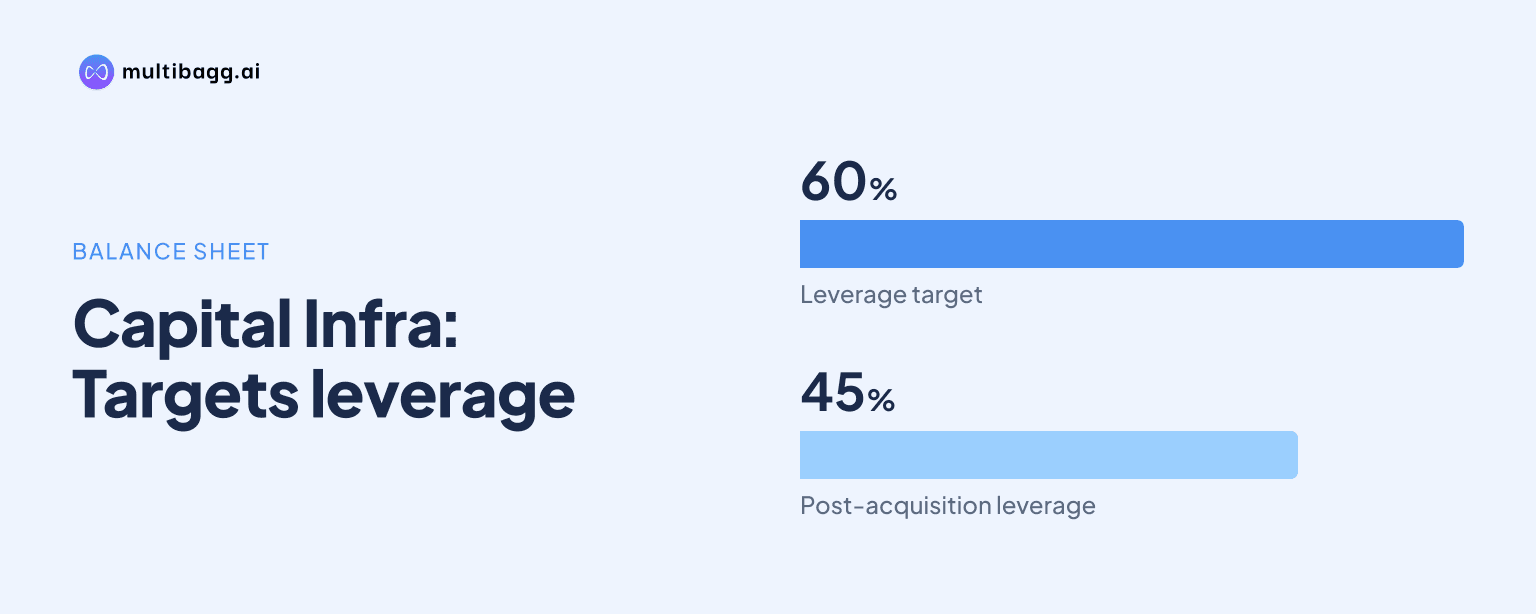
Capital Infra Trust said in its September 2026 quarter call that it plans to keep leverage near 60%, giving it capacity to acquire up to Rs 2,500 crore of assets with debt alone after its post-acquisition net borrowing ratio is expected to reach about 45%. Management said the level remains below the 70% limit it cited.
Know Capital Infra Trust inside out
Results, valuation, peers and who's buying, in one view.
Why is Capital Infra Trust targeting leverage near 60%?
Capital Infra Trust is targeting leverage near 60% to fund acquisitions while retaining room below the 70% level management said it can reach. Management identified leverage headroom as one of three factors supporting acquisition-led growth over the next three years, alongside the sponsor right-of-first-offer pipeline and third-party opportunities. The target is a management preference rather than an intention to use the full permitted level.
The Trust reported consolidated net debt to enterprise value of 40.3% as of September 2026 and expects the net borrowing ratio to be around 45% after six acquisitions. Management said a 57.5% net borrowing ratio could support approximately Rs 2,500 crore of incremental assets funded solely through debt. That leaves a cushion to the stated 60% operating level and the 70% ceiling cited on the call.
How much debt-only acquisition capacity does Capital Infra Trust have?
Capital Infra Trust said it has debt-only acquisition capacity of Rs 2,000 crore to Rs 2,500 crore before a further equity raise. Management said it intends to use this leverage headroom to purchase assets and then seek the next round of equity capital. It also said that no binding agreement for a third-party asset had been signed at the time of the call.
Management’s broader ambition is to add at least Rs 3,000 crore to Rs 3,500 crore of assets by the end of the next financial year, beyond the portfolio then held. This means debt capacity alone would not necessarily fund the full target. Following the six assets acquired after September, management said assets under management would reach about Rs 9,400 crore.
Which assets could Capital Infra Trust acquire next?
Capital Infra Trust plans to acquire sponsor right-of-first-offer, or ROFO, projects and selectively pursue third-party operational assets. The sponsor ROFO pipeline comprised 12 projects with balance project cost, or BPC, of around Rs 15,500 crore, maturing over the next three to four years. Management said two sponsor ROFO assets worth around Rs 1,250 crore could be ready for acquisition in the first quarter of the next financial year.
The Trust said it will remain focused on hybrid annuity model, or HAM, road assets in the short to medium term. Management said it has visibility to acquire Rs 3,000 crore to Rs 3,500 crore of assets annually for the next three years from the available road-sector pipeline. It said toll-operate-transfer, or TOT, assets or other sectors may be considered once assets under management reach around Rs 20,000 crore.
Got a follow-up? Ask IRIS
How has Capital Infra Trust funded its recent acquisitions?
Capital Infra Trust raised Rs 125 crore through a preferential issue in September and Rs 1,115 crore through a qualified institutional placement, or QIP, in October. Management said the Rs 1,240 crore of equity, together with approximately Rs 1,540 crore of debt, supported the six asset acquisitions. The capital raises were intended to broaden the equity base before the Trust uses additional leverage for future purchases.
As of September 2026, 42% of borrowings were fixed rate and 58% were floating rate, while the effective annualised borrowing cost was 7.3%. The Trust reported a debt service coverage ratio, or DSCR, of 2.27 times and an AAA stable credit rating. Management said debt-funded acquisitions of around Rs 2,500 crore would remain within regulations and lender covenants.
What supports Capital Infra Trust’s cash flows and distributions?
Capital Infra Trust invests in completed HAM road projects that receive quarterly annuity payments from the National Highways Authority of India, or NHAI. Management said the receipts include an interest-rate component linked to the Reserve Bank of India bank rate. Operating and maintenance work is contracted to the sponsor, which is also the project manager, at a fixed annual price set when each asset is acquired.
In Q2 FY27, special purpose vehicle-level operating cash flow was Rs 285.1 crore and net distributable cash flow at Trust level was Rs 161.2 crore. The board-approved distribution was Rs 150.95 crore, leaving Rs 10.25 crore retained by the Trust. Five of six annuities due in the quarter, worth Rs 186.33 crore, were received during Q2 FY27, while the remaining Rs 40.89 crore was received in October 2026.
Management said project operating expenses are fixed for the financial year and increase 5% annually. It said expenses appearing higher in Q2 FY27 reflected change-of-scope items and pending engineering, procurement and construction payments associated with recently acquired projects, rather than a quarter-on-quarter increase in fixed operating and maintenance costs. The Trust said its next quarterly results should provide a clearer view of the full 18-asset portfolio.
Conclusion
Capital Infra Trust’s stated financing plan is to use debt capacity before returning to the equity market, with a leverage preference near 60% and estimated debt-only acquisition room of Rs 2,000 crore to Rs 2,500 crore. The approach follows capital raises of Rs 1,240 crore of equity and approximately Rs 1,540 crore of debt for six acquisitions, while management expects the post-acquisition net borrowing ratio to be about 45%.
Investors will next watch whether the two sponsor ROFO assets valued at around Rs 1,250 crore become available in the first quarter of the next financial year, and whether a third-party transaction reaches a binding stage. Management also said it expects 50 to 75 basis points of further bank-rate increases over the next nine to 12 months, subject to Indian and global macroeconomic conditions.