










Capri Global targets Rs 65,000 crore AUM by FY28 on 28%-30% CAGR plan
Key highlights
- Capri Global targets Rs 65,000 crore of AUM by FY28 and more than Rs 1,25,000 crore by FY31.
- Capri Global reported Q2 FY27 AUM of Rs 43,878 crore, up 62% year on year.
- Capri Global plans to open 750-800 branches over the next two years from 1,609 operational branches in Q2 FY27.
- Capri Global targets RoAE of 19.0%-21.0% and RoAA of 4.2%-4.7%.
powered by IRIS
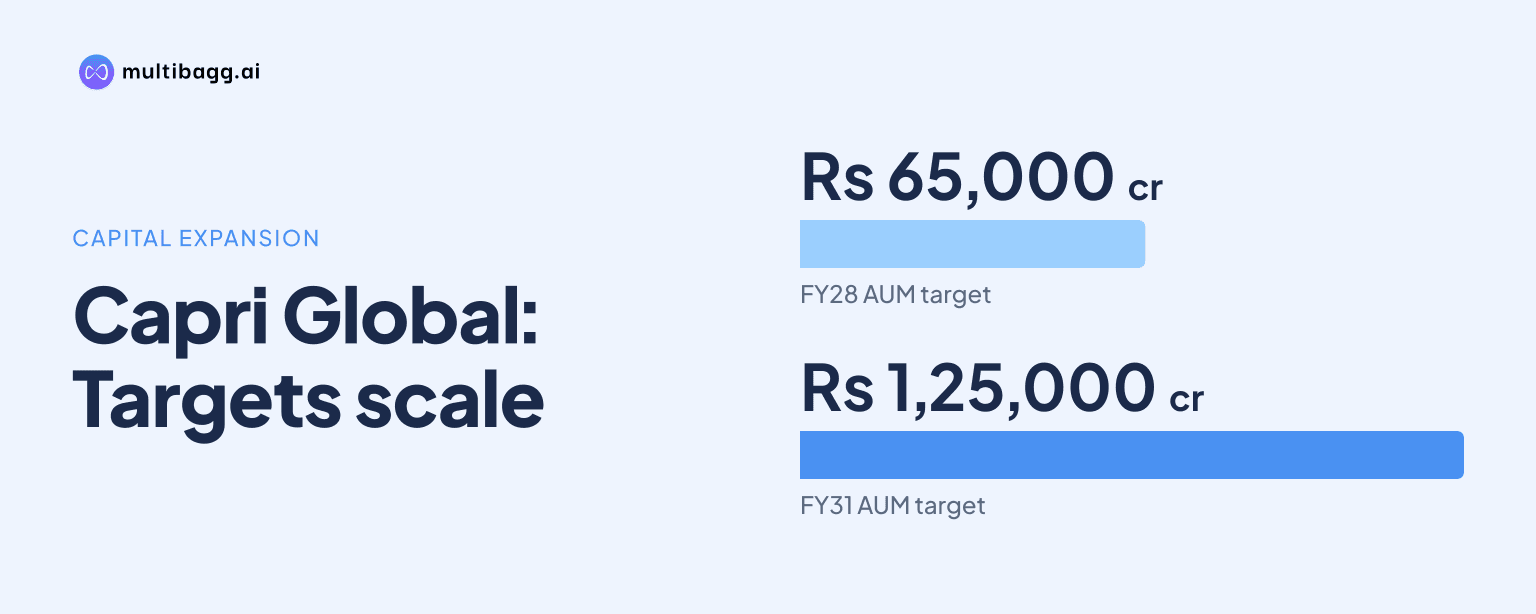
Capri Global targets Rs 65,000 crore of assets under management (AUM) by financial year 2028 (FY28), with a goal of more than Rs 1,25,000 crore by FY31, and says the plan requires 28%-30% compound annual growth. The Q2 FY27 starting base was Rs 43,878 crore, while management plans 750-800 new branches over two years.
Know Capri Global Capital inside out
Results, valuation, peers and who's buying, in one view.
How large are Capri Global’s AUM targets?
Capri Global’s stated target is Rs 65,000 crore of AUM by FY28 and more than Rs 1,25,000 crore by FY31. Management presents the two milestones as requiring a 28%-30% compound annual growth rate (CAGR) across the target period. The FY31 objective is more than Rs 60,000 crore above the FY28 target, because the later target is stated as exceeding Rs 1,25,000 crore rather than equalling it.
The targets follow reported Q2 FY27 AUM of Rs 43,878 crore, compared with Rs 27,040 crore in Q2 FY26, a 62% year-on-year increase. Reaching Rs 65,000 crore would add Rs 21,122 crore from the Q2 FY27 reported base. The presentation also reports consolidated AUM growth at a 52% CAGR from FY22 to Q2 FY27, when AUM rose from Rs 6,634.7 crore to Rs 43,878 crore.
Which lending segments are expected to support Capri Global’s expansion?
Capri Global identifies micro, small and medium enterprise (MSME) loans, micro loans against property (Micro LAP), affordable housing loans and gold loans as focus segments. Its MSME AUM definition includes MSME, Micro LAP and solar loans. The presentation also says MSME, gold and housing AUM figures include co-lending and directly assigned AUM.
Gold was Capri Global’s largest reported AUM segment at Rs 21,003.8 crore in Q2 FY27, followed by housing at Rs 8,325.3 crore, construction finance at Rs 7,502.8 crore and MSME at Rs 7,015.5 crore. Gold AUM rose from Rs 16,964.6 crore in FY26, while construction-finance AUM increased from Rs 5,708.1 crore. MSME AUM rose from Rs 6,485.9 crore in FY26.
The reported long-term growth rates differ by product. Total AUM recorded a 52% CAGR from FY22 to Q2 FY27, while construction finance recorded 49%, housing 41% and MSME 18%. Gold AUM recorded a 131% CAGR from FY23 to Q2 FY27, which is the distinct measurement period specified in the presentation. Management’s return framework cites a higher share of high-yield products as a margin-expansion lever.
How will Capri Global add branches and enter new markets?
Capri Global plans to add 750-800 branches over the next two years, expanding in existing and new states. The presentation names Telangana, Karnataka, Tamil Nadu, Andhra Pradesh, Odisha and Uttar Pradesh as intended geographies. This expansion follows an operating network of 1,609 branches as of Q2 FY27.
The planned additions would equal approximately 47%-50% of the Q2 FY27 network of 1,609 branches, based on the disclosed range. Management does not disclose a branch-by-branch allocation or annual opening schedule. It says the expanded network is intended to deepen presence, while growth opportunities include new markets, customer segments and partnerships.
Capri Global reports that more than 85% of its loan book is retail and that 100% is secured. Its Q2 FY27 summary reports a yield of 17.5%, spread of 8.3% and net interest margin (NIM) of 9.6%. The presentation links branch growth to underserved high-growth markets and customised products, but gives no separate market-share target for the six named states.
Got a follow-up? Ask IRIS
What technology and funding actions support Capri Global’s target?
Capri Global plans to use agentic artificial intelligence (AI) tools to improve cost efficiency, productivity and customer experience, with particular emphasis on sales productivity across MSME, housing and gold products. The company says it has a dedicated technology centre with more than 150 engineers and data scientists, alongside internally developed applications supporting end-to-end digital processes.
The productivity plan is paired with operating leverage from the existing network, according to the return framework. Operating expenses rose 33% year on year to Rs 449.2 crore in Q2 FY27, while operating profit increased 84% to Rs 636.3 crore. Over the same comparison, the cost-income ratio declined to 41.4% from 49.4%, a reduction of 807 basis points, where 100 basis points equal one percentage point.
On liabilities, Capri Global plans to diversify borrowings through non-convertible debentures (NCDs) and commercial paper (CP), widen its lender base and reduce its cost of funds. It also plans to strengthen co-lending partnerships. As of Q2 FY27, it reported more than 40 lenders and 11 co-lending partners, with co-lending accounting for 21% of AUM, and stated that there was no asset-liability management mismatch.
What return targets has Capri Global set?
Capri Global targets consistent return on average equity (RoAE) of 19.0%-21.0% and return on average assets (RoAA) of 4.2%-4.7%. Management’s stated levers are AUM growth, a higher share of high-yield products, co-lending-led liability management, fee income, cost efficiency and lower credit costs through data science and analytics.
Reported Q2 FY27 returns were within or above parts of those stated ranges: RoAE was 21.6%, compared with 14.4% in Q2 FY26, while RoAA was 4.4%, compared with 4.0%. For H1 FY27, RoAE was 20.4% and RoAA was 4.2%, compared with 15.0% and 3.6%, respectively, in H1 FY26. These are reported period measures, while the presentation describes the stated ranges as targets for consistent delivery.
Capri Global plans to generate more fee income through cross-selling and by scaling insurance, car-loan distribution and other new verticals. Non-interest income increased 34% year on year to Rs 273 crore in Q2 FY27, while net interest income rose 69% to Rs 812.5 crore. The company says it launched and scaled four products over the last five years: gold loans, Micro LAP, car-loan origination and insurance distribution.
Conclusion
Capri Global’s FY28 and FY31 AUM milestones depend on continued growth across gold, housing, construction finance and MSME-related lending while materially extending its distribution network. The reported Q2 FY27 base of Rs 43,878 crore, 62% above Q2 FY26, provides the starting point, while the plan combines branch additions, technology, co-lending, borrowing diversification and cross-selling rather than relying on one product alone.
The next disclosed execution marker is the planned addition of 750-800 branches over two years, including expansion across six named states. Investors can also watch whether Capri Global maintains progress toward management’s 19.0%-21.0% RoAE and 4.2%-4.7% RoAA targets as it increases high-yield product share, expands insurance and car-loan distribution, and develops funding partnerships.