










Capri Loans insurance premium rises 43% to Rs 143.4 crore
Key highlights
- Capri Loans reported H1FY27 insurance premium of Rs 143.4 crore, up 43% from Rs 100.4 crore in H1FY26.
- Capri Loans has partnerships with 23 insurers: nine life, 10 general and four health companies.
- Direct sales accounted for 65% of Capri Loans' Rs 78.2 crore Q2FY27 insurance premium mix.
- Health and wellness represented 56% of Capri Loans' Q2FY27 insurance premium by insurance type.
powered by IRIS
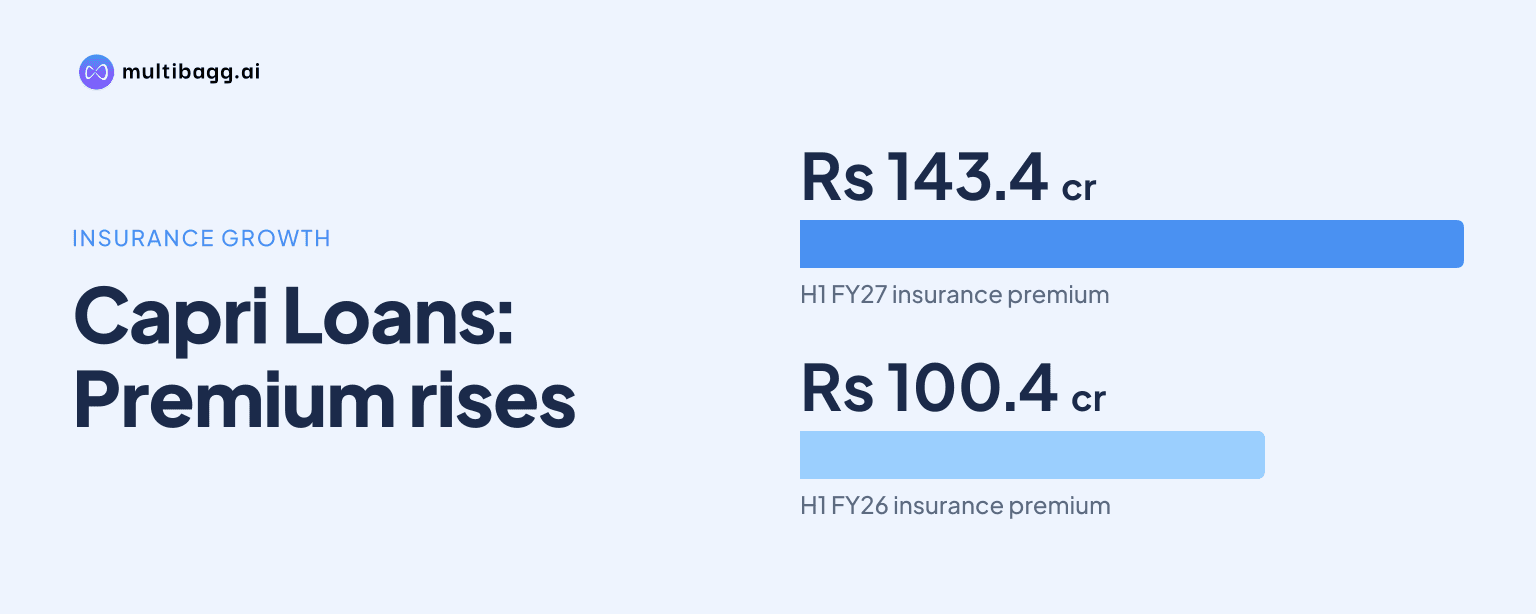
Capri Loans reported total insurance premium of Rs 143.4 crore in H1FY27, up 43% from Rs 100.4 crore in H1FY26, while operating an asset-light insurance-distribution model with 23 insurance-company partnerships, embedded loan-customer product offerings and real-time digital policy issuance.
Know Capri Global Capital inside out
Results, valuation, peers and who's buying, in one view.
What happened to Capri Loans' insurance premium in H1FY27?
Capri Loans' total insurance premium rose by Rs 43 crore year on year to Rs 143.4 crore in H1FY27. The presentation reports Rs 100.4 crore of total premium in H1FY26 and labels the change as a 43% increase. It describes insurance distribution as an asset-light income stream, positioning the business separately from Capri Loans' lending portfolio.
The comparison is based on total premium, not on disclosed commission income, net fee income or profitability. Capri Loans does not provide a premium split by insurer, product, geography or distribution channel for either H1FY26 or H1FY27. The disclosed evidence therefore establishes growth in premium placed through the platform but does not quantify the earnings retained from that premium.
The H1FY27 result follows a Q2FY27 premium snapshot of Rs 78.2 crore across the product, insurance-type and channel statistics shown in the presentation. That quarterly figure is not labelled as a comparable H1 measure, so it should not be added to or compared directly with the H1FY27 total. It does, however, show how the business was distributed by premium during Q2FY27.
How is Capri Loans' insurance distribution business structured?
Capri Loans distributes insurance through partnerships with 23 insurance companies: nine life insurers, 10 general insurers and four health insurers. The life-insurance offering includes life insurance, credit life cover and term plans, while the general-insurance offering includes property cover and private-car and two-wheeler products.
The four health-insurance partnerships support retail and group-health products, hospital daily cash, critical illness, personal accident and EMI Protect products. Critical illness and personal accident are identified in the presentation as CI and PA, respectively. The insurer mix gives Capri Loans products across life, general and health categories rather than a single-product distribution model.
Capri Loans' customer-sourcing approach includes offering insurance as an embedded product to loan customers. The presentation also identifies cross-selling health and motor insurance as a route to expand penetration in Tier II, III and IV cities and rural areas. This links insurance distribution to the loan-customer journey while also allowing products to be sold through channels beyond loan-linked cross-sell.
What did Capri Loans' Q2FY27 insurance mix look like?
Capri Loans' Q2FY27 premium mix was 65% direct and 35% cross-sell, based on the Rs 78.2 crore premium statistics shown in the presentation. The direct share was therefore larger than the cross-sell share by 30 percentage points. The source labels these figures as statistics by premium for Q2FY27 rather than as customer counts or policy counts.
By loan or product association, housing accounted for 36% of Q2FY27 premium, MSME accounted for 32%, gold accounted for 26% and other categories made up 6%. Housing was the largest disclosed category, exceeding MSME by four percentage points and gold by 10 percentage points. The presentation specifies that these shares are measured by premium.
Health and wellness represented 56% of Q2FY27 premium by insurance type, compared with 24% for life and 20% for general insurance. Health and wellness was therefore the largest insurance-type category, with a 32-percentage-point lead over life insurance. This type mix sits alongside the 23-company partnership structure, which contains 10 general insurers, nine life insurers and four health insurers.
Got a follow-up? Ask IRIS
What digital mechanisms support Capri Loans' insurance sales?
Capri Loans says it enables real-time policy issuance through digital consent and gives its sales team a Policy Buy & Compare portal with multiple product offerings. It also identifies a digital customer-onboarding journey, providing a process for customers to move from product selection through policy issuance without relying solely on physical documentation or an offline process.
The presentation lists a dedicated claims desk for pre-service and post-service support, as well as Insurance Ki Pathashala, an initiative for insurance-product and process education. These service features are presented alongside the Rs 78.2 crore Q2FY27 premium mix, but the source does not disclose claims volumes, turnaround time, policy renewal rates or customer-service outcomes.
For customer acquisition, Capri Loans says it provides suitable product offers through WhatsApp links with a two-click buying journey. The two-click mechanism and embedded loan-customer offering are distinct routes: one is a digital purchase path, while the other is sales linked to lending customers. The presentation does not disclose how much of the 65% direct Q2FY27 premium was generated through WhatsApp links.
How does technology fit into Capri Loans' insurance-distribution model?
Capri Loans' presentation describes a 150-plus-member on-roll technology team and an in-house-developed platform with fully integrated workflows and a digital loan journey. The stated objectives include faster turnaround time, performance monitoring, productivity and cost efficiency. The source does not assign a separate technology-team count or technology cost to insurance distribution.
The technology platform is also described as customizable and scalable, with encryption of sensitive customer data and compliance with regulatory changes. These features are disclosed alongside a multi-product offering from 23 insurance partners, but the presentation does not provide insurance-specific system uptime, issuance conversion or the cost of integrating an insurer.
Capri Loans is developing Generative AI capabilities for process automation, according to the presentation. That is a disclosed development initiative rather than a quantified insurance target. Capri Loans does not state when these capabilities will be deployed or how they will affect insurance premium, digital issuance or customer-support metrics.
Conclusion
Capri Loans' disclosed insurance result is a 43% year-on-year increase in total premium to Rs 143.4 crore in H1FY27 from Rs 100.4 crore in H1FY26. The Q2FY27 data show a business led by direct sales at 65% of premium, health and wellness at 56%, and housing-linked products at 36%, with 23 insurer partnerships supporting the product range.
The next disclosed operational development to watch is Capri Loans' work on Generative AI capabilities for process automation, alongside its 150-plus-member technology team and digital issuance tools. Capri Loans has not provided an insurance-premium target, a commission-income target, a deployment date for AI capabilities or an insurance-specific conversion metric, leaving those measures unresolved in the presentation.