










Captain Polyplast sees most Rs 82.4 crore orders booked by Q3
Key highlights
- Captain Polyplast expects most revenue from Rs 82.4 crore of FY27 solar-pump orders for 3,500 pumps to be recognised before Q3 FY27 ends.
- Captain Polyplast secured Rs 47 crore for 2,000 pumps in September FY27, its largest single solar EPC order win to date.
- Captain Polyplast's Q2 FY27 consolidated total income rose 32.89% year on year to Rs 106.43 crore.
- Captain Polyplast's Q2 FY27 EBITDA margin declined to 9.66% from 10.29% as HDPE and LLDPE costs increased.
powered by IRIS
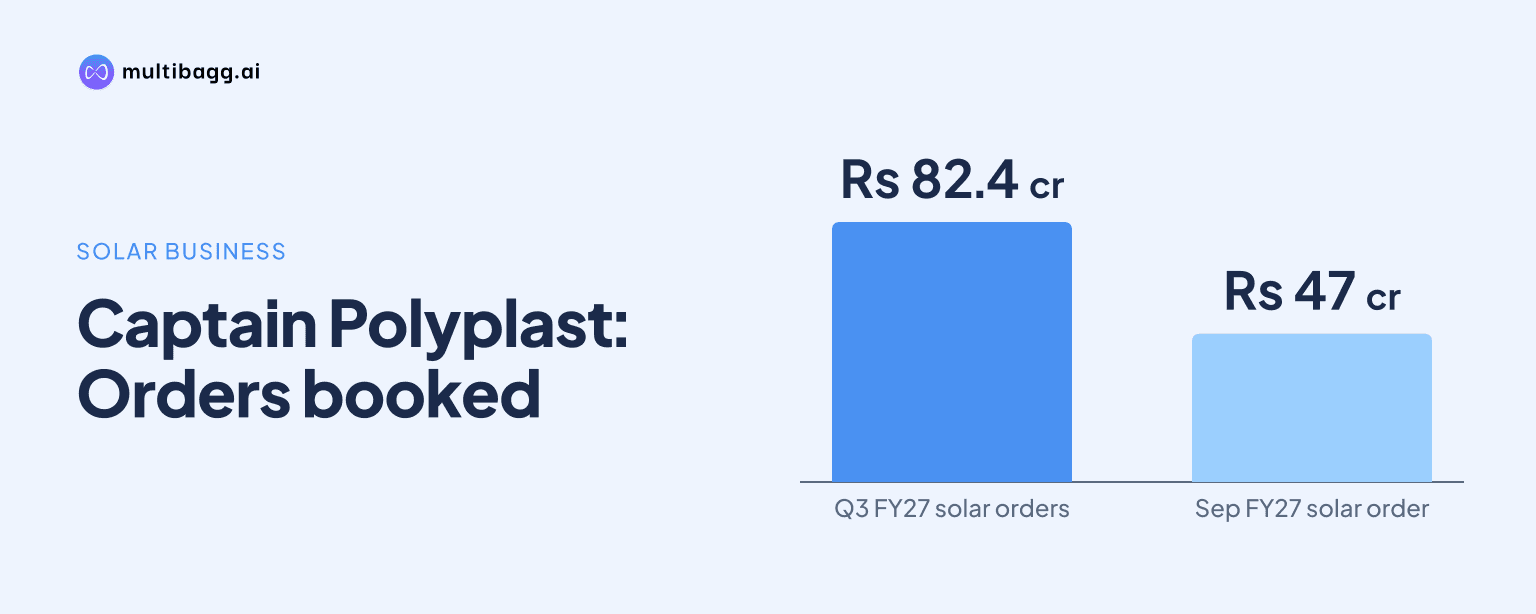
Captain Polyplast Limited expects most revenue from Rs 82.4 crore of FY27 solar-pump orders for 3,500 pumps to be recognised before Q3 FY27 ends, after recognising a large part in Q1 and Q2. Management said execution was under way, while orders from further tender wins would be recognised in Q4 as awarded.
Know Captain Polyplast inside out
Results, valuation, peers and who's buying, in one view.
When will Captain Polyplast recognise FY27 solar-pump revenue?
Captain Polyplast expects the majority of revenue from its 3,500 FY27 solar-pump orders to be recognised before Q3 FY27 ends. Whole-Time Director Ritesh Khichadia gave that timeline in response to an analyst's question on the Rs 82.4 crore order intake and said execution was already ongoing.
Management said a large part of the order revenue had already been recognised in Q1 and Q2 FY27, leaving the balance for Q3. It did not disclose the revenue booked in either quarter, the unrecognised order value, or an expected Q3 revenue figure. The stated timetable applies to the current FY27 order set rather than to future tender awards.
Captain Polyplast reported consolidated Q2 FY27 total income of Rs 106.43 crore, up 32.89% year on year. The call did not disclose solar pumps as a separate revenue line, so the contribution of the 3,500 pumps to Q2 income cannot be calculated from the transcript.
Which orders support Captain Polyplast's Q3 booking plan?
Captain Polyplast's Q3 recognition plan covers Rs 82.4 crore of FY27 solar-pump orders for 3,500 pumps, including two repeat orders from Maharashtra State Electricity Distribution Company Limited under the PM-KUSUM scheme. The September order was the company's largest single solar engineering, procurement and construction, or EPC, order win to date, according to management.
The July and September awards together account for Rs 70.6 crore and 3,000 pumps, compared with the Rs 82.4 crore and 3,500-pump FY27 total. Management did not provide the customer, award date or value for the remaining 500 pumps in the FY27 intake.
Captain Polyplast was empanelled in Maharashtra in August 2025 and has received orders for 5,000 pumps since then. That cumulative figure is 1,500 pumps higher than the FY27 intake of 3,500 pumps, and management cited it while discussing its execution record in solar pumps.
How did Captain Polyplast's Q2 earnings compare with order growth?
Captain Polyplast's Q2 FY27 total income grew faster than EBITDA and net profit as higher micro-irrigation input costs and interest costs limited earnings growth. Total income rose 32.89% year on year to Rs 106.43 crore, while earnings before interest, tax, depreciation and amortisation, or EBITDA, increased 24.75% to Rs 10.28 crore and net profit grew 5.55% to Rs 4.48 crore.
Q2 EBITDA margin declined to 9.66% from 10.29% a year earlier. Management attributed the change primarily to higher prices of high-density polyethylene, or HDPE, and linear low-density polyethylene, or LLDPE, petrochemical derivatives used in micro-irrigation products.
For H1 FY27, management said revenue increased 25.14% while profit after tax, or PAT, rose 7%. It said H1 EBITDA margin was almost flat, unlike the Q2 decline, and attributed the slower profit increase to raw-material costs and higher interest costs as working-capital requirements rose with business scale.
Got a follow-up? Ask IRIS
What could move Captain Polyplast revenue into Q4?
Captain Polyplast said revenue from additional tender wins would be recognised in Q4 FY27 as and when it receives those orders. Management said it was participating in another tender and expected one more tender after that, but did not disclose prospective pump volumes, order values or award dates.
Expansion beyond Maharashtra depends on a new phase of the Pradhan Mantri Kisan Urja Suraksha evam Utthan Mahabhiyan, or PM-KUSUM, scheme. Management said the original PM-KUSUM 1 deadline of March 2026 was extended and that there had been no fresh tendering during the current year in the states it was tracking.
Captain Polyplast expects fresh tendering after PM-KUSUM 2 is announced and said it could then seek empanelment in Rajasthan, Jharkhand, Karnataka and Haryana. The company did not specify a date for the scheme announcement or provide expected revenue from those states.
What are Captain Polyplast's H2 FY27 execution priorities?
Captain Polyplast's stated H2 FY27 priorities are timely solar-pump execution, ramping its Ahmedabad manufacturing facility and increasing non-subsidy micro-irrigation sales. Management said higher production at Ahmedabad would allow progressively more components to be made in-house, adding backward integration that it expects to support margins.
In micro-irrigation, commercial and non-subsidy channels, including repeat farmer purchases and exports, contribute about 10% of segment business, management said. It expects this share to improve, but gave no percentage target or timetable. Management also expects central and state governments to revise micro-irrigation benchmark costs in coming months, which it said could help pass through higher raw-material costs in H2.
Working-capital cycles differ between the two businesses. Management said solar pumps operate on a three-to-four-month cycle, compared with about eight months in micro-irrigation, and expects the consolidated cycle to reach five to six months by the end of FY27 as solar pumps become a larger part of the mix.
Captain Polyplast said most of its debt comprises annually renewable revolving working-capital facilities. Responding to an analyst who cited approximately Rs 89 crore of FY26 consolidated borrowing, management said actual annual repayment would be less than Rs 10 crore and could be met from existing accruals; it did not disclose a Q2 FY27 borrowing balance.
Conclusion
Captain Polyplast has set out a near-term execution timetable for its Rs 82.4 crore FY27 solar-pump intake: most revenue from 3,500 pumps is expected before Q3 ends. The order programme coincides with Q2 total-income growth of 32.89%, although higher HDPE and LLDPE costs and interest expenses held net-profit growth to 5.55%.
The next disclosures to watch are the remaining Q3 recognition from current solar-pump orders and any Q4 contribution from the two further tenders management described. Management's H2 margin expectations also depend on potential benchmark-cost revisions, Ahmedabad facility ramp-up and progress towards a five-to-six-month consolidated working-capital cycle by FY27 end.