










Concord Enviro targets 15%-20% FY27 growth on Q4 deliveries
Key highlights
- Concord Enviro retained its 15%-20% FY27 revenue-growth target despite a year-on-year H1 FY27 decline.
- Concord Enviro reported an order book of about Rs 714 crore, with a bulk executable in FY27.
- Management said Rs 422 crore of H2 FY27 revenue is needed to achieve 15% annual growth.
- Q2 FY27 gross margin rose to 57.5% from 50.5%, while EBITDA margin declined to 5.8% from 6.1%.
powered by IRIS
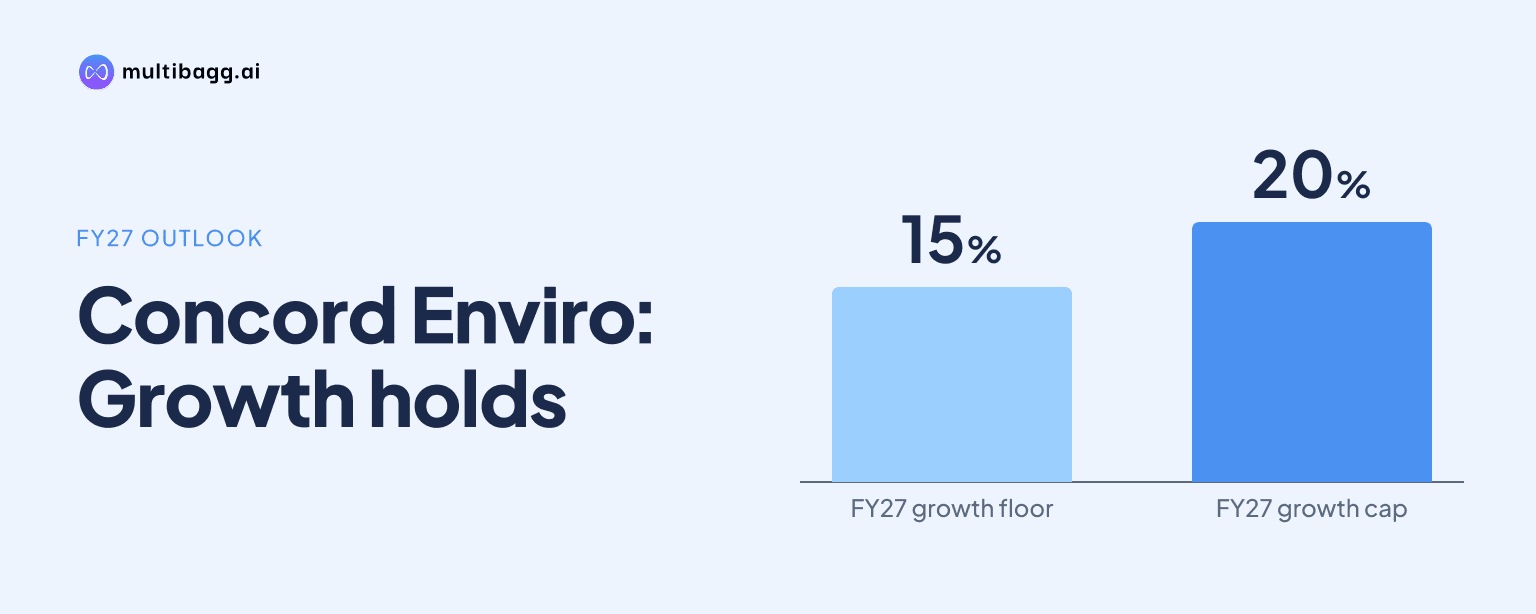
Concord Enviro Systems Limited maintained its FY27 revenue-growth target of 15%-20% despite a year-on-year H1 decline, with management relying on Rs 422 crore of H2 FY27 revenue and large steel-sector projects scheduled for Q4 delivery. The company said about Rs 714 crore of its order book was executable in FY27.
Know Concord Enviro Systems inside out
Results, valuation, peers and who's buying, in one view.
Can Concord Enviro meet its FY27 revenue-growth target after H1?
Concord Enviro says it can meet its FY27 target because large steel-sector orders are already being executed and are due for Q4 delivery. An analyst calculated that 15% annual growth would require Rs 422 crore of H2 FY27 revenue, and management said it was confident that Q3 and Q4 execution would achieve the revenue target.
Management placed the order book at about Rs 714 crore, with a bulk executable during FY27. That order book was the central support for its 15%-20% FY27 growth expectation. H1 FY27 had declined year on year after Q1 execution delays, including geopolitical and supply-chain disruptions affecting Gulf Cooperation Council, or GCC, linked operations and shipments.
The company described the revenue pattern as structurally weighted towards the second half. Management said Q1 and Q2 are generally suppressed quarters, while projects typically gather pace in Q3 and Q4 as customers finalise financial-year budgets and execution plans. Orders usually begin increasing in the latter part of Q2, making second-half delivery timing important to the FY27 outcome.
Why will Concord Enviro's quarterly revenue remain volatile?
Concord Enviro expects quarterly volatility to continue because project revenue depends on the execution schedules of large contracts, including steel orders planned for Q4 FY27. Management categorises normal orders as those worth Rs 5 crore to Rs 15 crore and large orders as those above Rs 50 crore. The delivery position of a large order can therefore shift revenue materially between quarters.
Export projects add to that variability, according to management. A quarter containing execution of a large export or industrial project can report higher revenue growth, while the period before delivery can be comparatively muted. The scheduled Q4 FY27 steel deliveries are consequently a stated reason why management expects a substantial share of annual revenue to arrive late in the year.
This differs from operations and maintenance, or O&M, revenue and sales of spares and consumables. Management said these streams are relatively steady, whereas S&P sales, its term for projects, remain volatile. The combination of recurring service revenue and delivery-led project sales means quarterly performance can vary even when underlying O&M and consumables demand is stable.
Q2 FY27 showed how revenue mix can affect profitability. Gross profit rose to Rs 77.267 crore from Rs 62.993 crore in Q2 FY26, while gross margin increased to 57.5% from 50.5%. However, earnings before interest, tax, depreciation and amortisation, or EBITDA, rose only 1.6% to Rs 7.779 crore from Rs 7.657 crore, and EBITDA margin declined to 5.8% from 6.1%.
Got a follow-up? Ask IRIS
What does Concord Enviro expect for FY27 margins?
Concord Enviro expects FY27 EBITDA margin to reach a low double-digit level, while management said overall profitability would remain in single digits for another year. Management based the EBITDA view on revenue growth, order mix and operating leverage, rather than on a revised revenue-growth target.
Management attributed part of the Q2 FY27 EBITDA-margin decline of 0.3 percentage points to foreign-exchange losses related to Mexican peso movement against the US dollar. It also said investments to scale operations, pursue larger project cycles and diversify products and business lines had raised fixed costs before the associated revenue base had fully expanded.
Management had initially said margins would be stable in FY27 and improve from FY28 onwards. During the call, it added that the expected annual mix and fixed-cost absorption could bring FY27 EBITDA margin into low double digits if Q3 and Q4 remain stable. This remains management's expectation, particularly after Q1 FY27 disruption to GCC-linked activity.
Management said Concord Enviro had generally operated near a 14%-odd EBITDA margin in earlier periods. It expects growth of about 20% to improve the absorption of fixed costs, but did not provide a precise FY27 EBITDA-margin target beyond a low double-digit range. The company also said gross-profit performance had generally exceeded that of competitors, without providing comparative figures.
Which businesses could support Concord Enviro's later growth?
Concord Enviro identified industrial water and wastewater, lifecycle services, membrane technology, desalination and industrial compressed biogas, or CBG, solutions as longer-term demand areas. Its immediate FY27 delivery plan is led by steel projects, while management also cited demand from solar manufacturing, chemicals and pharmaceuticals when discussing its multi-year order visibility.
The company said it had started receiving orders for its extreme heat-exchanger product, but management described it as an introductory offering priced around current market levels. It expects better margins over the longer term as adoption and scale increase, while placing current profitability within Concord Enviro's standard EBITDA range.
At its Sharjah facility, Concord Enviro said utilisation was running at 50%-60% after it moved some non-core and higher-cost activities to India. Sharjah remains its main membrane-production centre, while some export projects once assembled there are now assembled in India and shipped directly to customers. Management said it would review the planned Sharjah expansion in Q4 after assessing regional conditions.
Management also expects to submit Rs 500 crore to Rs 700 crore of bids in the next quarter for areas including dehumidification, CBG and battery manufacturing. It said a tertiary sewage-recycling demonstration cycle was beginning in the Middle East and that orders were expected in Q3. These are management expectations for bids and orders, rather than booked FY27 revenue.
Conclusion
Concord Enviro's FY27 growth case depends on turning the H1 setback into a Q3-Q4 execution recovery. The Rs 714 crore order book, the Rs 422 crore H2 revenue requirement and scheduled Q4 steel deliveries explain why management has retained its 15%-20% growth target despite acknowledging continuing volatility in project sales. O&M, spares and consumables provide steadier revenue, but large-project delivery remains decisive to the annual result.
The next measures to watch are Q3 progress on steel-project execution, whether Q4 deliveries occur as scheduled, and the resulting movement towards management's low double-digit FY27 EBITDA-margin expectation. Management also plans a Q4 review of Sharjah expansion investment, while Rs 500 crore to Rs 700 crore of expected next-quarter bids and anticipated Q3 Middle East orders could indicate the pace of opportunities beyond the current order book.