










Danish Power targets FY28 revenue of Rs 900-950 crore
Key highlights
- Danish Power targets FY28 revenue of Rs 900 crore to Rs 950 crore at 90% to 92% utilisation.
- Danish Power produced about 3,100 MVA in H1 FY27 at approximately 60% utilisation.
- Danish Power reported H1 FY27 consolidated revenue of Rs 291.93 crore, up 38% year on year.
- Danish Power's confirmed order book exceeded Rs 600 crore, with deliveries due over six to nine months.
powered by IRIS
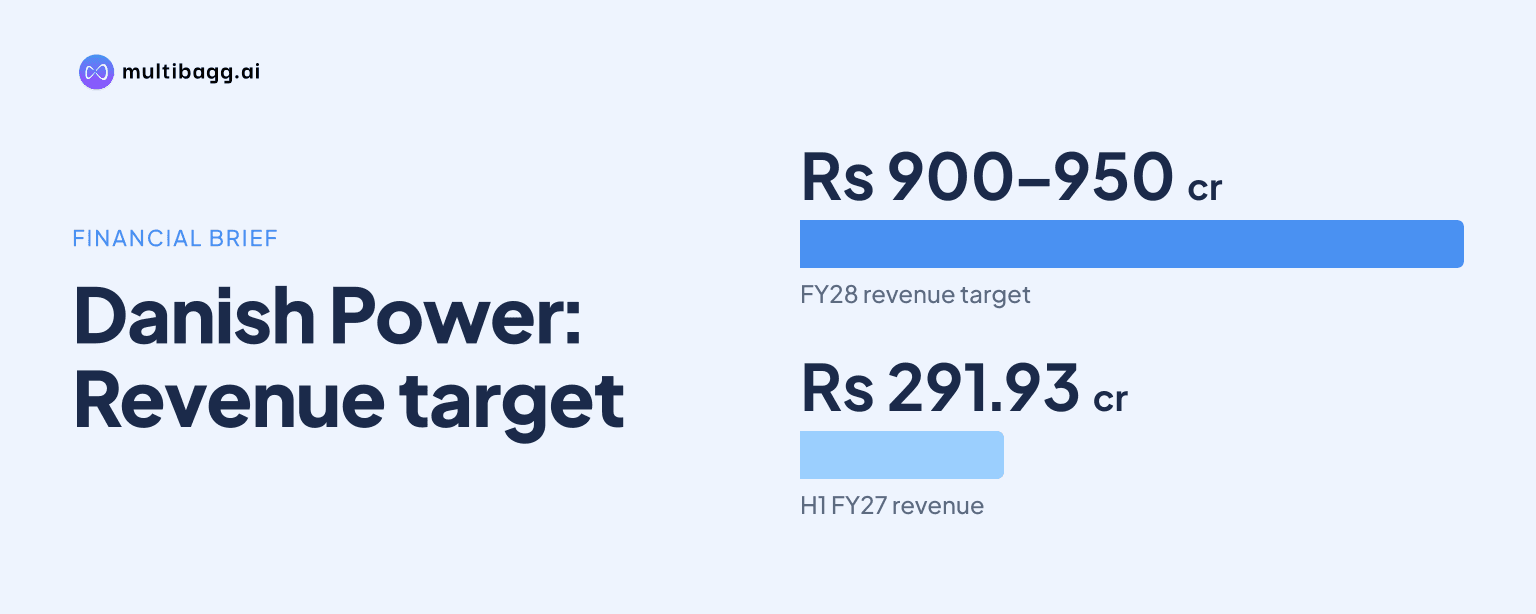
Danish Power Limited expects FY28 revenue of Rs 900 crore to Rs 950 crore from its existing transformer capacity as utilisation rises to 90% to 92%, from about 60% in H1 FY27. Management linked the target to a full-year ramp-up after capacity increased to more than 11,000 megavolt-amperes, or MVA.
Know Danish Power inside out
Results, valuation, peers and who's buying, in one view.
What is Danish Power's FY28 revenue target and utilisation assumption?
Danish Power has set a FY28 revenue target of Rs 900 crore to Rs 950 crore, assuming peak utilisation of about 90% to 92% at its existing facility. Management said 90% to 92% is generally the maximum utilisation possible in the transformer industry and described this as a full-year operating target for FY28.
The FY28 target is above Danish Power's FY27 revenue guidance of more than Rs 700 crore. The company reported consolidated revenue of Rs 291.93 crore in H1 FY27, up 38% year on year, and management said its business has historically been weighted towards H2. The FY27 outlook therefore relies on a heavier second-half production and delivery cycle, while the FY28 range assumes a full year of peak plant usage.
The revenue guidance is not a formal margin forecast. Danish Power reported H1 FY27 earnings before interest, tax, depreciation and amortisation, or EBITDA, of Rs 55.73 crore, up about 49% year on year, with an EBITDA margin of about 19.1%. Management said it aimed to maintain margins around the levels achieved over the past three years, with possible variation.
Why was Danish Power's H1 FY27 utilisation 60%?
Danish Power reported about 60% utilisation in H1 FY27 because the capacity increase to more than 11,000 MVA had only recently come online. Management said a plant does not normally attain peak utilisation in its first year because it must work through operational and production issues following expansion.
Production output was about 3,100 MVA in H1 FY27. Management also characterised H1 as the lighter half of its financial year, with dispatches and revenue concentrated in H2. The reported 60% rate therefore reflects both the early stage of the expanded facility and Danish Power's established seasonal production pattern.
Management said FY28 should be the first full year in which the plant can reach 90% to 92% utilisation. During the call, an analyst asked whether the current capacity could produce Rs 900 crore to Rs 950 crore at peak use, and management agreed. This linked the FY28 revenue target directly to the existing plant rather than the proposed 15,000-MVA expansion.
How does Danish Power's order book support its revenue plan?
Danish Power said its confirmed order book exceeded Rs 600 crore on November 5, 2026, with deliveries spread over the next six to nine months. Management cited that order book and its H2-heavy seasonality in saying it remained in line to meet FY27 revenue guidance of more than Rs 700 crore.
Demand enquiries covered battery storage, renewable and thermal generation, transmission and distribution, and exports. Exports represented about 15% of H1 FY27 revenue, compared with about 8% in the previous financial year. Management said 70% to 80% of orders typically come from repeat customers, which it cited when discussing demand visibility for both current and planned capacity.
Danish Power also expects power transformers to account for about 15% of product mix in FY27 after the division became active following the capacity expansion. In the 132-kilovolt, or kV, segment, the company had received a letter of intent, or LOI, and expected type-test completion in Q4 FY27. For 220 kV products, management expected an LOI shortly and type-test completion in Q1 of the next financial year.
Got a follow-up? Ask IRIS
What could affect Danish Power's margins and FY28 ramp-up?
Danish Power said the West Asia war increased transformer-oil, other raw-material and freight costs in H1 FY27, while also affecting availability. Despite that disruption, H1 FY27 EBITDA margin was about 19.1%, alongside EBITDA of Rs 55.73 crore. Management attributed the limited effect partly to price-variation clauses, supplier relationships and discussions with customers on affected firm-price orders.
Price-variation clauses use agreed formulas and price indices, so changes in raw-material prices can benefit either Danish Power or its customer. For certain firm-price contracts, management said it approached clients because of force majeure conditions. It said most orders in the current book were accepted from April onward and did not expect a significant impact in H2, although it noted that the war had not ended.
Component availability remains relevant to execution. Danish Power said it makes about 20% of its tank requirement in-house, while its automated radiator plant was scheduled for commissioning by the end of November 2026. Management said the radiator plant would supply about 80% to 90% of requirements and would address radiator bottlenecks in lead times and quality consistency.
How does Danish Power's planned expansion fit its longer-term capacity plan?
Danish Power plans to add about 15,000 MVA of capacity, taking total installed capacity to 26,000 MVA, through a project with an estimated outlay of Rs 200 crore. Site work was planned to start around December 2026, and management targeted commissioning 18 to 24 months later.
The proposed facility will produce 132 kV, 220 kV and 400 kV transformers, taking Danish Power into the 400 kV category for the first time. Management said it intended to fund about Rs 100 crore from internal accruals and Rs 80 crore to Rs 100 crore through debt. It also stated that the company had no debt at the time of the call.
Management estimated that the new 15,000-MVA capacity could generate additional revenue of about Rs 1,400 crore to Rs 1,500 crore, depending on product mix, timing and raw-material pricing. Danish Power plans to allocate about 30% to 40% of the new capacity to international markets, where management said capacity had constrained commitments to customers in Europe and the Middle East.
Conclusion
Danish Power's FY28 target of Rs 900 crore to Rs 950 crore depends on raising use of its existing more than 11,000-MVA plant from about 60% in H1 FY27 to 90% to 92% over a full year. The order book exceeding Rs 600 crore, H2-weighted delivery cycle, export growth and a broader power-transformer mix are the operating factors management identified behind that plan.
The next disclosed milestones are execution against FY27 guidance of more than Rs 700 crore, the planned 132 kV type test in Q4 FY27 and the 220 kV type test in Q1 of the next financial year. Management also plans to begin site work on the Rs 200 crore expansion around December 2026 and targets commissioning within 18 to 24 months.