










Delton H1 FY27 PAT more than doubles as revenue rises 62%
Key highlights
- Delton’s H1 FY27 PAT rose 114.4% to Rs 20.09 crore from Rs 9.4 crore.
- H1 FY27 revenue increased 62.0% to Rs 644.2 crore and EBITDA rose 72.1% to Rs 55.8 crore.
- Delton’s H1 FY27 EBITDA margin expanded to 8.66% from 8.15% in H1 FY26.
- Delton reported a Rs 471.5 crore order book on September 30, 2026, with EPC representing 87%.
powered by IRIS
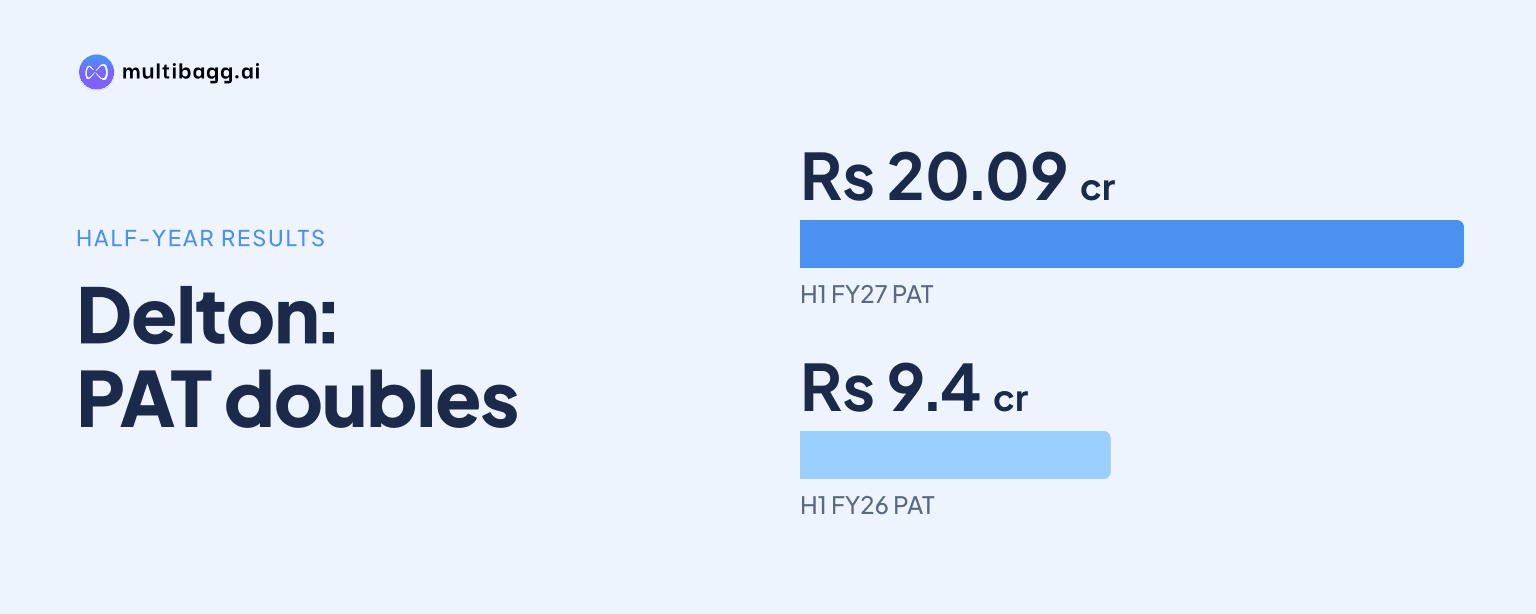
Delton’s H1 FY27 PAT rose 114.4% to Rs 20.09 crore from Rs 9.4 crore in H1 FY26, while revenue increased 62.0% to Rs 644.2 crore and EBITDA margin reached 8.66% from 8.15%, with no exceptional items reported in either half-year period.
Know Delton Cables inside out
Results, valuation, peers and who's buying, in one view.
How did Delton perform in H1 FY27?
Delton delivered H1 FY27 revenue of Rs 644.2 crore, compared with Rs 397.7 crore in H1 FY26, a 62% increase. Earnings before interest, tax, depreciation and amortisation, or EBITDA, rose 72% to Rs 55.8 crore from Rs 32.4 crore, while profit after tax, or PAT, increased 114% to Rs 20.1 crore from Rs 9.4 crore.
EBITDA and PAT grew faster than revenue in H1 FY27, while EBITDA margin rose by 51 basis points to 8.66% from 8.15%. Profit before tax, or PBT, increased 107% to Rs 25.7 crore from Rs 12.4 crore, and earnings per share rose to Rs 23.25 from Rs 10.84. Delton reported no exceptional items in either H1 FY27 or H1 FY26.
The presentation’s result-analysis page uses revenue of Rs 644.2 crore for H1 FY27, while the detailed profit and loss statement reports total income from operations of Rs 645.4 crore. The corresponding H1 FY26 figures are Rs 397.7 crore and Rs 398.6 crore, respectively, and both measures show 62% year-on-year growth.
What drove Delton’s margin expansion in H1 FY27?
Delton’s EBITDA margin increased to 8.66% because total operative expense rose 61%, marginally below the 62% rise in total income from operations. Total operative expense reached Rs 589.6 crore in H1 FY27 from Rs 366.2 crore a year earlier, leaving EBITDA of Rs 55.8 crore compared with Rs 32.4 crore.
Cost of materials consumed rose 71% to Rs 525.5 crore from Rs 307.8 crore, exceeding revenue growth. However, manufacturing expenses declined 6% to Rs 21.1 crore from Rs 22.6 crore, employee benefits expense rose 13% to Rs 29.9 crore from Rs 26.4 crore, and other expenses increased 39% to Rs 13.1 crore from Rs 9.4 crore.
Below EBITDA, finance costs grew 55% to Rs 26.1 crore from Rs 16.8 crore, while depreciation and amortisation increased 24% to Rs 4 crore from Rs 3.2 crore. These increases were below the 72% EBITDA growth rate, and PBT rose 107%; tax then increased 86% to Rs 5.6 crore from Rs 3 crore, resulting in the 114% increase in PAT.
Got a follow-up? Ask IRIS
Was Q2 FY27 better than the first quarter and last year?
Delton’s Q2 FY27 was higher than both Q1 FY27 and Q2 FY26 on revenue, EBITDA and PAT. Delton described Q2 FY27 as its highest-ever quarter on these three measures, reporting revenue of Rs 357.8 crore, EBITDA of Rs 30.4 crore and PAT of Rs 12.5 crore.
Against Q2 FY26, Q2 FY27 revenue increased 48% from Rs 241.3 crore, EBITDA rose 62% from Rs 18.7 crore and PAT grew 99% from Rs 6.3 crore. EBITDA margin moved to 8.49% from 7.76%, an improvement of 73 basis points, while PBT rose 92% to Rs 15.2 crore from Rs 7.9 crore.
Sequentially, Q2 FY27 revenue was 25% above Q1 FY27 revenue of Rs 287 crore. EBITDA increased 19% from Rs 25.4 crore, and PAT rose 65% from Rs 7.6 crore. Finance costs were broadly unchanged at Rs 13.1 crore in Q2 FY27 versus Rs 12.9 crore in Q1 FY27, while PBT increased 44% from Rs 10.5 crore.
Which segments and orders support Delton’s revenue base?
Delton’s H1 FY27 revenue was led by engineering, procurement and construction, or EPC, which accounted for 51% of revenue. Railways contributed 19%, Telecom contributed 11% and Other segments contributed 19%; Delton said EPC grew 68% year on year and Telecom grew 100%, without disclosing their half-year revenue values.
Delton reported an order book of Rs 471.5 crore as of September 30, 2026, equivalent to 1.4 times Q2 FY27 revenue according to its presentation. EPC represented Rs 409.5 crore, or 87%, of the order book, while Railway represented Rs 46 crore, or 10%, and Telecom represented Rs 16 crore, or 3%.
The presentation characterises EPC as the higher-margin segment but does not disclose segment-level margins or order-execution dates. It cites demand themes including a 500-gigawatt non-fossil capacity target by 2030 and fibre-optic category growth of about 12.4% compound annual growth rate, with those market figures attributed in the presentation to external industry sources.
Conclusion
Delton’s H1 FY27 result combined 62% revenue growth with a 51-basis-point improvement in EBITDA margin and a 114% increase in PAT. The detailed cost data show manufacturing expenses declined 6% and employee-benefit expense rose 13%, while material consumption increased 71% and finance costs rose 55% to Rs 26.1 crore.
What to watch next is conversion of the Rs 471.5 crore order book, 87% of which was EPC as of September 30, 2026, into revenue and profitability. Delton also reported an external credit-rating upgrade to BBB+/Stable from BBB/Stable and an increase in bank limits to Rs 310 crore from Rs 260 crore, while the presentation did not provide a future revenue or margin target.