










Dhanlaxmi H1 FY27 profit halves as margin falls to 11.1%
Key highlights
- Dhanlaxmi’s H1 FY2027 revenue from operations rose 20.27% to Rs 34.6281 crore.
- Dhanlaxmi’s H1 FY2027 EBITDA fell 44.45% to Rs 3.8513 crore and margin declined to 11.12% from 24.08%.
- Dhanlaxmi’s H1 FY2027 PAT declined 50.70% to Rs 2.2854 crore, with PAT margin at 6.60%.
- Dhanlaxmi’s trade receivables increased to Rs 33.588 crore at 30 Sep 26 from Rs 16.11 crore at 31 Mar 2026.
powered by IRIS
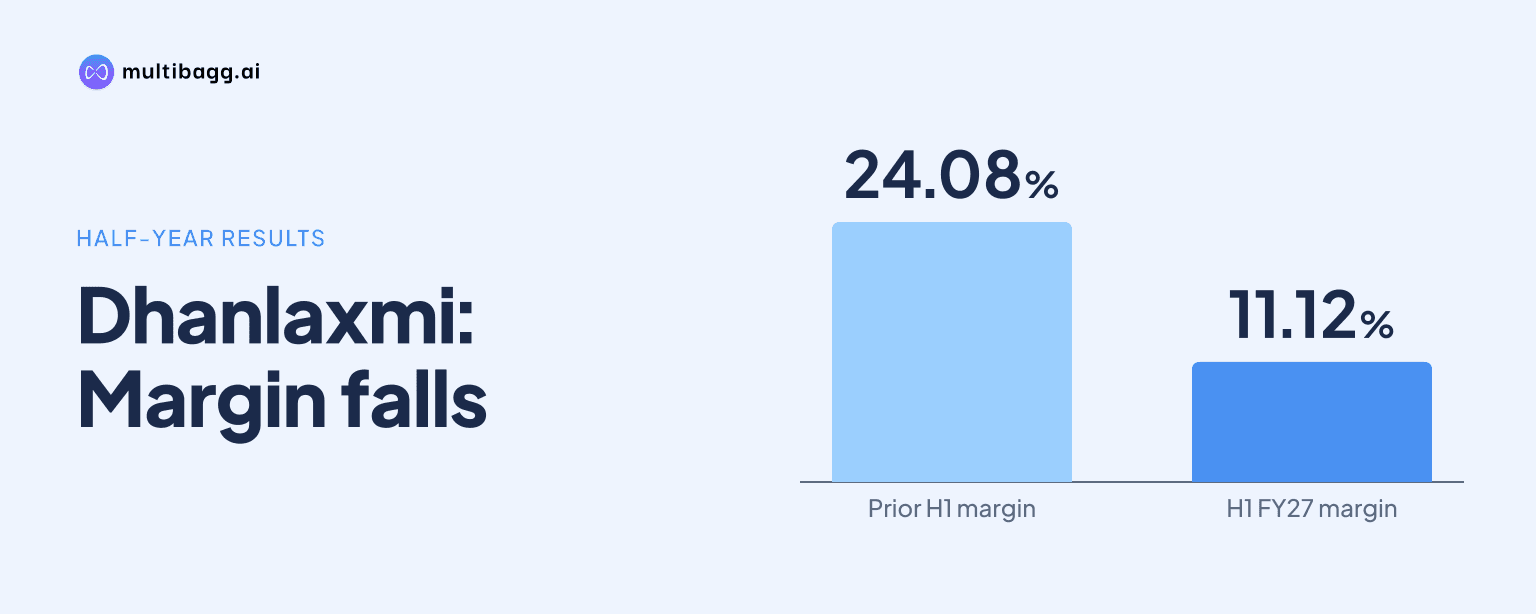
Dhanlaxmi Crop Science Limited reported H1 FY2027 revenue from operations of Rs 34.6281 crore, up 20.27% year on year, but profit after tax fell 50.70% to Rs 2.2854 crore as earnings before interest, tax, depreciation and amortisation margin declined to 11.12% from 24.08% in H1 FY2026.
Know Dhanlaxmi Crop Science inside out
Results, valuation, peers and who's buying, in one view.
Why did Dhanlaxmi’s H1 FY27 profit decline?
Dhanlaxmi’s profit declined because total expenses increased faster than income in H1 FY2027. Total expenses rose 40.79% to Rs 30.7768 crore, while total income increased 20.30% to Rs 34.6356 crore, reducing EBITDA by 44.45% to Rs 3.8513 crore from Rs 6.9326 crore in H1 FY2026.
The EBITDA margin declined by 12.96 percentage points to 11.12% from 24.08%. Profit before tax fell 50.72% to Rs 3.0542 crore from Rs 6.1981 crore, while tax expense declined 50.78% to Rs 76.89 lakh from Rs 1.5623 crore. PAT margin fell to 6.60% from 16.10%.
How did Dhanlaxmi’s costs change in H1 FY27?
Dhanlaxmi’s inventory movement was the main change in the reported cost pattern. Change in inventories of work in progress and finished goods was an expense of Rs 4.2142 crore in H1 FY2027, compared with negative Rs 17.373 crore in H1 FY2026, a change of Rs 21.5872 crore between the two periods.
Cost of material consumed declined 34.35% to Rs 22.0786 crore from Rs 33.6301 crore, while employee benefit expenses fell 10.63% to Rs 1.9089 crore. Other expenses declined 25.71% to Rs 2.5751 crore, but those reductions did not offset the inventory-line movement and the Rs 5.836 crore increase in revenue from operations.
Finance costs rose 9.18% to Rs 52.46 lakh from Rs 48.05 lakh, and depreciation and amortisation increased 10.28% to Rs 28.01 lakh from Rs 25.40 lakh. Together, these charges were Rs 80.47 lakh in H1 FY2027, compared with Rs 73.45 lakh a year earlier, contributing to the decline from EBITDA to profit before tax.
Got a follow-up? Ask IRIS
What does Dhanlaxmi’s September 2026 balance sheet show?
Dhanlaxmi’s total assets were Rs 87.5862 crore at 30 Sep 26, compared with Rs 63.8439 crore at 31 Mar 2026. Current assets increased to Rs 83.2632 crore from Rs 59.2568 crore, led by inventories of Rs 45.5406 crore and trade receivables of Rs 33.588 crore.
Inventories increased by Rs 6.4366 crore from Rs 39.104 crore, while trade receivables rose by Rs 17.478 crore from Rs 16.11 crore. Cash and cash equivalents increased to Rs 2.3697 crore from Rs 1.4025 crore, whereas total non-current assets decreased to Rs 4.323 crore from Rs 4.5871 crore.
Current liabilities rose to Rs 35.3057 crore at 30 Sep 26 from Rs 15.656 crore at 31 Mar 2026. Trade payables due to others increased to Rs 21.2601 crore from Rs 3.6204 crore, and short-term borrowings rose to Rs 10.1885 crore from Rs 9.2336 crore. Shareholders’ funds increased to Rs 47.7319 crore from Rs 45.4465 crore, while long-term borrowings rose to Rs 3.0243 crore from Rs 1.3482 crore.
How did Dhanlaxmi’s H1 FY27 compare with H2 FY26?
Dhanlaxmi returned to positive EBITDA and PAT in H1 FY2027 after reporting losses in H2 FY2026. Revenue from operations rose 270.89% to Rs 34.6281 crore from Rs 9.3364 crore, while EBITDA moved to a profit of Rs 3.8513 crore from a loss of Rs 5.8935 crore.
The EBITDA margin moved to 11.12% from negative 63.12% in H2 FY2026. PAT was Rs 2.2854 crore in H1 FY2027, compared with a loss of Rs 5.1274 crore in H2 FY2026, while profit before tax was Rs 3.0542 crore against a loss of Rs 6.6566 crore.
Total income increased 270.94% to Rs 34.6356 crore from Rs 9.3372 crore, exceeding the 102.08% increase in total expenses to Rs 30.7768 crore from Rs 15.2299 crore. This half-on-half improvement differs from the year-on-year comparison, under which H1 FY2027 EBITDA, PAT and both reported margins remained below H1 FY2026 levels.
Conclusion
Dhanlaxmi’s H1 FY2027 results show that revenue growth did not translate into proportionate profit growth. Revenue increased 20.27% to Rs 34.6281 crore, but a change in the inventory line from negative Rs 17.373 crore to an expense of Rs 4.2142 crore accompanied a 44.45% decline in EBITDA and a 50.70% decline in PAT. The balance sheet also showed higher inventories, receivables and current liabilities at 30 Sep 26.
What to watch next is Dhanlaxmi’s disclosed plan to diversify beyond its cotton-led portfolio and advance its product pipeline. Management has identified chilli varieties Dhanlabh, Dhantej and Dhanshakti for progression, plans to move okra varieties Kalyani and Shivani toward commercial readiness, and intends to deploy resources toward working capital, systems and scientific infrastructure alongside multi-season breeding and multi-location trials.