










Emerald Finance review unmodified despite unreviewed subsidiary data
Key highlights
- Emerald Finance received an unmodified consolidated review conclusion for the quarter ended 30 September 2026.
- The comparative quarter ended 30 September 2025 was board-approved but not reviewed.
- One subsidiary’s unreviewed information included Rs 10.069 crore revenue and Rs 5.3015 crore net profit after tax.
- Other-auditor-reviewed information included Rs 3.1171 crore quarterly revenue and Rs 1.6121 crore net profit after tax.
powered by IRIS
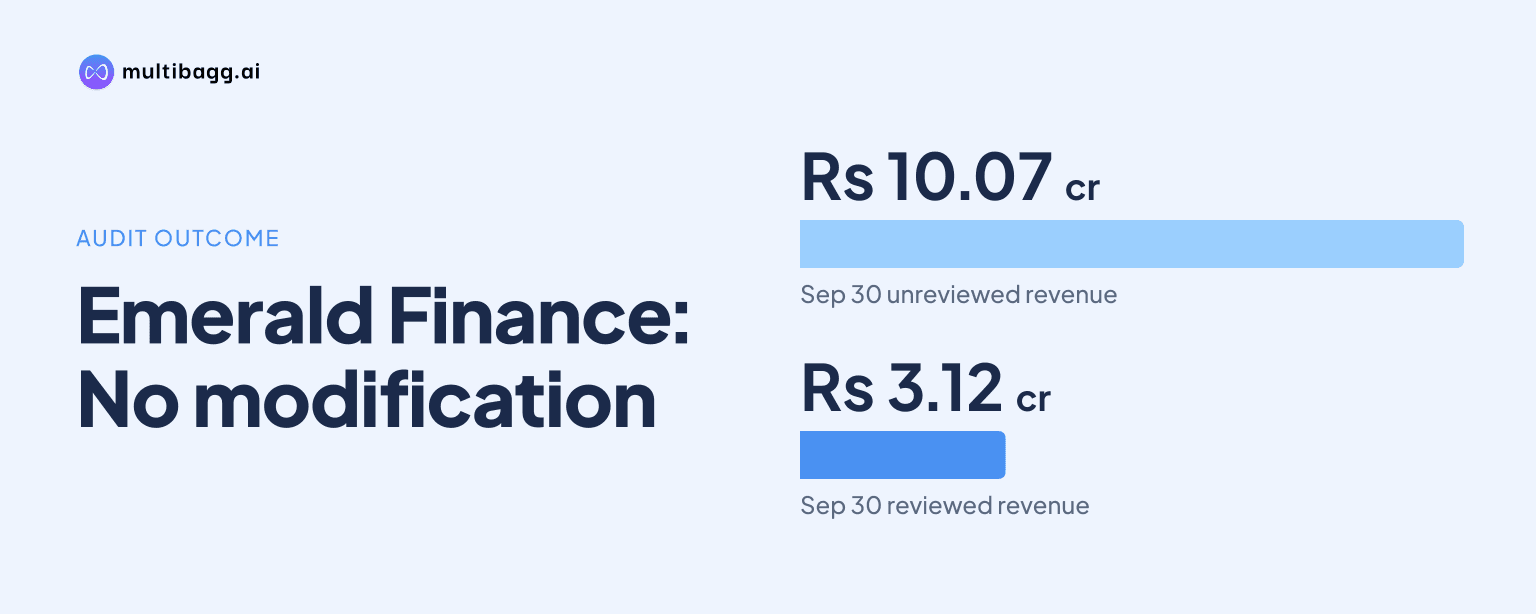
Emerald Finance Limited received an unmodified review conclusion on consolidated results for the quarter ended 30 September 2026, although the auditor said one subsidiary’s unreviewed information included Rs 10.069 crore of quarterly revenue and the corresponding quarter ended 30 September 2025 had not been reviewed.
Know Emerald Finance inside out
Results, valuation, peers and who's buying, in one view.
What did Emerald Finance’s auditor conclude?
Emerald Finance’s auditor concluded that nothing had come to its attention to indicate that the consolidated statement for the quarter ended 30 September 2026 omitted required disclosures or contained a material misstatement. S. Lal Bansal & Co. stated that its conclusion was not modified in respect of the subsidiary-information matters disclosed in its report dated 4 November 2026.
The conclusion covered consolidated unaudited quarterly and year-to-date financial results submitted under Regulation 33 of the Securities and Exchange Board of India, or SEBI, Listing Obligations and Disclosure Requirements Regulations, 2015. The report identifies Emerald Finance as the parent and says the statement included Éclat Net Advisors Private Limited, prepared using Indian Accounting Standard 34, or Ind AS 34, Interim Financial Reporting.
This was a review, rather than an audit, performed under Standard on Review Engagements, or SRE, 2410. The auditor said a review principally uses inquiries and analytical procedures and is substantially narrower than an audit, so it does not provide assurance that all significant matters that could arise in an audit would be identified.
Emerald Finance’s results notes, approved by its board on 4 November 2026, describe the statutory auditors as having expressed an “unmodified audit opinion.” However, the consolidated independent auditor’s report uses the term unmodified conclusion and expressly says that it does not express an audit opinion. The report’s formal finding is therefore an unmodified review conclusion.
Which Emerald Finance comparative figures were not reviewed?
The consolidated figures for the corresponding quarter ended 30 September 2025 were approved by Emerald Finance’s board but were not subjected to review, according to the auditor. This statement concerns the comparative quarterly figures presented with the 30 September 2026 results, rather than a modification to the current-period conclusion.
The report does not give individual revenue, profit or asset figures for the unreviewed September 2025 comparative quarter. It says only that the parent’s board approved those comparative consolidated figures, while the auditor’s review procedures applied to the statement submitted for the quarter ended 30 September 2026.
The distinction matters because the report separately discusses subsidiary information included in the current-quarter consolidation. The 30 September 2025 matter relates to comparative figures, whereas the subsidiary disclosures give current-quarter revenue and profit figures as well as fixed-asset balances at 30 September 2026.
Emerald Finance’s notes also say that its consolidated financial results for the quarter and half year ended 30 September 2026 were reviewed before the board took them on record on 4 November 2026. The auditor’s report nonetheless specifically calls out the absence of review for the corresponding quarterly comparative figures from 30 September 2025.
Got a follow-up? Ask IRIS
How did Emerald Finance’s subsidiary information sets differ?
The auditor described one subsidiary’s interim information as having been reviewed by other auditors, whose reports were furnished by management. That information reflected fixed assets of Rs 7.906 lakh at 30 September 2026, quarterly revenue of Rs 3.1171 crore and quarterly net profit after tax of Rs 1.6121 crore.
The report separately described one subsidiary whose interim financial information had not been reviewed or audited by that subsidiary’s auditors. As included in Emerald Finance’s consolidated unaudited results, that information reflected fixed assets of Rs 1.6332 crore at 30 September 2026, revenue of Rs 10.069 crore and net profit after tax of Rs 5.3015 crore for the quarter ended 30 September 2026.
The unreviewed-or-unaudited information had Rs 6.9519 crore more reported quarterly revenue than the information reviewed by other auditors, based on the two sets of figures in the report. Its fixed assets were also Rs 1.55414 crore higher at 30 September 2026. These comparisons describe the figures disclosed by the auditor and do not establish the subsidiaries’ contribution to consolidated results.
The filing does not connect the name Éclat Net Advisors Private Limited to either disclosed set of subsidiary figures. It also does not give a reconciliation from the Rs 10.069 crore or Rs 3.1171 crore revenue figures to Emerald Finance’s total consolidated revenue, nor does it state why one subsidiary’s information was not reviewed or audited by its own auditors.
What was the scope of Emerald Finance’s consolidated review?
S. Lal Bansal & Co. reviewed Emerald Finance’s consolidated statement for the quarter ended 30 September 2026 under SRE 2410 and performed applicable procedures under the SEBI circular issued for Regulation 33(8). Management was responsible for preparing the statement, and the board approved it on 4 November 2026.
The auditor stated that its conclusion, insofar as it related to the subsidiary information reviewed by other auditors, was based on those other auditors’ reports furnished by management. For the subsidiary information that had not been reviewed or audited by its own auditors, the auditor explicitly said that its conclusion was not modified.
Emerald Finance’s accounting notes say the group operates in one segment, “Finances - Non Banking Finance Company,” and therefore says the segment disclosure requirements of Ind AS 108 do not apply. The notes also say that, at 30 September 2026, impairment allowances under Ind AS 109 exceeded the total provision required under Income Recognition Asset Classification and Provisioning norms, so no impairment-reserve transfer was required.
The same filing includes a cash-flow statement for the half year ended 30 September 2026, reporting net cash generated from operating activities of negative Rs 8.3195 crore, compared with negative Rs 10.635 crore for the half year ended 30 September 2025. The subsidiary scope disclosures in the auditor’s report, however, identify revenue and profit specifically for the quarter ended 30 September 2026, so the two reporting periods should not be treated as directly comparable.
Conclusion
Emerald Finance’s consolidated review conclusion for the quarter ended 30 September 2026 was not modified, but the report identifies limits around parts of the supporting subsidiary information. The corresponding 30 September 2025 quarter was not reviewed, while one current-quarter subsidiary information set included Rs 10.069 crore of revenue without review or audit by that subsidiary’s auditors.
The next item to watch is Emerald Finance’s subsequent results filing after the board approval of 4 November 2026, particularly whether the auditor again discloses unreviewed subsidiary information or unreviewed comparatives. The supplied filing discloses no remediation plan, target or scheduled audit action regarding the Rs 10.069 crore subsidiary information.