










GRCL sees Plant 2 revenue of Rs 50-60 crore at full use
Key highlights
- GRCL expects Plant 2 to be fully utilised by the end of FY28.
- Plant 2 was operating at about 35% to 40% utilisation in H1 FY27.
- Management estimates Plant 2 can generate Rs 50 crore to Rs 60 crore at peak utilisation.
- Plant 1 was at about 85% utilisation, versus 35% to 40% for Plant 2.
powered by IRIS
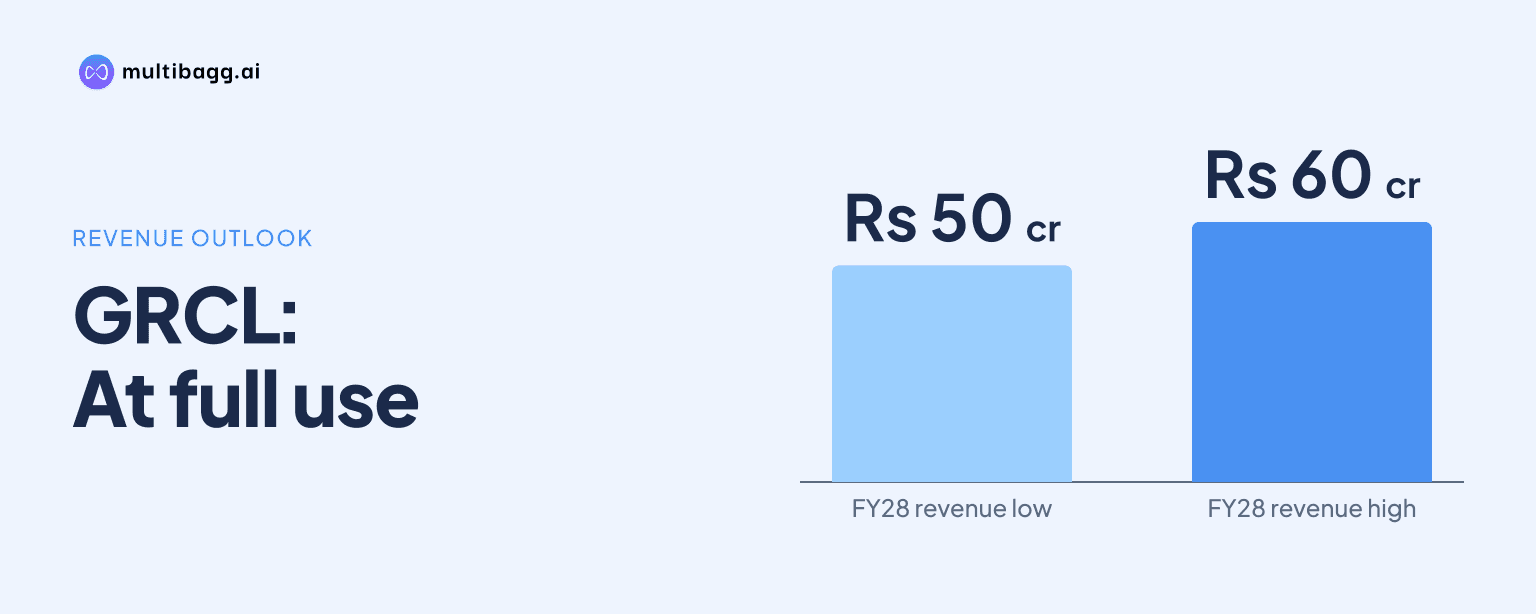
Gayatri Rubbers and Chemicals Limited said on November 5, 2026 that Plant 2 could generate Rs 50 crore to Rs 60 crore of revenue at peak utilisation and is expected to be fully utilised by the end of financial year 2028 (FY28). The specialised railway-products facility was operating at about 35% to 40% utilisation, leaving existing capacity available for a production ramp.
Know Gayatri Rubbers and Chemicals inside out
Results, valuation, peers and who's buying, in one view.
When does GRCL expect Plant 2 to be fully utilised?
GRCL expects Plant 2 to be fully utilised by the end of FY28, according to Managing Director Shilp Chotai’s response to an investor question on the H1 FY27 earnings call. He described the timeline as feasible within the coming two years, while framing it as an expectation rather than formal financial guidance. Plant 2 is dedicated to specialised railway products, so its ramp depends on demand and product approvals in that market.
The FY28 target contrasts with the nearer-term outlook for Plant 1. Management said Plant 1, which has installed capacity of 200 metric tonnes per month, was operating at about 85% utilisation in H1 FY27 and could reach complete utilisation around FY27. Plant 2, by comparison, was at about 35% to 40%, leaving more available capacity at the railway-focused facility.
GRCL’s medium-term objective is to raise utilisation of its existing manufacturing facilities towards 90% to 95% while expanding its product range and customer base. The two Faridabad facilities support current operations, and management said the available capacity allows it to cater to incremental demand without immediately requiring substantial investment in new manufacturing infrastructure.
What revenue can GRCL’s Plant 2 generate at full use?
GRCL said Plant 2 could generate maximum revenue of around Rs 50 crore to Rs 60 crore at peak utilisation. Management added that the actual outcome would depend on how much machinery is used, making the range an estimate of facility potential rather than a committed sales target.
The indicated Rs 50 crore to Rs 60 crore range exceeds GRCL’s total income of Rs 27.52 crore for H1 FY27 across both plants and all business lines. H1 FY27 total income rose 58.75% year on year, while earnings before interest, tax, depreciation and amortisation (EBITDA) increased 60.91% to Rs 6.46 crore and profit after tax rose 54.21% to Rs 4.06 crore.
Management said it remained on track with its FY27 revenue target of Rs 55 crore and that revenue could exceed that figure. It attributed the H1 FY27 contribution particularly to Indian Railways and said Indian Railways and smart meters were expected to contribute in the second half as well.
How much unused capacity does GRCL have at Plant 2?
GRCL has approximately 60% to 65% of Plant 2 capacity unused based on the disclosed 35% to 40% utilisation range, compared with about 15% unused capacity at Plant 1. This difference explains management’s focus on raising existing-facility utilisation before taking a decision on a third plant.
The expansion opportunity is centred on railways but extends across several components. GRCL said it supplies about 65 of the 75 rubber products required for a single railway coach. Of the remaining 10 products, management identified two to three as high-revenue opportunities, including railway pads and automatic inter-car gangways, which require approvals before additional work can be pursued.
Plant 2’s current utilisation also sits alongside a railway order book of around Rs 10 crore to Rs 12 crore, which management said would be completed entirely in FY27. Indian Railways contributes around 50% of GRCL revenue, according to management. Separately, the company secured purchase orders worth Rs 4.53 crore for specialised rubber-with-metal railway components, with execution scheduled through May 2027.
Got a follow-up? Ask IRIS
What will determine GRCL’s Plant 2 ramp?
GRCL’s Plant 2 ramp will depend substantially on railway demand, railway-pad approval and conversion of product opportunities into orders. Management said railway pads could contribute to FY28 revenue if approval is obtained by then. It said it did not expect a major increase in smart-meter demand, while expressing hope for Indian Railways and railway-pad demand through FY28.
GRCL expects approximately Rs 10 crore to Rs 15 crore of FY27 revenue from Vande Bharat and Metro projects, separate from its other Indian Railways business. The company said it was receiving good orders for Vande Bharat and expected some good orders from Metro projects, although it did not provide a split between the two categories.
Management also cited specialised rubber pipes, for which supplies were expected to commence in the first half of 2027, as an adjacent opportunity. GRCL said its prototype for gas and water meter applications had been accepted by Genus. It also delivered a prototype order to the Indian Space Research Organisation, but management said any subsequent business would depend on tenders issued when the agency requires material.
Why is GRCL delaying a decision on Plant 3?
GRCL said it will consider Plant 3 only after receiving approval for railway pads. Management said the railway-pad approval process has four stages, of which one stage had been cleared as of the November 5, 2026 call. It estimated that complete clearance and approval could take nine to 12 months.
That sequence makes Plant 3 a conditional future investment rather than an announced capital-expenditure programme. Until the railway-pad approval is obtained, Plant 2 remains the specialised railway-products facility available for the proposed ramp towards full utilisation by FY28.
GRCL also said it had completed 70% of the documents, permissions and certificates required for exports, while the remaining 30% involved tests and fulfilment of criteria. Management did not provide an export revenue estimate, saying it could not comment on the contribution until exports begin to the desired countries.
Conclusion
GRCL has set out a measurable capacity plan for Plant 2: utilisation of about 35% to 40% in H1 FY27, an expected full-utilisation point by the end of FY28, and estimated peak revenue of Rs 50 crore to Rs 60 crore. The contrast with Plant 1 at about 85% utilisation shows why management sees room to grow through the two existing Faridabad facilities before considering a new plant.
The next disclosed milestones are railway-pad approval, which management said may require nine to 12 months after one of four stages was cleared, and the expected commencement of specialised rubber-pipe supplies in the first half of 2027. Execution of the Rs 10 crore to Rs 12 crore railway order book in FY27 and management’s expectation of Rs 10 crore to Rs 15 crore from Vande Bharat and Metro projects will also indicate the pace of the Plant 2 ramp.