










Ice Make FY26 revenue grew 41% as EBITDA margin fell to 6.54%
Key highlights
- Ice Make’s FY26 standalone revenue rose 41.25% to Rs 668.4073 crore.
- Ice Make’s FY26 EBITDA margin fell to 6.54% from 9.11% in FY25.
- Ice Make’s FY26 standalone PAT declined 53.09% to Rs 10.8942 crore.
- Ice Make’s FY26 debt-to-equity ratio increased to 2.68 times from 1.84 times.
powered by IRIS
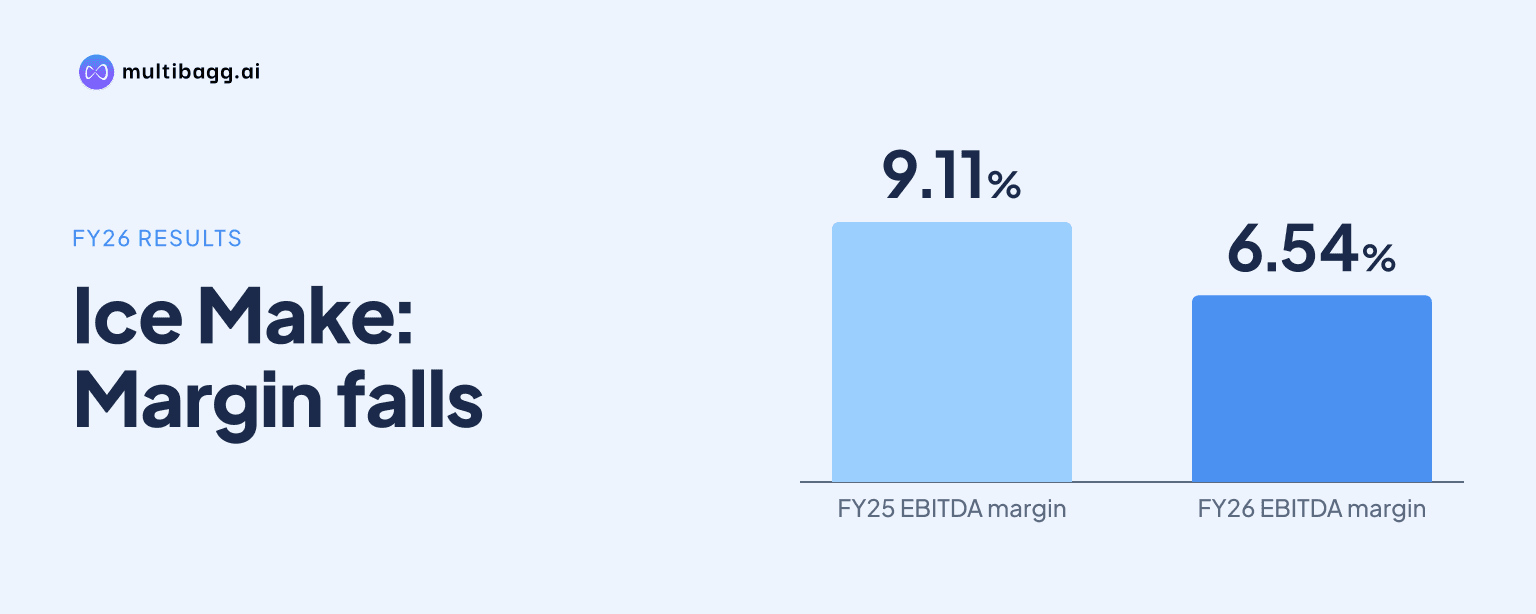
Ice Make reported FY26 standalone revenue of Rs 668.4073 crore, up 41.25% from FY25, but EBITDA margin fell to 6.54% from 9.11% and profit after tax declined 53.09% to Rs 10.8942 crore. The reported FY26 outcome shows sales growth materially outpaced the change in operating profit.
Know ICE Make Refrigeration inside out
Results, valuation, peers and who's buying, in one view.
How fast did Ice Make’s FY26 standalone revenue grow?
Ice Make’s standalone revenue grew 41.25% to Rs 668.4073 crore in FY26 from Rs 473.2224 crore in FY25. The Rs 195.1849 crore increase followed revenue of Rs 370.5795 crore in FY24, Rs 304.235 crore in FY23 and Rs 201.1923 crore in FY22.
Earnings before interest, tax, depreciation and amortisation, or EBITDA, rose only 1.39% to Rs 43.7297 crore in FY26 from Rs 43.1315 crore in FY25. Revenue therefore increased by Rs 195.1849 crore while EBITDA increased by Rs 0.5982 crore, which is consistent with the reported EBITDA-margin decline.
The FY26 figures on the annual financial page are standalone figures, while the presentation’s Q4 page is consolidated. This means the annual Rs 668.4073 crore revenue, Rs 43.7297 crore EBITDA and Rs 10.8942 crore PAT should not be equated directly with the consolidated quarterly figures. The supplied pages do not provide full-year consolidated financial numbers.
Why did Ice Make’s FY26 profit margins fall?
Ice Make’s FY26 EBITDA margin fell 2.57 percentage points to 6.54%, from 9.11% in FY25, despite the 41.25% increase in standalone revenue. The margin was 11.12% in FY24 and 10.80% in FY23, making FY26 the lowest EBITDA-margin figure in the five-year series displayed.
PAT margin declined 3.28 percentage points to 1.63% in FY26 from 4.91% in FY25. PAT fell to Rs 10.8942 crore from Rs 23.2241 crore a year earlier and was also below Rs 26.6172 crore in FY24, although FY26 revenue exceeded revenue reported in both prior years.
Earnings per share, or EPS, decreased to Rs 6.90 in FY26 from Rs 14.72 in FY25 and Rs 16.87 in FY24. Net worth nevertheless increased to Rs 136.0547 crore from Rs 128.3958 crore in FY25, while return on equity moved in the opposite direction as profit declined.
The presentation reports the margin movement but does not identify a specific cost, pricing, product-mix or customer-mix reason for it. It lists selective backward integration and automated panel manufacturing as mechanisms intended to improve cost control and execution readiness, but gives no margin target, savings estimate or timetable for these initiatives.
Got a follow-up? Ask IRIS
What do Ice Make’s consolidated Q4 numbers show?
Ice Make’s consolidated revenue for Q4 March 31, 2026 rose 41.86% to Rs 255.8464 crore from Rs 180.3549 crore in Q4 March 31, 2025. Consolidated EBITDA, however, declined 0.37% to Rs 21.7691 crore from Rs 21.8499 crore, showing a similar sales-and-profit divergence to the FY26 standalone figures.
Consolidated EBITDA margin declined by 3.58 percentage points to 8.50% in Q4 March 31, 2026 from 12.08% a year earlier. Consolidated PAT margin fell by 2.50 percentage points to 3.95%, while PAT decreased by Rs 1.5404 crore to Rs 10.1235 crore.
The Q4 revenue increase was Rs 75.4915 crore, but both reported EBITDA and PAT declined year on year. The presentation does not provide a Q4 breakdown by refrigeration product, customer, geography or expense category, so it does not establish the drivers of the quarterly margin changes.
How did Ice Make’s returns and leverage change in FY26?
Ice Make’s return on equity, or ROE, fell to 8.24% in FY26 from 19.60% in FY25, a reduction of 11.36 percentage points. ROE was 27.52% in FY24 and 28.00% in FY23, while FY26 net worth was Rs 136.0547 crore.
Ice Make’s debt-to-equity ratio rose to 2.68 times in FY26 from 1.84 times in FY25 and 0.93 times in FY24. The ratio was 0.86 times in FY23 and 0.88 times in FY22, making 2.68 times the highest figure in the five-year series shown in the presentation.
The supplied pages do not disclose the absolute debt balance or explain why debt-to-equity increased in FY26. They do show that manufacturing of continuous polyurethane foam/polyisocyanurate sandwich panels, chest freezers and visi coolers began at the Bavla facility in 2025, but do not quantify any impact on borrowing, revenue or margins.
Ice Make also reports five plants at Dantali, Vamaj, Bavla, Vayalur and Kolkata. In 2026, Bharat Refrigerations Private Limited was relocated to Vayalur, and Ice Make entered share subscription, shareholders’ and joint-venture agreements with Galilei Holdings Co. Limited; the presentation does not provide financial terms or expected earnings effects for those agreements.
Conclusion
Ice Make’s FY26 results combine 41.25% standalone revenue growth with lower profitability, returns and a higher debt-to-equity ratio. EBITDA rose only 1.39% as EBITDA margin fell to 6.54%, while PAT declined 53.09%; the consolidated Q4 figures similarly show revenue growth alongside lower EBITDA and PAT.
The next reported results will show whether Ice Make’s stated selective backward integration, automated panel manufacturing and expansion in quick-commerce cold-chain solutions affect margins and execution. The presentation also leaves unresolved how the 2.68-times FY26 debt-to-equity ratio, the Bavla manufacturing activity and the Galilei Holdings Co. Limited agreements will affect subsequent financial performance.