










Indo-MIM Limited Revenue Reaches ₹1,271 Crore in Q2 FY27
Key highlights
- Indo-MIM reported Q2 FY27 revenue of ₹1,271 crore, compared with ₹1,218 crore in Q1 FY27.
- Q2 FY27 pre-exceptional PBT declined to ₹309 crore from ₹325 crore in Q1 FY27.
- H1 FY27 consolidated revenue was ₹2,490 crore, up 11.8% year on year.
- Indo-MIM retained its FY27 revenue target of ₹5,000 crore and bottom-line target of ₹850 crore.
powered by IRIS
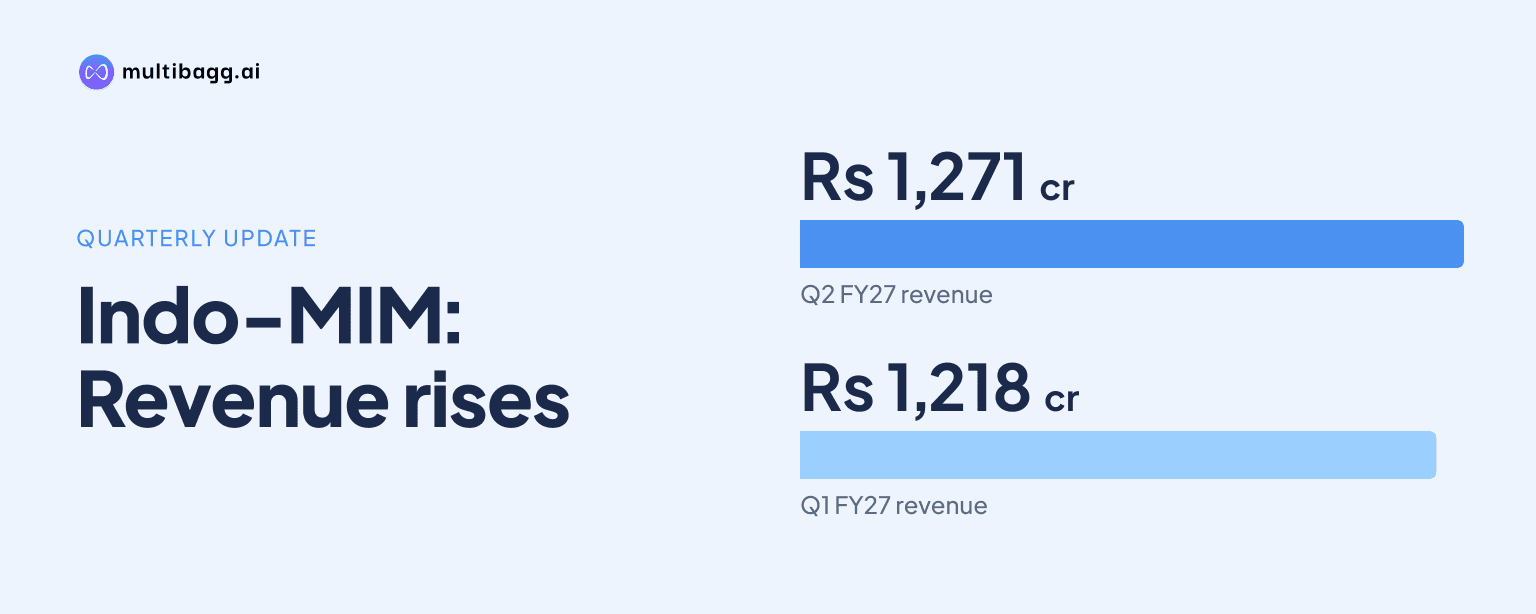
Indo-MIM Limited reported Q2 FY27 revenue of ₹1,271 crore, up from ₹1,218 crore in Q1, but pre-exceptional profit before tax declined to ₹309 crore from ₹325 crore as product mix affected profitability. The company retained its FY27 revenue target of ₹5,000 crore after H1 consolidated revenue reached ₹2,490 crore.
Know Indo-MIM inside out
Results, valuation, peers and who's buying, in one view.
What did Indo-MIM report for Q2 FY27?
Indo-MIM reported sequential revenue growth in the September quarter, with Q2 FY27 revenue rising ₹53 crore from Q1 FY27 to ₹1,271 crore. H1 FY27 consolidated revenue stood at ₹2,490 crore, representing year-on-year growth of 11.8%, according to the company’s investor presentation.
The stronger top line was supported by activity across aerospace, medical devices and consumer electronics. Management also cited demand visibility in industrial gas turbines, aerospace, humanoids and satellite-related programmes. However, it noted that some new programmes remain pre-revenue, meaning their contribution has not yet been reflected in reported sales.
Why did pre-exceptional profit decline despite higher revenue?
Pre-exceptional PBT fell to ₹309 crore in Q2 FY27 from ₹325 crore in Q1 FY27, despite the quarter-on-quarter increase in revenue. The call summary attributed the decline primarily to product mix, while stating that gross margin improved because of the component mix during the period.
H1 FY27 PAT was ₹455.3 crore, up 57.0% year on year, while the company’s presentation reported EBITDA of ₹803.4 crore and an EBITDA margin of 32.0%. Management commentary indicated that the increase in half-year profit was influenced by exceptional items, with underlying pre-exceptional profit growth remaining limited. This distinction is relevant because headline PAT and recurring operating performance did not move at the same pace.
What was discussed on the Indo-MIM earnings call?
Indo-MIM held its earnings conference call on November 16, 2026, at 15:00 IST to discuss unaudited standalone and consolidated results for the quarter and half year ended September 30, 2026. HDFC Securities Limited hosted the call, and the company subsequently made the audio recording available on its website.
The company filed the availability of the recording with NSE and BSE under Regulation 30 of the SEBI Listing Regulations. The exchange filing itself did not contain financial figures or new business updates. Instead, investors were directed to the recording for management commentary, while the reported financial information was available through the results material and investor presentation.
Management’s message on the call was balanced. It expressed confidence on the revenue trajectory and said the FY27 top-line target was within reach. But it did not give an unqualified upgrade to profit guidance, indicating that a more specific update could be provided in January after greater visibility on the second half.
Got a follow-up? Ask IRIS
How do the results affect Indo-MIM’s FY27 targets?
Indo-MIM retained its FY27 revenue target of ₹5,000 crore and bottom-line target of ₹850 crore. With H1 revenue of ₹2,490 crore, the company had achieved close to half of the annual revenue objective by the end of September 2026. Management said it expected to meet the revenue target comfortably.
The company also said the bottom line could be slightly ahead of its initial target, subject to a later update. Yet the Q2 decline in pre-exceptional PBT shows why the company’s guidance language remained measured. Revenue growth alone does not establish the pace of recurring profit growth when quarterly product mix changes.
For investors, the key reported indicators are the 11.8% H1 revenue increase, the 32.0% H1 EBITDA margin and the gap between headline PAT growth and pre-exceptional profitability. Inventory days were also identified as an area of attention in the call coverage, alongside the progress of emerging programmes that have not started generating revenue.
What are the broader operating factors behind the quarter?
Indo-MIM operates in industrial manufacturing and serves end markets including aerospace, medical devices and consumer electronics. The company’s discussion of industrial gas turbines, humanoids and satellite applications points to a programme-led demand pipeline, where qualification and ramp-up timelines can affect when business converts into revenue.
The company also reported lower leverage and improved returns on capital in the H1 FY27 discussion. These operating indicators provide context for management’s revenue confidence, while the rise in inventory days and the Q2 pre-exceptional PBT movement remain factors investors can track through subsequent disclosures. No specific inventory figure was provided in the supplied call material.
Conclusion
Indo-MIM delivered higher Q2 FY27 revenue of ₹1,271 crore and H1 revenue of ₹2,490 crore, keeping its ₹5,000 crore annual sales target unchanged. However, pre-exceptional PBT declined sequentially to ₹309 crore, showing that the improvement in headline H1 PAT included the effect of exceptional items and should be considered alongside recurring profitability.
The next disclosed checkpoint is management’s planned January update on FY27 bottom-line visibility. Investors will also watch whether new aerospace, industrial gas turbine, humanoid and satellite programmes begin contributing revenue, and whether inventory and product mix trends support pre-exceptional profit in the second half.