










Mahanadi Coalfields margin fell 4.72 points in two years
Key highlights
- Mahanadi Coalfields’ operating EBITDA margin fell from 46.41% in Fiscal 2024 to 41.69% in Fiscal 2026.
- Operating EBITDA declined by Rs 1,945.68 crore from Fiscal 2024 to Fiscal 2026.
- Mahanadi Coalfields’ 41.69% Fiscal 2026 operating EBITDA margin exceeded Coal India’s disclosed 24.94%.
- Return on net worth declined from 80.56% in Fiscal 2024 to 53.77% in Fiscal 2026.
powered by IRIS
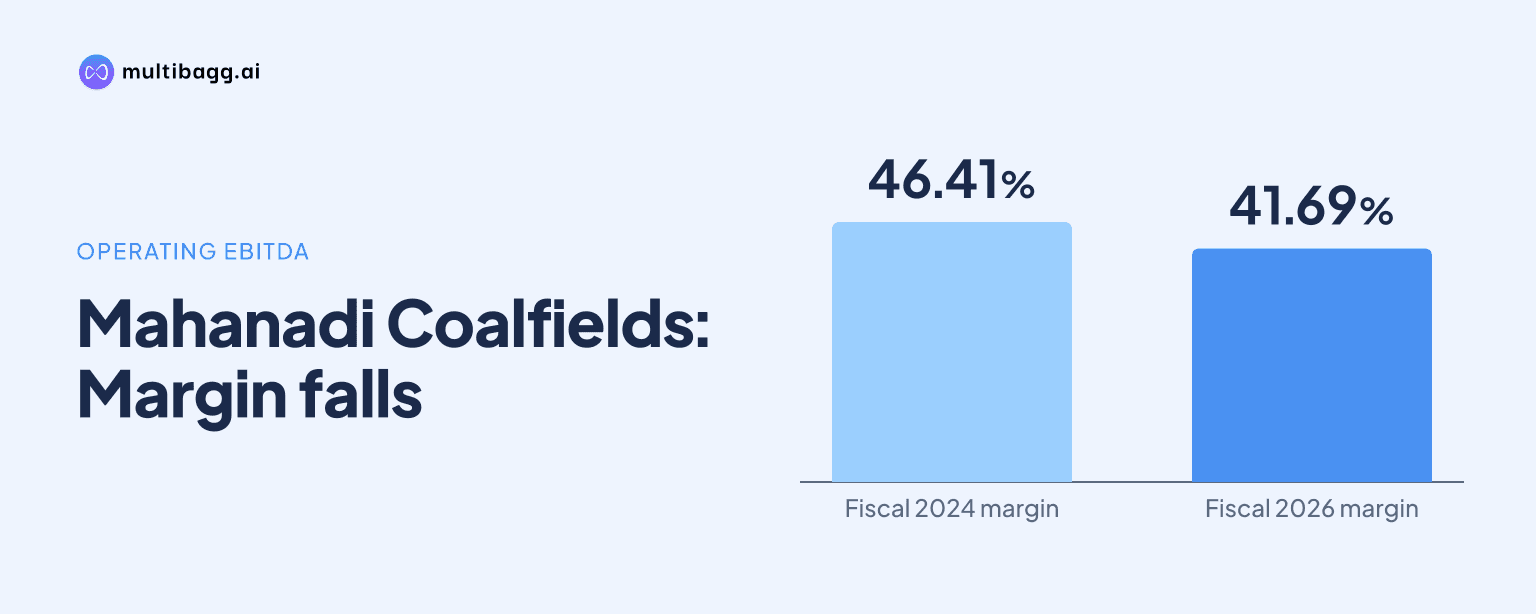
Mahanadi Coalfields Limited reported a 41.69% operating EBITDA margin in Fiscal 2026, 4.72 percentage points below Fiscal 2024’s 46.41%, because operating EBITDA declined faster than revenue from operations. Mahanadi Coalfields nevertheless recorded the highest operating EBITDA margin among the listed industry peers disclosed for their respective reporting periods.
Why did Mahanadi Coalfields’ operating margin fall to 41.69%?
Mahanadi Coalfields’ operating EBITDA margin fell to 41.69% in Fiscal 2026 because operating EBITDA declined by Rs 1,945.68 crore over two years, compared with a Rs 1,084.76 crore reduction in revenue from operations. Operating EBITDA is defined as restated profit after tax plus finance costs, taxes, depreciation and amortisation, less other income. The margin divides that measure by revenue from operations, so a faster decline in operating EBITDA reduced the ratio.
Operating EBITDA declined from Rs 14,680.92 crore in Fiscal 2024 to Rs 13,655.48 crore in Fiscal 2025 and Rs 12,735.24 crore in Fiscal 2026. Revenue from operations moved from Rs 31,634.35 crore in Fiscal 2024 to Rs 31,353.02 crore in Fiscal 2025 and Rs 30,549.59 crore in Fiscal 2026. The company reported a negative 6.86% compound annual growth rate, or CAGR, for operating EBITDA for Fiscal 2024 to Fiscal 2026, compared with negative 1.73% for revenue.
The decline was therefore a continuing two-year trend rather than solely a Fiscal 2026 movement. EBITDA margin, which uses total income as its denominator, also fell from 49.53% in Fiscal 2024 to 47.45% in Fiscal 2026. Operating EBITDA margin is the more direct measure of the company’s core operating result relative to revenue because it excludes other income from the numerator.
How did Mahanadi Coalfields’ operating margin compare with listed peers?
Mahanadi Coalfields’ Fiscal 2026 operating EBITDA margin of 41.69% exceeded each ratio in the disclosed listed-peer comparison, including Coal India’s 24.94%, Bharat Coking Coal’s negative 3.62% and National Mineral Development Corporation’s 28.87%. PT Bukit Asam reported 14.08% and Yancoal Australia reported 23.01%, both for years ended December 31, 2025 rather than March 31, 2026.
The comparison has timing and definition limits. The prospectus states that peers may calculate key performance indicators differently, and the peer companies cover public-sector coal mining, coking coal, iron ore and overseas coal operations. Coal India’s 24.94% is a consolidated measure for Fiscal 2026 that includes results of subsidiaries, including Mahanadi Coalfields and Bharat Coking Coal, so it is not an independent company-only comparison.
The margin lead also did not coincide with the fastest operating-profit direction among all peers. National Mineral Development Corporation’s operating EBITDA increased from Rs 7,010.88 crore in Fiscal 2024 to Rs 9,259.52 crore in Fiscal 2026, with a reported 14.92% CAGR. Mahanadi Coalfields’ operating EBITDA decreased over that period despite ending Fiscal 2026 with a 12.82-percentage-point margin lead over National Mineral Development Corporation.
Got a follow-up? Ask IRIS
What happened to Mahanadi Coalfields’ profit and returns?
Mahanadi Coalfields’ profit after tax, or PAT, declined to Rs 10,698.12 crore in Fiscal 2026 from Rs 11,841.55 crore in Fiscal 2024, while PAT margin fell to 31.56% from 35.25%. PAT is restated profit attributable to the period or year in the company’s restated consolidated financial information. The company reported a negative 4.95% PAT CAGR over Fiscal 2024 to Fiscal 2026.
Earnings per share declined from Rs 17.89 in Fiscal 2024 to Rs 16.35 in Fiscal 2025 and Rs 16.13 in Fiscal 2026. These earnings-per-share figures reflect the August 2026 subdivision of paid-up equity shares from 13,236,726 shares of Rs 1,000 each to 6,618,363,000 shares of Rs 2 each. Basic and diluted earnings per share were the same because the company reported no dilutive capital.
Returns also reduced as profit declined. Return on average capital employed, or RoACE, fell from 107.04% in Fiscal 2024 to 83.17% in Fiscal 2025 and 73.26% in Fiscal 2026. RoACE measures earnings before interest and tax against average capital employed, while return on net worth, or RoNW, fell from 80.56% to 53.77% as it measures profit attributable to owners against average net worth.
For the six months ended September 30, 2026, the operating EBITDA margin was 40.07%, below 40.66% in the six months ended September 30, 2025; neither period is annualised. Revenue increased by Rs 1,368.50 crore year on year to Rs 16,093.04 crore, while operating EBITDA increased by Rs 461.49 crore to Rs 6,449.19 crore. This left operating EBITDA growth below revenue growth in the half-year period as well.
Which operating indicators could affect Mahanadi Coalfields’ margin trend?
Mahanadi Coalfields’ production base was concentrated in opencast mines, which supplied 99.85% of Fiscal 2026 production of 218.31 million tonnes. The prospectus describes opencast mining as having higher recovery rates and being more cost-effective than underground mining. This concentration is relevant to the cost structure, but the disclosed data do not assign a quantified part of the Fiscal 2026 margin decline to mine type.
Coal production fell from 225.17 million tonnes in Fiscal 2025 to 218.31 million tonnes in Fiscal 2026, while coal offtake rose from 210.45 million tonnes to 211.35 million tonnes. Offtake includes coal dispatched to customers, raw coal transferred to washeries and internal or colliery consumption. Fiscal 2026 offtake represented 96.81% of production, compared with 93.46% in Fiscal 2025.
The stripping ratio was 1.50 cubic metres of overburden removed per tonne of coal extracted in Fiscal 2025 and Fiscal 2026, compared with 1.34 in Fiscal 2024. Overburden is the soil, rock and other material above coal seams that must be removed to access the coal. The prospectus states that a higher stripping ratio requires greater excavation effort, cost and time, but does not identify stripping activity as the cause of the reported margin change.
Workforce output improved in Fiscal 2026, even as total production declined. Output per manshift rose to 30.34 tonnes from 29.56 tonnes in Fiscal 2025 and 27.24 tonnes in Fiscal 2024, while year-end manpower fell to 20,602 from 21,060 a year earlier. Capital expenditure was Rs 2,929.61 crore in Fiscal 2026, close to Rs 2,907.52 crore in Fiscal 2025 but below Rs 3,839.80 crore in Fiscal 2024.
Conclusion
Mahanadi Coalfields’ 41.69% operating EBITDA margin remained above every disclosed listed-peer ratio, but the company’s internal profitability trend declined between Fiscal 2024 and Fiscal 2026. Revenue, operating EBITDA, PAT, PAT margin, RoACE and RoNW were all lower in Fiscal 2026 than two years earlier, showing that relative margin leadership and growth in earnings or returns are separate measures.
The next disclosed checkpoint is Mahanadi Coalfields’ commitment to report the key performance indicators at least annually for one year after listing, or more often if its board determines. The figures to watch are whether operating EBITDA margin improves from 40.07% in the six months ended September 30, 2026, alongside coal production, the 1.50 stripping ratio, offtake and output per manshift.