










Mahanadi Coalfields has Rs 8,334.641 crore in tax disputes
Key highlights
- Mahanadi Coalfields reports Rs 8,334.641 crore in quantified tax disputes across 111 cases.
- Mahanadi Coalfields’ 42 direct-tax cases account for Rs 8,082.046 crore, or 96.97% of the total disclosed amount.
- Nine material direct-tax matters described by Mahanadi Coalfields total Rs 5,117.020 crore.
- Mahanadi Coalfields subsidiaries have one direct-tax case involving Rs 42.05 lakh and no indirect-tax cases.
powered by IRIS
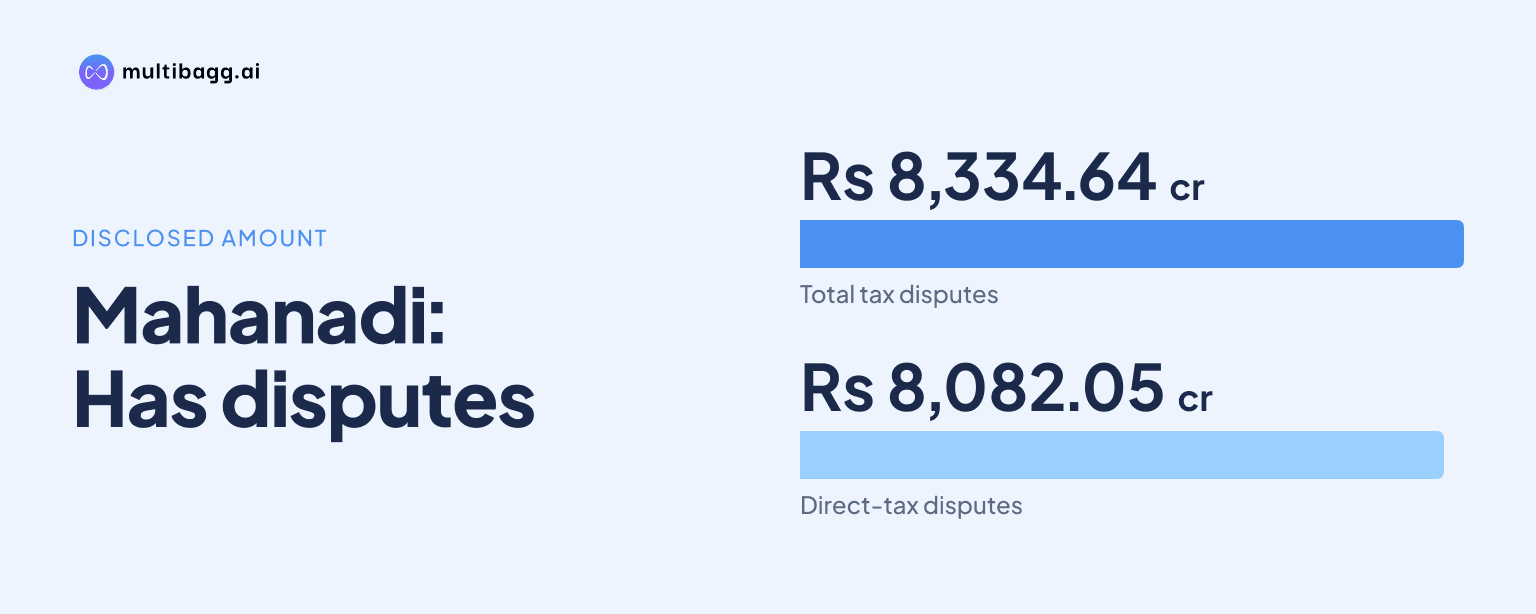
Mahanadi Coalfields Limited has Rs 8,334.641 crore in quantified tax disputes across 111 cases, with 42 direct-tax cases accounting for Rs 8,082.046 crore, or 96.97% of the disclosed amount. Mahanadi Coalfields’ material direct-tax cases before the High Court of Odisha span assessment years 2011-2012 through 2019-2020 and remain pending.
How large are Mahanadi Coalfields’ tax disputes?
Mahanadi Coalfields reports Rs 8,334.641 crore in dispute or demand across 111 tax cases, to the extent quantifiable. The disclosure separates 42 direct-tax cases carrying Rs 8,082.046 crore from 69 indirect-tax cases carrying Rs 252.595 crore; it does not describe the total as a final adjudicated payment obligation.
The distribution differs sharply by count and value. Direct tax represents 37.84% of the 111 cases but 96.97% of their quantified amount, while indirect tax represents 62.16% of cases but 3.03% of the amount. This means the reported tax-dispute value depends principally on the outcome of direct-tax proceedings rather than on the larger number of indirect-tax cases.
The phrase “to the extent quantifiable” limits what the table establishes. It records amounts in dispute or demand for Mahanadi Coalfields’ own cases, but it does not give an outcome, provision, payment schedule or expected disposal date for the full Rs 8,334.641 crore. The company separately reports one subsidiary direct-tax case of Rs 42.05 lakh, which is not included in its own 111-case table.
Why do direct-tax claims dominate Mahanadi Coalfields’ tax disputes?
Direct-tax claims dominate Mahanadi Coalfields’ tax disputes because nine material matters described in the disclosure total Rs 5,117.020 crore, with individual amounts ranging from Rs 48.323 crore to Rs 904.648 crore. These nine matters account for 63.31% of the Rs 8,082.046 crore direct-tax amount, leaving Rs 2,965.026 crore across 33 other direct-tax cases whose specific issues are not described in this section.
Five matters concern assessment years 2011-2012 through 2015-2016. The Income Tax Appellate Tribunal, Cuttack gave Mahanadi Coalfields partial relief through orders dated March 20, 2018, after which the Commissioner of Income Tax, Sambalpur filed appeals under Section 260A of the Income-tax Act, 1961 before the High Court of Odisha. Each of the five appeals is pending.
The five assessment years total Rs 3,219.785 crore, or 39.84% of Mahanadi Coalfields’ direct-tax amount. The 2015-2016 matter is the largest of this group at Rs 749.850 crore, exceeding the Rs 495.969 crore involved in 2011-2012 by Rs 253.881 crore. Although all five followed March 20, 2018 tribunal orders and the same Section 260A appeal route, the disclosure does not say they raise identical legal questions.
Got a follow-up? Ask IRIS
What issues are under challenge for assessment years 2016-2017 to 2019-2020?
Mahanadi Coalfields faces Rs 1,897.235 crore of disclosed tax effect for assessment years 2016-2017 to 2019-2020 in four High Court of Odisha applications filed by the Assistant Commissioner of Income Tax in March 2024. The applications challenge Income Tax Appellate Tribunal, Cuttack orders dated December 31, 2018, December 31, 2019, March 21, 2021 and September 29, 2021.
The four applications raise the same stated questions: whether depreciation under Section 32(1) is available on leasehold land or lease rights acquired for coal mining; whether the tribunal was justified in deleting an overburden removal adjustment disallowance; whether payments to Coal India Limited’s Rehabilitation Fund qualify as deductions under Section 37(1); and whether losses on sold, discarded or surveyed-off assets can be separately deducted. Overburden removal refers here to the accounting adjustment specifically identified in the tax challenge, while the Rehabilitation Fund is described as being maintained by Coal India Limited for rehabilitation of other loss-making subsidiaries.
The disclosed tax effect was Rs 904.648 crore for 2016-2017, Rs 517.300 crore for 2017-2018, Rs 426.964 crore for 2018-2019 and Rs 48.323 crore for 2019-2020. The 2016-2017 amount alone represents 47.68% of the four-year total, and it exceeds the 2019-2020 amount by Rs 856.325 crore.
The repeated legal questions make the treatment of mine-related lease rights, overburden accounting, Rehabilitation Fund contributions and asset write-offs material to this group of cases. However, the figures remain disputed tax effects rather than final liability determinations because Mahanadi Coalfields states that all four High Court of Odisha matters are pending. Their continued relevance to the reported amount depends on the proceedings remaining unresolved and on the tax effect not being revised through court orders or tax assessments.
Do Mahanadi Coalfields subsidiaries add to the reported tax-dispute amount?
Mahanadi Coalfields’ Rs 8,334.641 crore headline figure applies to tax proceedings involving the company, while the disclosure presents subsidiary proceedings in a separate table. That subsidiary table lists one direct-tax case involving Rs 42.05 lakh, no indirect-tax cases and a total of one quantifiable tax case.
The subsidiary amount is materially smaller than the company’s Rs 8,082.046 crore direct-tax amount, but it should not be added to the 111 company cases without changing the definition of the reported total. The disclosure does not identify the subsidiary tax issue, assessment year, forum or expected resolution date, so it provides no basis for assessing whether that Rs 42.05 lakh matter overlaps with the questions raised in the company’s High Court cases.
For subsidiaries, the disclosure also records nil criminal proceedings by or against them, nil other material proceedings by or against them, and nil regulatory actions against them. Those nil entries relate to the litigation categories disclosed for subsidiaries and do not alter the separate tax-case classification of one direct-tax matter.
Conclusion
Taken together, Mahanadi Coalfields’ quantified tax-dispute profile is concentrated in direct tax by monetary value, even though indirect-tax cases form the larger share of the 111 cases by number. The most detailed matters cover nine assessment years from 2011-2012 to 2019-2020, and the Rs 1,897.235 crore group for 2016-2017 through 2019-2020 centres on four recurring deductions and accounting questions.
The next development to watch is the status of the pending High Court of Odisha proceedings, including the five Section 260A appeals following the March 20, 2018 tribunal orders and the four applications filed in March 2024. Mahanadi Coalfields discloses neither hearing dates nor a settlement or resolution timetable, so future court orders, revised demands or changes in the number of quantified cases would determine whether the disclosed tax-dispute amount changes.