










MCL contingent liabilities rise to Rs 12,513.29 crore in six months
Key highlights
- MCL disclosed Rs 12,513.29 crore of contingent claims at 30 September 2026, up Rs 4,007.06 crore from 31 March 2026.
- Income-tax claims were Rs 8,074.83 crore at 30 September 2026, about 64.5% of MCL’s disclosed claims total.
- State-government and local-authority claims rose to Rs 1,929.88 crore, including Rs 857.38 crore of water-tax claims.
- MCL says the financial impact of the pending ORISED Act appeal is presently not ascertainable.
powered by IRIS
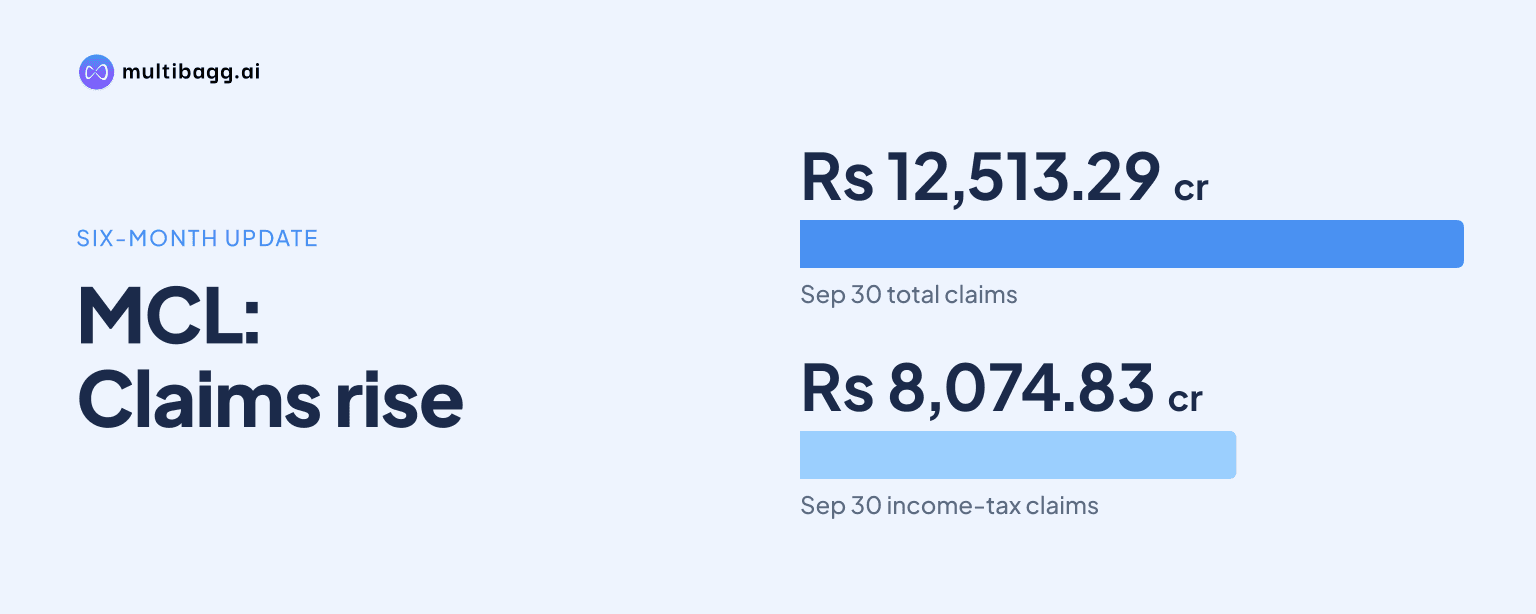
Mahanadi Coalfields Limited reported contingent liabilities of Rs 12,513.29 crore at 30 September 2026, up Rs 4,007.06 crore in six months from Rs 8,506.23 crore at 31 March 2026. MCL’s disclosed claims not acknowledged as debt were led by Rs 8,074.83 crore of income-tax claims, while an Odisha mining-land levy dispute remains unquantifiable pending Supreme Court adjudication.
Why did MCL contingent liabilities rise to Rs 12,513.29 crore?
MCL’s contingent claims increased because additions of Rs 4,352.45 crore during the six months to 30 September 2026 exceeded settlements of Rs 345.39 crore. A contingent liability is a potential obligation whose settlement depends on uncertain future outcomes; MCL has disclosed these claims as not acknowledged as debt and has not provided for them to the stated extent.
The Rs 4,007.06 crore six-month increase contrasts with the year ended 31 March 2026, when MCL’s closing contingent claims fell to Rs 8,506.23 crore from Rs 10,122.21 crore at 1 April 2025. In the six months to September 2026, central-government claims rose by Rs 3,079.94 crore, state-government and local-authority claims by Rs 944.18 crore, and other claims declined by Rs 17.06 crore after settlements.
MCL’s September 2026 closing total also exceeded Rs 7,604.62 crore at 30 September 2025 by Rs 4,908.67 crore. That comparison reflects a different movement in state claims: state-government and local-authority claims were Rs 375.56 crore at September 2025, compared with Rs 1,929.88 crore at September 2026, while central-government claims rose from Rs 5,057.24 crore to Rs 8,351.55 crore.
What income-tax claims account for MCL’s contingent liability increase?
Income-tax claims accounted for Rs 8,074.83 crore at 30 September 2026, or about 64.5% of MCL’s Rs 12,513.29 crore total disclosed claims. The income-tax amount increased by Rs 3,079.09 crore from Rs 4,995.74 crore at 31 March 2026 and by Rs 3,291.66 crore from Rs 4,783.17 crore at 30 September 2025.
The central-government subtotal was Rs 8,351.55 crore at 30 September 2026, representing about 66.7% of all claims not acknowledged as debt. Besides income tax, this subtotal comprised Rs 226.86 crore of central excise, Rs 26.70 crore of clean-energy cess, Rs 4.43 crore of service tax and Rs 18.73 crore of other claims. Central excise and clean-energy cess were largely unchanged from 31 March 2026, making income tax the principal driver of the category’s six-month rise.
MCL states that it has reviewed pending litigation and proceedings, made provisions where applicable, and does not expect the disclosed proceedings to have a material impact on its financial position. That statement does not fix a cash-payment amount: MCL says future cash outflows depend on judgments and decisions, and interest is not expected in settlements except where management holds an adverse view.
Which Odisha levies and local claims increased at MCL?
State-government and local-authority claims reached Rs 1,929.88 crore at 30 September 2026, up Rs 944.18 crore from Rs 985.70 crore at 31 March 2026. Water-tax claims were Rs 857.38 crore, royalty claims were Rs 225.08 crore and other state or local claims were Rs 823.72 crore, alongside Rs 18.52 crore of sales tax or value-added tax and Rs 5.18 crore of entry tax.
Water tax was absent from MCL’s reported state-government contingent-liability table at 30 September 2025 but stood at Rs 702.64 crore on 31 March 2026 before rising by Rs 154.74 crore by 30 September 2026. Royalty claims also increased from Rs 31.08 crore at March 2026 to Rs 225.08 crore at September 2026. Conversely, the category no longer includes the Rs 2,864.07 crore environment-clearance demand that appeared at 31 March 2025.
The state category’s change reflects both new claims and a changed treatment of the environment-clearance matter. MCL had previously disclosed demand notices alleging production beyond available environmental-clearance limits, but says it filed revision petitions before the Coal Tribunal and that a Joint Secretary and Revisional Authority set aside similar matters for different MCL projects. On that basis, MCL assessed the chance of resource outflow as remote and excluded the Rs 2,864.07 crore demand from contingent-liability reporting.
Got a follow-up? Ask IRIS
What is the unresolved ORISED Act mining-land dispute?
MCL cannot quantify any obligation from Odisha’s ORISED Act, 2004 because the related civil appeal remains pending before the Supreme Court of India and Odisha has not notified a new levy or raised a fresh demand. The Act concerned charges for use of land in mining operations; the High Court of Orissa at Cuttack struck it down, after which the State Government of Odisha filed Civil Appeal No. 1883 of 2006.
The Supreme Court’s July and August 2024 decisions in Mineral Area Development Authority versus SAIL held that states can notify or levy taxes for the use of land for mining operations from April 2005 onwards. MCL says the pending ORISED Act appeal will determine whether it has an obligation, if any, and that the financial effect is presently not ascertainable.
For MCL’s potential obligation to become measurable, the Supreme Court must finally dispose of the appeal and the relevant state action must establish the applicable levy or demand. MCL’s disclosure specifically says no new levy has been notified and no fresh demand has been raised to date, despite the 2024 Supreme Court rulings on states’ taxing power.
What other legal claims and commitments did MCL disclose?
MCL reported Rs 2,221.10 crore of claims in the “Others” category at 30 September 2026, down Rs 17.06 crore from 31 March 2026. Land compensation and other miscellaneous claims accounted for Rs 2,101.00 crore, while arbitration, civil suits and employee-related matters accounted for Rs 120.10 crore. A separate claim under litigation involving central public-sector enterprises was Rs 10.76 crore.
MCL separately reported bank guarantees of Rs 644.08 crore at 30 September 2026, compared with Rs 624.24 crore at 31 March 2026. It also reported Rs 23.59 crore of outstanding letters of credit at September 2026, whereas no such amount was reported at 31 March 2026. These instruments are disclosed separately from claims not acknowledged as debt and should not be added to the Rs 12,513.29 crore claims total without distinguishing their different mechanisms.
Capital commitments were another separate disclosure, with Rs 3,467.47 crore of estimated capital contracts remaining to be executed at 30 September 2026 and Rs 1,883.33 crore net of capital advances. The corresponding net commitment was Rs 2,354.01 crore at 31 March 2026, so the September figure was lower by Rs 470.68 crore. Commitments are contracted future spending, rather than disputed claims whose payment depends on litigation or administrative outcomes.
Conclusion
MCL’s reported contingent claims increased materially over the six months to 30 September 2026, chiefly because income-tax claims rose to Rs 8,074.83 crore and state and local claims reached Rs 1,929.88 crore. The Rs 12,513.29 crore figure represents disclosed claims not acknowledged as debt, not a confirmed cash obligation, and MCL says the eventual outflow depends on legal and administrative decisions.
The next key development is final disposal of Civil Appeal No. 1883 of 2006 concerning the ORISED Act, 2004. MCL says the financial impact cannot currently be determined because Odisha has not notified a new levy or made a fresh demand; changes in that position, along with rulings on the income-tax and other pending proceedings, would affect future disclosures.