










MCL e-auction premium fell 66%, cutting coal realizations
Key highlights
- MCL’s average e-auction premium fell 65.7% from Rs 802.07 per tonne in Fiscal 2024 to Rs 274.90 in Fiscal 2026.
- E-auction revenue fell by Rs 1,695.793 crore between Fiscal 2024 and Fiscal 2026, reducing its net-sales share to 17.88%.
- Revenue from operations per tonne dispatched declined 8.80% to Rs 1,449.65 in Fiscal 2026.
- Other income of Rs 3,349.69 crore represented 31.3% of MCL’s Fiscal 2026 profit before tax.
powered by IRIS
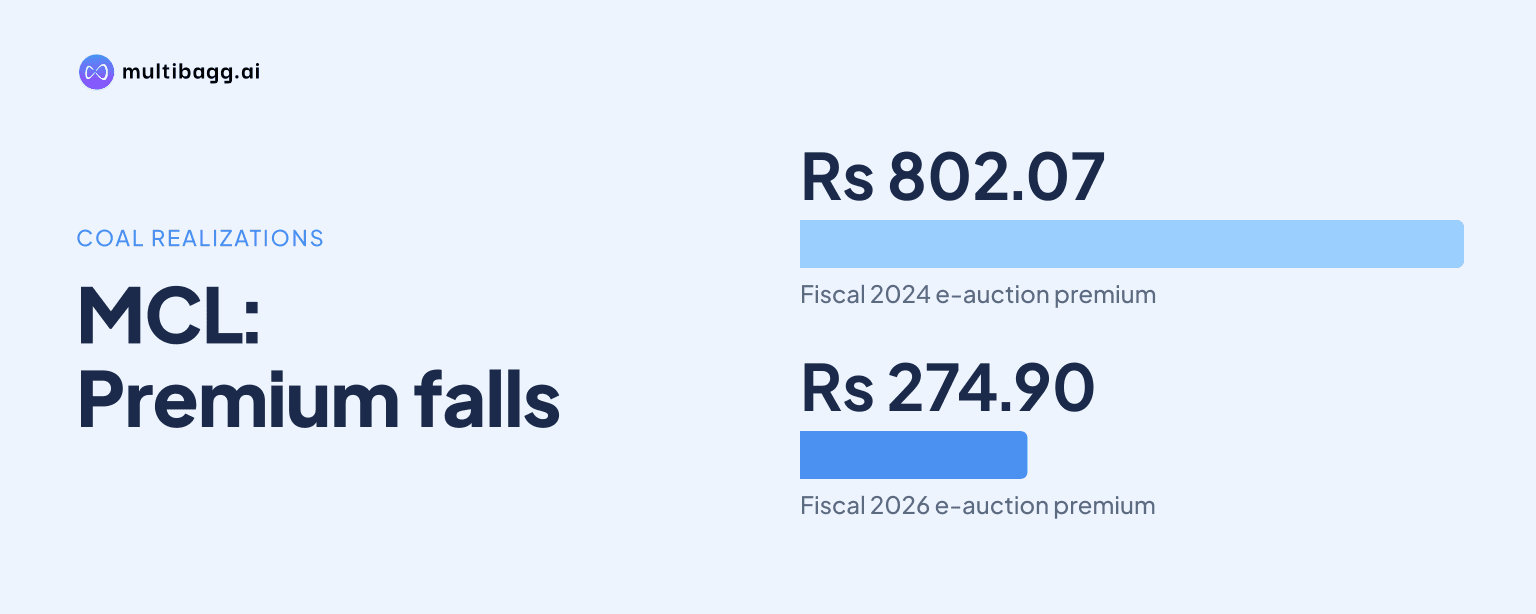
In Fiscal 2026, Mahanadi Coalfields Limited (MCL) recorded an average e-auction premium of Rs 274.90 per tonne, 65.7% below Fiscal 2024's Rs 802.07, while revenue from operations per tonne dispatched fell 8.80% to Rs 1,449.65 as Fuel Supply Agreement (FSA) and linkage sales reached 82.12% of net sales.
Why did MCL’s e-auction premium fall and cut coal realizations?
MCL’s e-auction premium fell because booked auction volumes did not keep pace with the quantity offered, reducing the market-determined premium paid above Coal India Limited’s notified coal price. The average premium declined from Rs 802.07 per tonne in Fiscal 2024 to Rs 405.02 in Fiscal 2025 and Rs 274.90 in Fiscal 2026, a Rs 527.17 per-tonne reduction over two years.
MCL offered 72.26 million tonnes (MT) through e-auctions in Fiscal 2026, against 28.65 MT in Fiscal 2024, but booked quantity increased only to 26.49 MT from 22.86 MT. The booked proportion of offered volume therefore fell from about 80% in Fiscal 2024 to about 37% in Fiscal 2026, while the total auction premium declined despite the higher quantity offered.
MCL does not set the base price for most non-coking coal sales. Coal India Limited (CIL) centrally notifies pit-head run-of-mine coal prices by gross calorific value (GCV) grade, while e-auction buyers competitively bid the premium over that price. MCL can determine offered quantity and reserve terms, but an improvement in auction-led realization depends on buyers bidding higher premiums.
How did MCL’s sales mix change between Fiscal 2024 and Fiscal 2026?
MCL shifted sales revenue towards FSA and linkage contracts, whose share of net sales rose from 77.46% in Fiscal 2024 to 82.12% in Fiscal 2026. FSA and linkage revenue increased by Rs 339.716 crore to Rs 24,515.787 crore, while e-auction revenue fell by Rs 1,695.793 crore to Rs 5,338.656 crore over the two fiscal years.
The shift reduced e-auction exposure in MCL’s revenue base. E-auction’s share of net sales fell by 4.66 percentage points, from 22.54% in Fiscal 2024 to 17.88% in Fiscal 2026. FSA-power sales are made at CIL-notified prices, while non-regulated FSA routes can include a linkage-auction premium, making the channel mix and applicable premium important to blended realization.
Power-sector customers, including captive power plants, accounted for Rs 25,433.782 crore, or 85.19%, of MCL’s Fiscal 2026 net sales revenue of Rs 29,854.44 crore. About 74% of Fiscal 2026 coal dispatches went to the power sector under long-term FSAs and memoranda of understanding (MoUs), and MCL had 241 active FSAs and MoUs covering annual contracted quantity of nearly 48.50 MT.
The 48.50 MT of contracted quantity supports demand visibility, but it also makes the balance of FSA, linkage and e-auction dispatches important for average realization. A recovery in blended realization would require a higher auction premium, a larger premium-priced sales share, changes in notified prices, or higher applicable operating charges.
Got a follow-up? Ask IRIS
How far did MCL’s unit realization and operating margin decline?
MCL’s revenue from operations per tonne dispatched declined by Rs 139.86, from Rs 1,589.51 in Fiscal 2024 to Rs 1,449.65 in Fiscal 2026. Net sales realization per tonne fell by Rs 151.56 to Rs 1,416.65, while gross sales realization declined from Rs 2,175 per tonne to Rs 1,739 per tonne across the same period.
Total operating cost per tonne produced rose from Rs 607 in Fiscal 2024 to Rs 816 in Fiscal 2026. The source defines this measure as cash operating cost, calculated as total expenses less depreciation and amortisation and finance cost. Lower per-tonne realization and higher unit cost reduced operating earnings before interest, tax, depreciation and amortisation (EBITDA) per tonne dispatched from Rs 737.66 to Rs 604.32.
MCL’s operating EBITDA margin declined by 4.72 percentage points between Fiscal 2024 and Fiscal 2026, while revenue from operations fell by Rs 1,084.76 crore to Rs 30,549.59 crore. Profit after tax declined by Rs 1,143.43 crore to Rs 10,698.12 crore and profit after tax per tonne dispatched fell from Rs 595.00 to Rs 507.65. The source also identifies MCL’s geology-driven low-GCV, high-ash coal profile as a factor that can affect profitability.
How did other income support MCL’s Fiscal 2026 profit?
Other income supported MCL’s Fiscal 2026 profit because Rs 3,349.69 crore of interest on bank deposits and mutual-fund investments equalled 31.3% of profit before tax of Rs 14,361.41 crore. Other income more than doubled from Rs 1,675.63 crore in Fiscal 2025, providing an offset to lower operating earnings.
Operating EBITDA fell by Rs 925.684 crore from Fiscal 2025 to Rs 12,735.24 crore in Fiscal 2026, yet profit before tax increased by Rs 199.85 crore. Total income rose to Rs 33,899.28 crore in Fiscal 2026 even as revenue from operations declined by Rs 803.43 crore from Fiscal 2025.
This earnings cushion came from deposits and mutual-fund investments rather than a recovery in coal pricing. MCL’s reported other income can remain material only if the underlying cash and investments are retained and continue to earn comparable returns; it does not change the decline in operating EBITDA per tonne dispatched.
Conclusion
MCL’s Fiscal 2026 profitability moderation reflected both lower auction economics and a greater share of FSA and linkage sales. The 65.7% fall in e-auction premium over two years, combined with an 8.80% decline in revenue from operations per tonne and higher operating cost per tonne, reduced operating EBITDA margin to 41.69%. Interest income of Rs 3,349.69 crore partly offset that operating pressure in reported profit.
The next factors to watch are MCL’s capacity, logistics and beneficiation plans. As of March 31, 2026, MCL had 11 projects under implementation with 274 MT of rated capacity, proposed projects adding 37.55 MT, and 96 million tonnes per annum of operational first-mile connectivity capacity. Its plan to add 27 million tonnes per annum of washery capacity could affect product mix and quality, subject to project implementation and customer demand.