










Kilburn Engineering Reports ₹153.1 Crore Q2 Revenue, Flat YoY
Key highlights
- Kilburn Engineering reported Q2 FY27 consolidated revenue of ₹153.1 crore, up 30.9% sequentially and marginally below ₹153.6 crore a year earlier.
- The company’s closing order book stood at ₹471 crore at the end of Q2 FY27.
- H1 FY27 consolidated revenue was ₹270.1 crore, down 4.5% from ₹282.8 crore in H1 FY26.
- Management indicated FY27 group revenue of ₹600 crore to ₹650 crore and FY28 revenue of ₹900 crore to ₹1,000 crore.
powered by IRIS
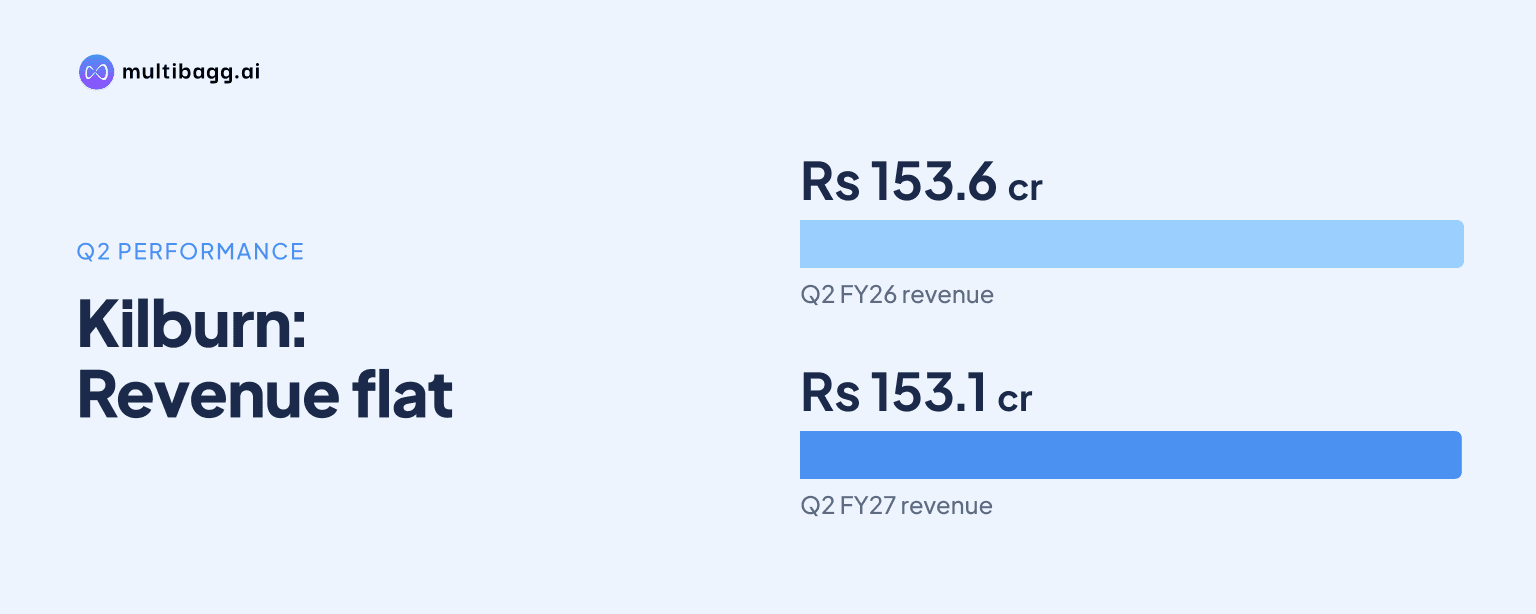
Kilburn Engineering Limited reported consolidated revenue of ₹153.1 crore in Q2 FY27, broadly flat from ₹153.6 crore a year earlier, while its closing order book stood at ₹471 crore. The quarter marked a 30.9% sequential recovery in revenue, but lower standalone revenue and profit kept the half-year performance below the previous year.
Know Kilburn Engineering inside out
Results, valuation, peers and who's buying, in one view.
What were Kilburn Engineering's Q2 FY27 financial results?
Kilburn Engineering reported consolidated revenue from operations of ₹153.1 crore for the quarter ended September 30, 2026. This was marginally lower than ₹153.6 crore in Q2 FY26, but was 30.9% higher than the preceding quarter. Consolidated profit after tax was ₹16.5 crore for the quarter, compared with a year-on-year decline of 38.7% cited in the company’s Q2 FY27 results summary.
For the first half of FY27, consolidated revenue was ₹270.1 crore, down 4.5% from ₹282.8 crore in the corresponding period of the previous financial year. Half-year consolidated profit after tax stood at ₹29.6 crore. Management linked the recovery from Q1 to the execution of delayed orders, particularly from export and capital-goods markets.
How did subsidiaries shape Kilburn Engineering's first-half performance?
Kilburn Engineering said its subsidiaries made a material contribution to group performance in the first half. Revenue from subsidiaries roughly doubled to about ₹141.7 crore in H1 FY27 from ₹73.4 crore in H1 FY26. The subsidiaries contributed more than half of group revenue during the period, according to management.
Management also said subsidiary revenue contribution grew 21% and their profit contribution increased 21% over the same period. The group’s portfolio includes businesses represented on the call by ME Energy Private Limited and Monga Strayfield Private Limited. Their contribution helped support consolidated performance while the standalone business faced the impact of delayed order flow.
The standalone business reported revenue of ₹69.5 crore in Q2 FY27, compared with ₹114.8 crore a year earlier. Standalone profit after tax declined to ₹5.7 crore from ₹18.0 crore. These figures show that the sequential group recovery did not fully offset the year-on-year pressure in the standalone operation.
What is Kilburn Engineering's order book and sector exposure?
Kilburn Engineering closed Q2 FY27 with an order book of ₹471 crore. Management described the order backlog as diversified across fertilizers, carbon black, iron and steel, and nuclear power, reducing dependence on a single end-market for near-term execution.
The company also highlighted its entry into the global fertilizer engineering, procurement and construction vendor ecosystem. This development broadens the company’s addressable market beyond domestic projects, although management did not provide separate order values, contract timing, or revenue contribution from this initiative during the available call excerpts.
Order timing remains important for the reported numbers. Management said delayed orders from export and capital-goods markets affected the standalone business. It indicated that some delayed orders are expected to contribute in early FY28, rather than within the immediate FY27 execution cycle.
Got a follow-up? Ask IRIS
What revenue outlook has Kilburn Engineering provided for FY27 and FY28?
Kilburn Engineering indicated group revenue of ₹600 crore to ₹650 crore for FY27. This guidance follows first-half consolidated revenue of ₹270.1 crore and reflects management’s expectation of stronger execution in the second half, despite delays in certain standalone orders.
For FY28, management has targeted group revenue of ₹900 crore to ₹1,000 crore. It also reiterated a 20% to 25% compound annual growth rate commitment for FY26 to FY28. The company indicated an approximately 20% EBITDA margin while discussing its operating outlook, though it did not provide a detailed segment-wise margin bridge in the information available.
The guidance should be read alongside the existing order book and timing of project execution. Capital-goods companies can see revenue shift between quarters when customer approvals, engineering milestones, exports, or site readiness are delayed. In Kilburn Engineering’s case, management has specifically identified delayed orders as a factor influencing the FY27 revenue profile.
How does the Q2 performance matter for Kilburn Engineering investors?
The Q2 numbers present two distinct trends for investors. Consolidated revenue recovered sharply on a quarter-on-quarter basis, rising 30.9% to ₹153.1 crore, and the ₹471 crore order book provides visibility across multiple industrial sectors. At the same time, revenue was broadly unchanged year-on-year and consolidated profit after tax declined year-on-year.
The weaker standalone results also remain relevant. Standalone Q2 revenue fell to ₹69.5 crore from ₹114.8 crore, while standalone profit after tax fell to ₹5.7 crore from ₹18.0 crore. The increase in subsidiary contribution partly cushioned the group-level impact, but it also means investors will need to track the sustainability of subsidiary growth and the pace of recovery in the core standalone order pipeline.
The company’s FY27 and FY28 targets provide a framework for assessing execution. Progress on fertilizer EPC vendor opportunities, conversion of the existing order book, and the timing of export and capital-goods orders will be relevant operational markers. No stock-price movement or market reaction was disclosed in the provided earnings-call material.
Conclusion
Kilburn Engineering’s Q2 FY27 performance showed a sequential revenue rebound, supported by project execution and a larger contribution from subsidiaries, but it remained flat year-on-year at ₹153.1 crore. The lower standalone revenue and profit explain why the first-half figures remained below the previous year despite the recovery from Q1.
The next key disclosures will be progress toward FY27 group revenue guidance of ₹600 crore to ₹650 crore, execution of the ₹471 crore order book, and updates on delayed export and capital-goods orders expected to contribute in early FY28. Investors will also watch whether the company advances toward its FY28 revenue target of ₹900 crore to ₹1,000 crore.