










Krystal Q2 revenue rises 46% while EBITDA margin falls to 6%
Key highlights
- Krystal reported Q2 FY'27 revenue of Rs 414.47 crore, up 46.25% year on year.
- Q2 FY'27 EBITDA excluding other income was Rs 24.86 crore, with margin at 6% versus 6.32% a year earlier.
- Employee cost increased to 75.9% of Q2 revenue from 72.3% after 33 new customer additions in the quarter.
- Krystal reported an order book of about Rs 2,980 crore expected to flow over three to three-and-a-half years.
powered by IRIS
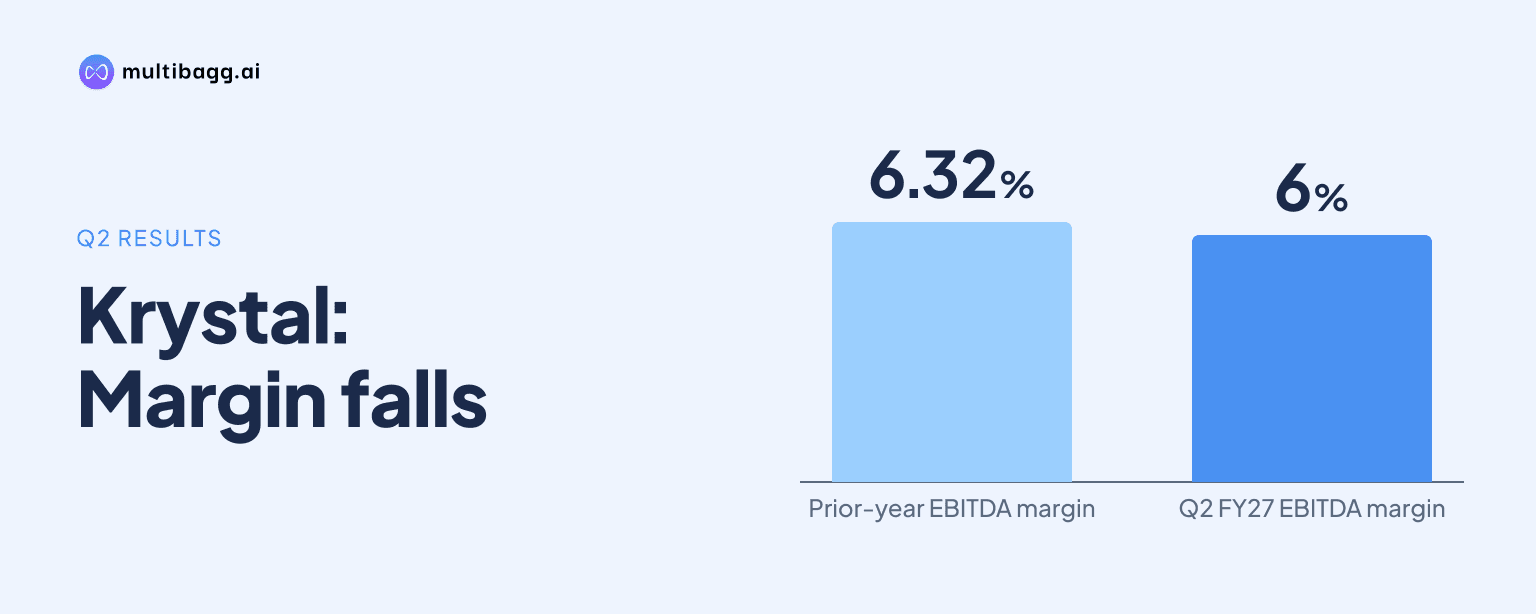
Krystal Integrated Services Limited reported Q2 FY'27 revenue of Rs 414.47 crore, up 46.25% year on year, while EBITDA margin declined to 6% from 6.32% as employee costs rose to 75.9% of revenue during the start-up of larger new contracts. Management said margins can stabilise after initial contract mobilisation.
Know Krystal Integrated Services inside out
Results, valuation, peers and who's buying, in one view.
Why did Krystal’s EBITDA margin decline in Q2 FY'27?
Krystal’s EBITDA margin declined by 32 basis points to 6% in Q2 FY'27 because larger new contracts required higher initial spending to mobilise and stabilise operations. EBITDA, or earnings before interest, tax, depreciation and amortisation, excluding other income, rose 38.82% year on year to Rs 24.86 crore, below the 46.25% revenue growth rate.
Employee cost was the principal disclosed factor, rising to 75.9% of Q2 revenue from 72.3% in Q2 FY'26. The Chief Financial Officer said lower material and other expenses as a share of revenue partly offset the increase. Management linked the higher staffing requirement to the addition of 33 customers during the quarter.
Management said a large contract normally requires more working capital and other expenses during its initial set-up than in routine monthly operations. It described this as a business-cycle effect, under which margins can dip when bigger contracts begin and later stabilise as service delivery becomes established.
How fast did Krystal grow in Q2 and H1 FY'27?
Krystal’s revenue from operations rose to Rs 414.47 crore in Q2 FY'27 from Rs 283.4 crore in Q2 FY'26 and was 14.9% above Rs 360.71 crore in the preceding quarter. H1 FY'27 revenue increased 27.82% year on year to Rs 775.18 crore from Rs 606.48 crore in H1 FY'26, making the Q2 growth rate higher than the half-year rate.
Profit after tax, or PAT, rose 41.66% to Rs 18.67 crore in Q2 FY'27 and 22.09% to Rs 36.04 crore in H1 FY'27. Management attributed Q2 PAT growing faster than EBITDA partly to a lower effective tax rate of 12.5%, compared with 16.6% a year earlier. H1 PAT margin was 4.65%, and earnings per share was reported as 25.85%.
H1 EBITDA excluding other income rose 21.39% to Rs 47.66 crore, but the margin declined to 6.15% from 6.47% in H1 FY'26. Manpower and related services generated about 91% of H1 revenue, while catering and related services accounted for up to 9%, leaving labour costs central to the consolidated margin outcome.
What contract additions are driving Krystal’s expansion?
Krystal added 59 corporate customers in H1 FY'27, including 31 in Q2, and served more than 540 customers at over 4,700 locations as of September 30, 2026. Its network comprised 33 branches, five warehouses and 49,971 on-site employees, showing the operational scale behind the higher Q2 employee-cost ratio.
Recent awards included a 24-month South-East Central Railway Bilaspur Division contract worth about Rs 26 crore and a three-year integrated facility-management contract from Maharashtra State Road Transport Corporation worth about Rs 134 crore. Krystal also disclosed work orders worth about Rs 296 crore, representing its 40% share through the LC Infra-Krystal Consortium, for sewage treatment plants and sewer networks in Pune and Nagpur.
Other wins included contracts worth about Rs 33 crore and Rs 6.6 crore from Maha Mumbai Metro Operations Corporation, a Rs 27.6 crore sanitation contract covering 563 hostels in Andhra Pradesh, and a Rs 17 crore five-year manpower contract in Pune. The disclosed mix spans railways, public transport, water infrastructure, sanitation and industrial staffing rather than one service category.
Got a follow-up? Ask IRIS
What does management expect for Krystal’s margins and order book?
Management said Krystal aspires to maintain EBITDA margins of 6.25% to 7.5% over the medium to long term. Q2 FY'27 margin of 6% and H1 margin of 6.15% were below that range. Management cited operational efficiencies, internal cost rationalisation and cross-selling multiple services to existing customers as measures intended to support the aspiration.
Krystal reported an order book of about Rs 2,980 crore, or approximately Rs 3,000 crore, which management said should flow over the next three to three-and-a-half years according to contract tenure. Management did not disclose a segment split, but described the broader business mix as about 65% government and 35% corporate.
The tender pipeline remains separate from secured orders. Krystal evaluated tenders worth more than Rs 12,000 crore and participated in bids worth about Rs 4,500 crore during the period. Management said historical conversion of new tenders has been 8% to 10%, while stressing that this was a trend rather than a committed outcome. Trade receivable days were about 118 as of September 30, 2026, in line with March 2026.
Which new businesses could change Krystal’s revenue mix?
Krystal has acquired 100% of Citelum India and begun bidding in power and city lighting under its Krystal 2.0 strategy. Management targets annual revenue of Rs 300 crore to Rs 350 crore from this vertical over the next three to four years, supported by planned investment of about Rs 100 crore in engineering capabilities, technology platforms and expansion.
Management said Citelum India brought a captive team and pre-qualification capabilities, with prior city-lighting work in Ahmedabad and Noida. It described the activity as design, installation, commissioning and operations and maintenance, or O&M, and said projects would not require Krystal to invest in operating assets.
Krystal also plans to expand solid-waste processing capacity from about 400 tonnes per day to 800 to 1,000 tonnes per day. It has secured its first solar engineering, procurement and construction order from DMER and introduced technical facility management as a separate segment for activities including electrical-plant O&M and turbine maintenance. Management did not disclose revenue, profitability or an execution timetable for those two newer activities.
Conclusion
Krystal’s Q2 results show revenue growing faster than operating profit as the company added larger contracts requiring upfront staffing and mobilisation spending. Revenue rose 46.25% to Rs 414.47 crore, EBITDA increased 38.82% to Rs 24.86 crore and margin moved down 32 basis points to 6%. The comparison with H1, where EBITDA margin was 6.15%, indicates that margin moderation extended beyond one quarter.
The next items to watch are whether recently added contracts stabilise as management expects and whether the company moves toward its stated 6.25% to 7.5% EBITDA-margin aspiration. Management also plans to execute an order book of about Rs 2,980 crore over three to three-and-a-half years, expand waste-processing capacity to 800 to 1,000 tonnes per day, and pursue Rs 300 crore to Rs 350 crore of annual city-lighting revenue over the next three to four years.