










Laser Power targets positive FY27 cash flow after inventory rise
Key highlights
- Laser Power reported inventory of Rs 946 crore at September 30, 2026, up from Rs 710 crore at the end of Q1 FY27.
- Laser Power is targeting a reduction of about 25 to 40 working-capital days by Q4 FY27 from 166 days at September 30, 2026.
- Laser Power's Q2 FY27 EPC revenue fell to Rs 104 crore from Rs 212 crore a year earlier after heavy-rain execution delays.
- Laser Power used about Rs 490 crore of initial public offering proceeds to repay borrowings during Q2 FY27.
powered by IRIS
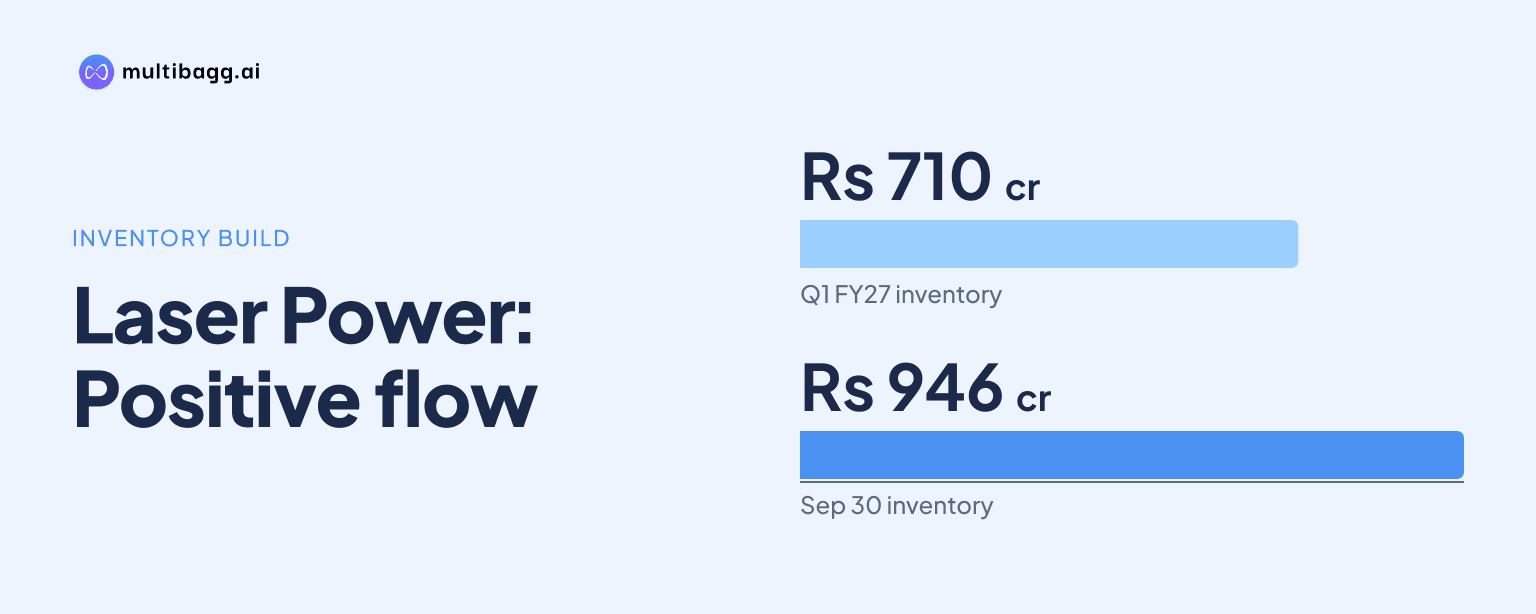
Laser Power & Infra Limited expects operating cash flow to turn positive in FY27 after heavy rains delayed engineering, procurement and construction work and lifted inventory to Rs 946 crore at September 30, 2026. Management is targeting a reduction of about 25 to 40 working-capital days by Q4 FY27 through faster execution, billing and collections.
Know Laser Power & Infra inside out
Results, valuation, peers and who's buying, in one view.
Why did Laser Power's inventory rise to Rs 946 crore?
Laser Power's inventory rose to Rs 946 crore at September 30, 2026, from Rs 710 crore at the end of Q1 FY27 because heavy rains delayed project execution. Management said the delays temporarily held up the movement of materials into completed engineering, procurement and construction, or EPC, work, certification and billing.
Working capital increased by about Rs 100 crore to Rs 1,159 crore at September 30 from Rs 1,059 crore at the end of Q1 FY27. However, working-capital days fell to 166 from 183 because of a higher quarterly revenue base, meaning the reported day metric improved even as the absolute balance rose.
Trade receivables moved differently from inventory, declining to Rs 1,382 crore at September 30 from Rs 1,416 crore at the end of Q1 FY27. Laser Power identified the inventory increase as the principal factor affecting operating cash flow, while saying that execution and billing had already started to improve.
How did rain delays affect Laser Power's Q2 FY27 results?
Rain-related execution delays reduced Laser Power's Q2 FY27 EPC revenue to Rs 104 crore from Rs 212 crore in Q2 FY26, while manufacturing revenue increased to Rs 524 crore from Rs 404 crore. Manufacturing growth of 29.9% year on year therefore offset part of the 50.9% fall in EPC revenue.
Laser Power reported total Q2 FY27 revenue from operations of Rs 628 crore, up 2.1% year on year and 20.5% sequentially. Earnings before interest, tax, depreciation and amortisation, or EBITDA, was Rs 76 crore, with a 12.1% margin against 13.0% a year earlier; management attributed the decline in EPC revenue and EBITDA to the weather disruption.
For H1 FY27, manufacturing revenue increased 13.8% to Rs 906 crore, while EPC revenue declined 10.7% to Rs 243 crore. Total H1 revenue rose 7.5% to Rs 1,150 crore, EBITDA rose 7.0% to Rs 142 crore and profit after tax increased 7.2% to Rs 52 crore, indicating that the first-half pressure was concentrated in EPC execution.
How does Laser Power plan to make cash flow positive in FY27?
Laser Power expects positive FY27 operating cash flow as manufactured orders are dispatched and EPC projects progress through installation, certification and billing. The planned cash conversion depends on inventory becoming executed work and invoices, followed by collection of receivables from customers.
Management is targeting an improvement of about 25 to 40 working-capital days by Q4 FY27 from the 166 days reported at September 30, 2026. It cited disciplined procurement, better execution, faster certification, timely billing and stronger collections as the operational measures behind that target, without providing an inventory target in rupees.
The seasonal revenue pattern is central to that plan. Laser Power said it typically records about 40% to 42% of full-year revenue in the first half, leaving 58% to 60% for the second half as projects are executed, which gives H2 FY27 greater scope to release delayed inventory and raise billings.
Got a follow-up? Ask IRIS
What supports Laser Power's execution and cash-conversion plan?
Laser Power had an order book of about Rs 2,543 crore at September 30, 2026, comprising Rs 1,303 crore of manufacturing orders and Rs 1,240 crore of EPC orders. This order base provides work for H2 FY27, but its conversion to cash still requires timely procurement, installation, certification and collection.
The company secured about Rs 449 crore of orders in H1 FY27, including its first commercial high-temperature low-sag, or HTLS, conductor and reconductoring order from Power Grid worth Rs 72.76 crore. It also received a Rs 44 crore CESC order for 33 kilovolt and 220 kilovolt underground cabling, its first 220 kilovolt underground transmission project.
Management said the CESC project has an execution timeline of about one year from the call date. Laser Power also said it uses its own manufactured cables and conductors in EPC work, linking manufacturing dispatches with project execution and making the pace of certification and billing relevant to working-capital conversion.
How has debt repayment changed Laser Power's finance costs?
Laser Power used about Rs 490 crore of initial public offering proceeds during Q2 FY27 to repay identified borrowings. Finance cost declined sequentially to about Rs 33 crore in Q2 from Rs 36 crore in Q1 FY27, while total borrowings stood at about Rs 499 crore on September 30, 2026.
Management said Q2 FY27 captured only a partial-period benefit because repayment was completed during the quarter. H1 finance cost was Rs 68 crore, compared with Rs 64 crore in H1 FY26, reflecting borrowing costs incurred before the initial public offering proceeds were deployed in Q2.
Laser Power expects the interest-cost benefit to be more visible in H2 FY27 and has guided for EBITDA margin to stabilise in a range of 12.5% to 13.0%. That outlook compares with the 12.1% Q2 FY27 margin and depends, according to management, on improved operating performance alongside lower finance costs.
Conclusion
Laser Power's positive FY27 operating-cash-flow objective relies on reversing the Q2 working-capital build, particularly inventory of Rs 946 crore created by rain-delayed EPC execution. Manufacturing revenue of Rs 524 crore in Q2 FY27 helped support total revenue, but the cash outcome depends on project materials advancing into certified work, invoices and collections.
The next disclosed milestones are the Q4 FY27 target to reduce working-capital days by about 25 to 40 days from 166 days and management's expectation of positive FY27 operating cash flow. H2 execution of the Rs 2,543 crore order book, including the Rs 72.76 crore Power Grid HTLS order and the Rs 44 crore CESC project, will determine progress against those plans.